Homeowners Are Happy! Renters? Not So Much.
When people talk about homeownership and the American Dream, much of the conversation revolves around the financial benefits of owning a home or condominium. However, two recent studies show that the non-financial benefits might be even more valuable.
In a recent survey, Bank of America asked homeowners: “Does owning a home make you happier than renting?” 93% of the respondents answered yes, while only 7% said no. The survey also revealed:
- More than 80% said they wouldn’t go back to renting
- 88% agreed that buying a home or condo is the “best decision they have ever made”
- 79% believed owning a home or condo has changed them for the better
Those surveyed talked about the “emotional equity” that is built through homeownership. The study says more than half of current homeowners define a home as a place to make memories, compared to 42% who view a home as a financial investment. Besides building wealth, the survey also showed that homeownership enhances quality of life:
- 67% of current homeowners believed their relationships with family and loved ones have changed for the better since they bought a home
- 78% are satisfied with the quality of their social life
- 82% of homeowners said they were satisfied with the amount of time they spend on their hobbies and passions since purchasing a home
- 75% of homeowners pursued new hobbies after buying a home
Homeowners seem to be very happy.
Renters Tell a Different Story…
According to the latest Zillow Housing Aspirations Report, 45% of renters regret renting rather than buying — more than five times the share of homeowners (8%) who regret buying instead of renting. Here are the four major reasons people regret renting, according to the report:
- 52% regret not being able to build equity
- 52% regret not being able to customize or improve their rentals
- 50% regret that the rent is so high
- 49% regret that they lack private outdoor space
These two studies prove that renting is just not the same as owning.
Bottom Line
There are both financial and non-financial benefits to homeownership. As good as the “financial equity” is, it doesn’t compare to the “emotional equity” gained through owning your own home. Thinking of starting your search for the perfect place to call your own? Contact the Ann Arbor Condo specialists with The Bouma Group at 734-761-3060 or info@condohotline.com today!
Stop Wondering What Your Budget Is & Get Pre-Approved!

In many markets across the country, the number of buyers searching for their dream home or condo outnumbers the number for sale. This has led to a competitive marketplace where buyers often need to stand out. One way to show that you are serious about purchasing is to get pre-approved for a mortgage before starting your search.
Even if you are not in an incredibly competitive market, understanding your budget will give you the confidence of knowing whether or not your dream condo is within your reach.
Freddie Mac lays out the advantages of pre-approval in the ‘My Home’ section of their website:
“It’s highly recommended that you work with your lender to get pre-approved before you begin house hunting. Pre-approval will tell you how much home you can afford and can help you move faster, and with greater confidence, in competitive markets.”
One of the many advantages of working with a local real estate professional is that many have relationships with lenders who will be able to help you through this process. Once you have selected a lender, you will need to fill out their loan application and provide them with important information regarding “your credit, debt, work history, down payment and residential history.”
Freddie Mac describes the ‘4 Cs’ that help determine the amount you will be qualified to borrow:
- Capacity: Your current and future ability to make your payments
- Capital or cash reserves: The money, savings, and investments you have that can be sold quickly for cash
- Collateral: The home, or type of home, that you would like to purchase
- Credit: Your history of paying bills and other debts on time
Getting pre-approved is one of many steps that will show sellers that you are serious about buying, and it often helps speed up the process once your offer has been accepted.
Bottom Line
Many potential buyers overestimate the down payment and credit scores necessary to qualify for a mortgage. If you are ready and willing to buy, you may be pleasantly surprised at your ability to do so today. Contact us at The Bouma Group, Realtors and we can give you a list of local mortgage lenders that have wowed our clients! 734-761-3060 or info@condohotline.com Check out Ann Arbor Condos here!
2 Myths Holding Back Condo Buyers
Freddie Mac recently released a report entitled, “Perceptions of Down Payment Consumer Research.” Their research revealed that,
“For many prospective homebuyers, saving for a down payment is the largest barrier to achieving the goal of homeownership. Part of the challenge for those planning to purchase a home is their perception of how much they will need to save for the down payment…
…Based on our recent survey of individuals planning to purchase a home in the next three years, nearly a third think they need to put more than 20% down.”
Myth #1: “I Need a 20% Down Payment”
Buyers often overestimate the funds needed to qualify for a home loan. According to the same report:
22% of renters and 31% of homeowners believe lenders require 20% or more of a sale price as a down payment for a typical mortgage today. And,
“If a 20% down payment was required, 70% of those who were planning to buy a home in the next three years said it would delay them from purchasing and nearly 30% indicated they would never be able to afford a home.”
While many believe at least 20% down is necessary to buy the home or condo of their dreams, they do not realize programs are available which permit as little as 3%. Many renters may actually be able to enter the housing market sooner than they ever imagined!
Myth #2: “I Need a 780 FICO® Score or Higher to Buy”
Many either don’t know or are misinformed concerning the FICO® score necessary to qualify, believing a ‘good’ credit score is 780 or higher.
To debunk this myth, let’s take a look at Ellie Mae’s latest Origination Insight Report, which focuses on recently closed (approved) loans. As indicated in the chart above, 52.4% of approved mortgages had a credit score of 600-749.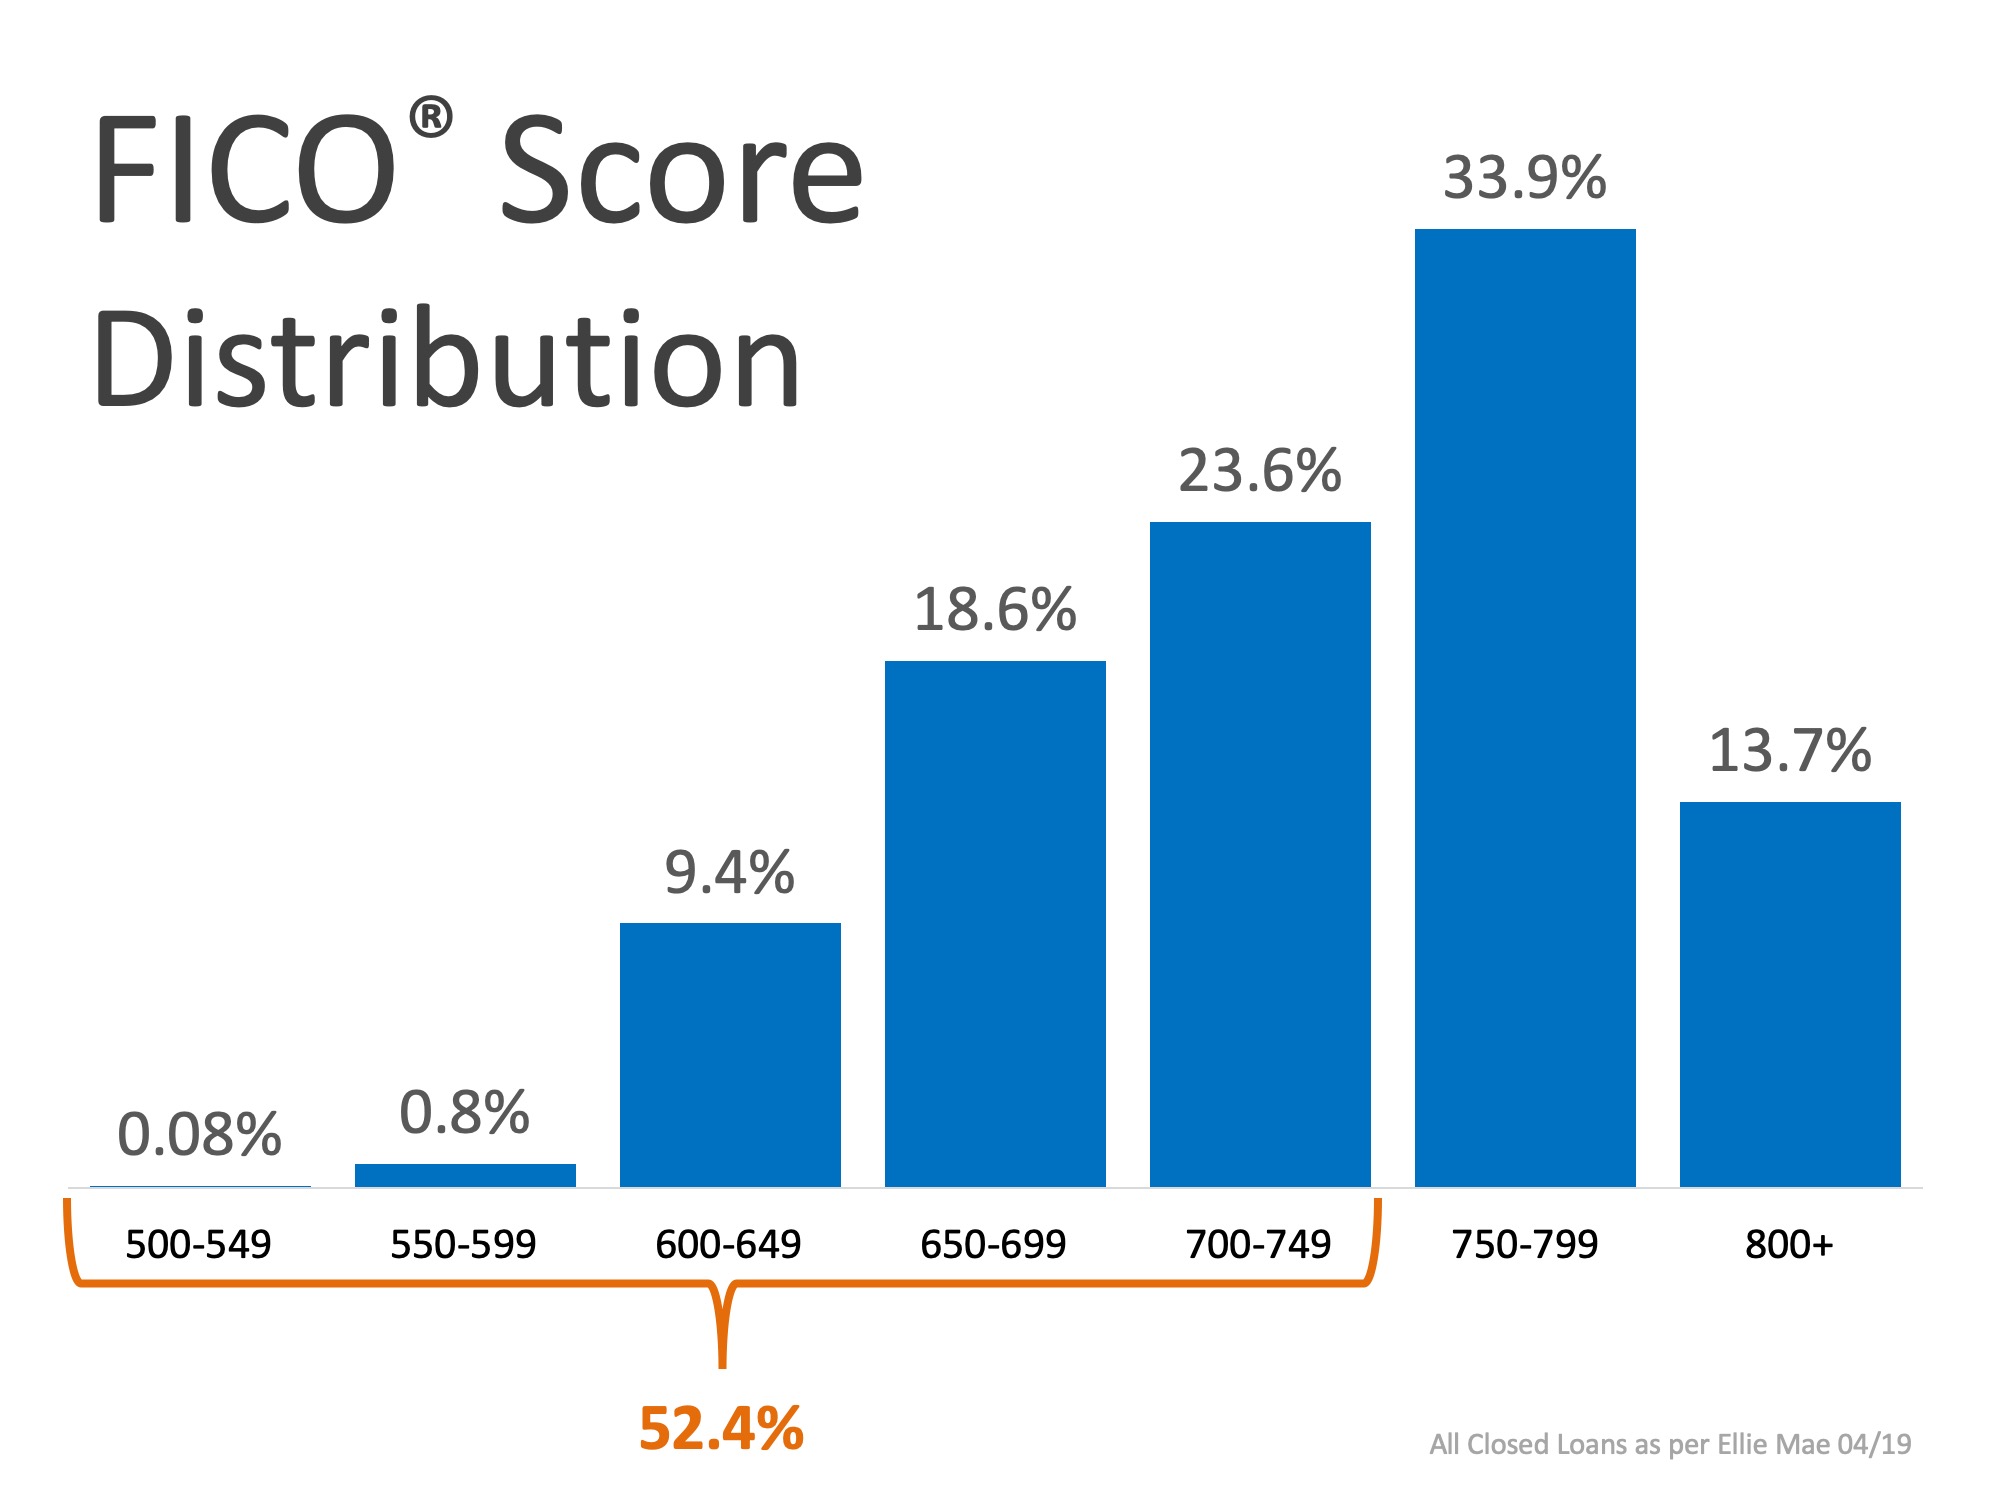
Bottom Line
Whether buying your first condo or moving up to your dream home, knowing your options will make the mortgage process easier. Your dream may already be within your reach! Contact us, the Ann Arbor Condo specialists to begin your new condo search at 734-761-3060 or info@condohotline.com.
4 Tips for Making a Competitive Offer
So, you’ve been searching for that perfect place to call ‘home,’ and you’ve finally found it! The price is right and in such a competitive market you want to make sure you make a good offer so that you can guarantee that your dream of making this condo yours comes true!
Below are 4 steps provided by Freddie Mac to help buyers make offers, along with some additional information for your consideration:
1. Determine Your Price
“You’ve found the perfect condo and you’re ready to buy. Now what? Your real estate agent will be by your side, helping you determine an offer price that is fair.”
Based on your agent’s experience and key considerations (like similar condos recently sold in the same area or the condition of the condo and what you can afford), your agent will help you to determine the offer that you are going to present.
Getting pre-approved will not only show the sellers that you are serious about buying, but it will also allow you to make your offer with confidence because you’ll know that you have already been approved for a mortgage in that amount.
2. Submit an Offer
“Once you’ve determined your price, your agent will draw up an offer, or purchase agreement, to submit to the seller’s real estate agent. This offer will include the purchase price and terms and conditions of the purchase.”
Talk with your agent to find out if there are any ways in which you can make your offer stand out in this competitive market! A licensed real estate agent who is active in the complexes you are considering will be instrumental in helping you put in a solid offer.
3. Negotiate the Offer
“Oftentimes, the seller will counter the offer, typically asking for a higher purchase price or to adjust the closing date. In these cases, the seller’s agent will submit a counteroffer to your agent, detailing their desired changes, at this time, you can either accept the offer or decide if you want to counter.
Each time changes are made through a counteroffer, you or the seller have the option to accept, reject or counter it again. The contract is considered final when both parties sign the written offer.”
If your offer is approved, Freddie Mac urges you to “always get an independent home inspection, so you know the true condition of the unit.” If the inspector uncovers undisclosed problems or issues, you can discuss any repairs that may need to be made with the seller or even cancel the contract altogether.
4. Act Fast
The inventory of condos listed for sale has remained well below the 6-month supply that is needed for a ‘normal’ market. Buyer demand has continued to outpace the supply of homes for sale, causing buyers to compete with each other for their dream homes.
Make sure that as soon as you decide that you want to make an offer, you work with your agent to present it as quickly as possible.
Bottom Line
Whether buying your first home or condo or your fifth, having a local real estate professional who is an expert in his or her market on your side is your best bet in making sure the process goes smoothly. Let’s talk about how we can make your dream of home ownership a reality! We are the Ann Arbor Condo specialists, give us a call today at 734-761-3060 or info@condohotline.com.
How to Buy a Condo in One Year: A Step-by-Step Guide
Let’s start the Spring off right. If you’ve been dreaming of a new condo, it’s time to get started! Here’s a month-by-month guide to planning for and buying a new condo.
Month 1: Brush Up on Your Market Knowledge
 The best way to get started? Brush up on your real estate knowledge. Scour the market with a fine-tooth comb. Check out things like current inventory in your city, average sales prices, and the listing-to-sales-price ratio.
This research will help you familiarize yourself with the market. Check out Ann Arbor Condo complexes here!
Month 2: Address Your Budget
Let’s finalize our budget shall we? The easiest way to do this is to get pre-approved for a mortgage.
Meet with a lender (let us know if you’d like a recommendation) to review your finances. The lender will go over your financial history, and then let you know what the bank is willing to lend you.
Now you have an idea of what your mortgage will be and what you can afford in a condo.
Month 3: Find Your Perfect Location
 Do some soul searching. Where will you be happiest? Explore locations based on their job market, housing affordability, and overall quality of life. The goal is to narrow down your search to one city.
If you have the means, try to take some time off to go and visit a few areas. Once you find an area, it’s time to narrow your search down even further by pinpointing specific complexes or parts of town that will best meet your needs.
Month 4: Find the Right Agent
Find the right real estate agent to help you buy a condo. Trust us: they’ll save you time, money, and more than a few headaches.
If you need any recommendations, let us know. We have more than a few ideas.
Month 5: Define Your Dream Home
 Now is the fun part! Start putting together a list of everything you want in your dream home. We recommend starting by defining your “must-have” features. Think of the things you can’t live without. That’s a great place to start.
It’s also important to know the difference between “must-have” (i.e. you need 3 bedrooms and 2 bathrooms) and “nice-to-haves” (it would be nice to have granite countertops, but you can also live without them.)
Month 6-7: Begin Searching
Use a handy home search tool like ours to begin browsing homes for sale in your target area. Once you find a home that you like, it’s time to schedule a tour.
Private tours are often better than traditional open houses because you have more time to walk through the unit, without the pressure of competing with other potential buyers.
At some point in your home-search journey, you’re likely to come across at least one that calls your name.
Month 8: Fall in Love and Make an Offer
 You’ve found the one; now make an offer!
Work closely with your agent to compare recently sold condos in the area and craft the perfect offer.
Ask your agent for their advice—like whether or not they think the price is right for this home, as well as what other contingencies you might want to include in your offer. This is when your real estate agent will prove truly valuable: they’ll be able to provide useful insight in order to help you get the home of your dreams for the best possible price.
Month 9: Schedule All the Things
Let’s get down to business. It’s time to negotiate with the seller, schedule an inspection, have your real estate agent complete any re-negotiations (based on that inspection), and get the condo appraised by a professional.
You’ll also have to take care of some more paperwork to finalize your mortgage loan.
Month 10 – 12: Let’s Start Closing
 Next, you’ll start the closing process.
Buckle up, because we’re in it for the long haul! Here’s where you’ll finalize your mortgage approval (this requires a ton of paperwork) and meet with an attorney to set closing dates and sign paperwork prior to closing. This is also the time when you’ll review closing fees and the exact monthly costs for your condo.
At the end of it all comes the close. You’ll pay the remaining closing fees, sign all the paperwork, and collect your keys Congratulations! You just bought a home!!!
Ready to Begin?
We’re ready to help. Give us a call today at 734-761-3060 or info@condohotline.com to get started.
Ann Arbor Condo Report – March 2019
Spring Inventory Sees a Spike
If you’re looking to buy an Ann Arbor condo, now is the time to do so! There has been a large increase in new listings, from 69 units to 90, resulting in a 30% increase. Further, listing prices have also experienced a 13.2% drop from $377,729 to $327,774 this past month. Unfortunately new inventory has been slower to exit the market, with only 29 condos selling comparative to the 35 last March – a 17% decrease. Unfortunately, the average days on the market is 52 days, a massive 160% rise. There has been a 9% increase in selling prices though, $278,132 versus $303,492.
Looking at the year-to-date statistics, there has been 171 units sold since last March, a 9% increase from the 147 the previous year. Cumulatively, the average listing price is $337,421, which is a 8% in comparison to $367,749 to the year prior. Thus far, 99 condos have been sold and last year 80 were sold at this time – a 23.7% increase. There was a 3.7% in the ASP from $288,887 to $300,060.
Whether you are looking to buy a condo or are considering selling, contact the condo specialists with The Bouma Group at (734)761-3060 or email info@condohotline.com. Stay up-to-date on all of your Ann Arbor condo needs by checking back here!
Saving up for a New Home or Condo? Here Are All the Costs You Need to Know
Once you’ve found the perfect home or condo and secured the loan, all that’s left to do is start chipping away at those mortgage payments…right? In actuality, there are a handful of other, often-overlooked expenses that come with buying, but as long as you know what you’re getting into, they’re plenty manageable.
Take a look at our comprehensive list of all the costs of buying a home or condo.
One-Time Payments & Closing Costs

Closing Costs
For buyers, closing costs are typically low and range from 2-5% of your purchase price. A lot of these costs are one-time expenses, and totals can vary from state-to-state.
If you want a better idea of what closing costs could be for you, check out this helpful guide on the average payments for each state.
Miscellaneous Fees
There are quite a bit of one-time fees bundled into your closing costs, but most of them are pretty inexpensive. Some of the most common expenses include the home inspection, appraisal, credit report, deed recording, land survey, notary fees, title insurance, and document prep fees.
Recurring Payments

Mortgage Payments
Mortgage payments are the most obvious cost when buying a home. These are your predictable, monthly payments decided by both the final price of your home and your down payment—in addition to a few other bundled costs. A larger down payment means a smaller mortgage payment, and it’s a good idea to pay this off quickly, since it will accumulate interest.
Property Taxes
Property tax payments don’t go towards just one thing—they actually cover quite a bit, like road construction, community maintenance, public works, and local government salaries. The exact amount you’ll pay in property tax is calculated by the county based on your home’s value, and the rates tend to rise and fall over time. Many buyers pay their property taxes through an escrow account set up by the lender.
Homeowner’s Insurance
It’s better to have insurance and not need it than need insurance and not have it, so homeowner’s insurance is pretty crucial to home owning. While it’s almost always required when you get a mortgage and then bundled into your monthly payments, be sure to double-check that you’re covered.
Private Mortgage Insurance
If you can’t afford a 20% down payment on your home, you’ll have to pay PMI as a way to ensure that the lender won’t go under if you default on your loan. You don’t have to pay PMI forever—it ends once you pay off 78% or more of the principal amount—but until then, expect to pay up to 2% of your loan amount annually.
HOA Fees
Moving to a neighborhood with an HOA? Your dues can range anywhere from under a hundred dollars to over a thousand, but they come with perks like landscaping and exterior maintenance, and some even include added benefits like swimming pools and fitness centers. Not all neighborhoods have an HOA, but your agent can tell you what your payments will be if yours does.
Utilities
Lastly, utility fees can come as a surprise to new homeowners who are used to renting. Depending on the size of your home, you can expect to pay a few hundred dollars per month for water, electricity, heating and cooling, and trash services. If you’re curious what your utility bills might look like, just ask your agent, and they can likely secure a few statements from the past owners.
Ready to Make an Offer?
When it comes to buying a home, the most important thing you can do is be prepared. While there are a handful of costs to keep in mind, the satisfaction of calling a place your own is well-worth it in the end.
Are you ready to get started on your home-buying journey? With years of professional and local experience, our condo professionals at The Bouma Group knows all about navigating the expenses that come with buying. Give us a call today at 734-761-3060 or info@condohotline.com to get a better idea of your costs, and let’s get started!
Get Prepared to Spring Ahead of the Condo Competition!
Spring brings two things: more buyers & more sellers! Get prepared now to stand out in the crowd!
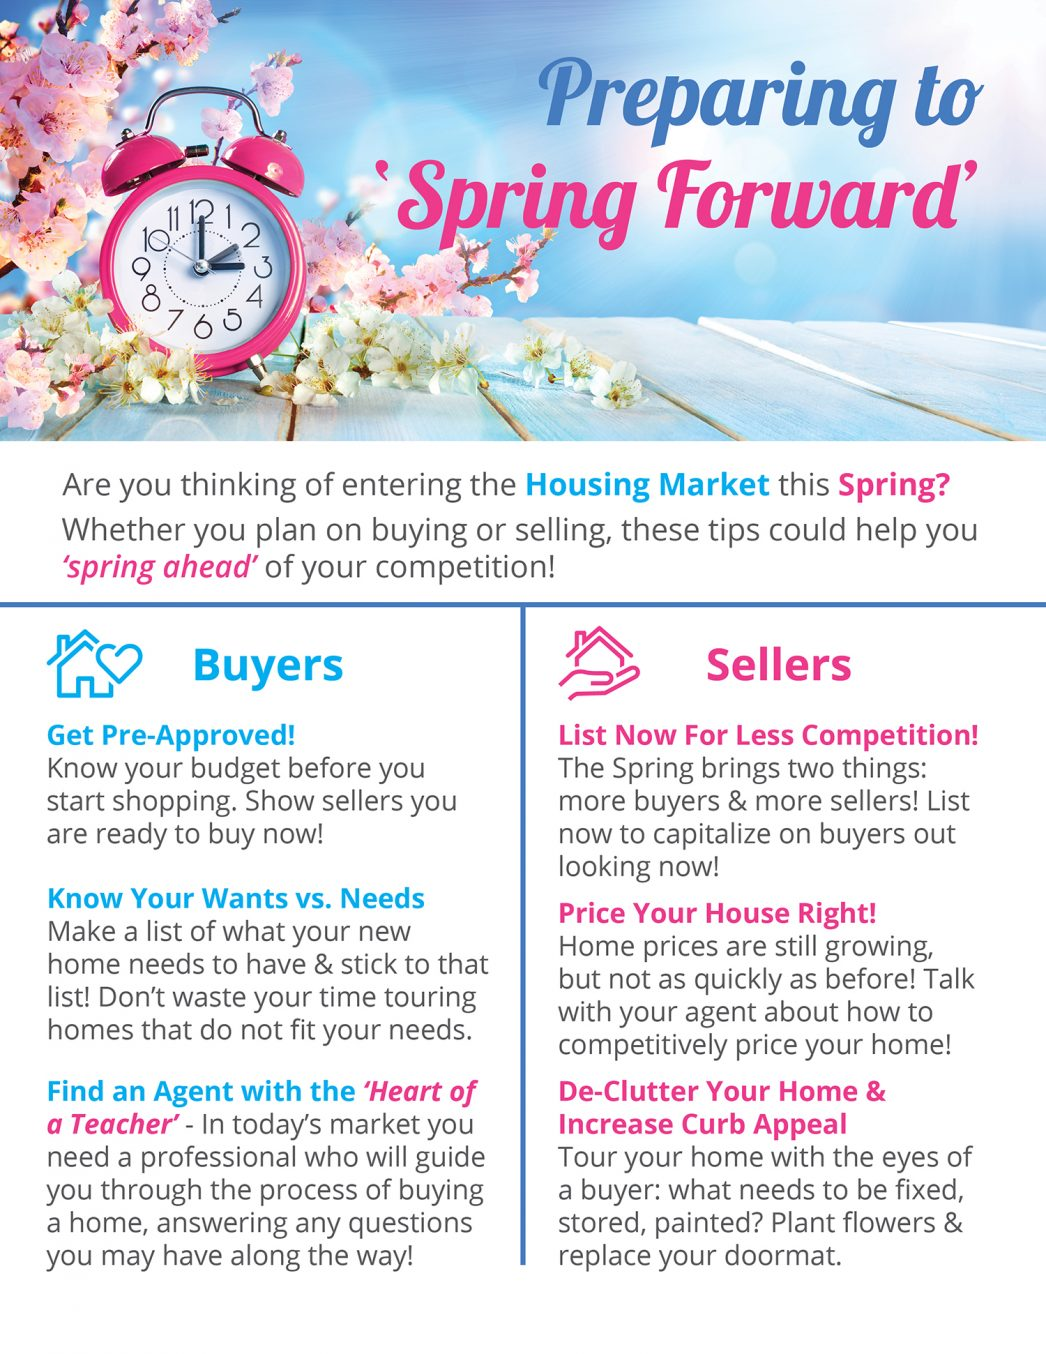
Whether you plan on buying or selling an Ann Arbor Condo, contact the real estate specialists with The Bouma Group to get the answers you need! 888-581-6923 or info@bouma.com.
No Worries… Condo Prices Coming in for a SOFT Landing

Condo prices have appreciated considerably over the last five years. This has some concerned that we may be in for another dramatic correction. However, recent statistics suggest condo values will not crash as they did a decade ago. Instead, this time they will come in for a soft landing.
The previous housing market was fueled by an artificial demand created by mortgage standards that were far too lenient. When this demand was shut off, a flood of inventory came to market. This included heavily discounted distressed properties (foreclosures and short sales).
Today’s market is totally different. Mortgage standards are tighter than they were prior to the last boom and bust. There is no fear that a rush of foreclosures will come to market. The Mortgage Bankers’ Association just announced that foreclosures are lower today than at any time since 1996.
Case Shiller looks at the percentage of appreciation as compared to the same month the year prior. Here is a graph of their findings over the last ten months:

As we can see, home price appreciation is softening as more inventory comes to market. This shows that real estate prices are not crashing, but merely returning toward historic appreciation numbers of 3.6% annually.
Bottom Line
Home and condo prices are leveling off. Long term, that is a good thing for the housing market. It’s especially good for condo buyers! Contact us today at 888-581-6923 to learn more about the Ann Arbor Condo market and your purchasing options!
Condo Buying Terminology: A Cheat Sheet
Buying a condo shouldn’t be rocket science. You find the perfect place, make an offer to the seller, pay a couple of fees, and bam! You just bought a home.
However, buying a condo actually has a lot of moving parts which include a number of funny real estate terms you’ve probably never heard before. Are Realtors and real estate agents even speaking English anymore?
To help you out, we’ve come up with a cheat sheet so you’ll know exactly what we are talking about when we explain the home-buying process.
Pre-Approval
If you meet with an agent before you begin looking for condos, they’ll likely recommend you get pre-approved for a mortgage. Mortgage pre-approval is the best first step to buying a condo, because it essentially sets your budget for you.
Pre-approval involves sitting down with a lender to discuss your financial portfolio. This includes your credit score, borrowing history, outstanding debts, annual income, and any assets you have. After reviewing all of this, the lender gives you an exact number: that’s how much the bank is willing to lend you.
Not only is your budget set, sellers will take you more seriously because they know you can qualify for enough loan to support your offer.
Earnest Money
Defined loosely, earnest money is the money you pay to confirm a contract. When you’re buying a condo, this is essentially a good faith deposit. It lets the seller know that you’re serious—serious enough to go ahead and put money down.
This money sits in a joint account (called an “escrow” account) held by both the buyer and seller. When the purchase is finalized, the earnest money goes toward the buyer’s down payment.
Due Diligence
Due diligence refers to the period of time after the seller has accepted a buyer’s offer. This is the time when you as the buyer can schedule inspections, confirm financing, and make sure that buying this unit is in your best interest.
Now’s the time to do some research! Have it inspected by a professional to ensure nothing is wrong with it, consult public records to learn more about its past home ownership, as well as any environmental issues in the neighborhood, and work with your lender to make sure this is a good financial decision.
So…. Are Realtors and Agents the Same Thing?
Yes and no. The primary difference between REALTOR®s and real estate agents is the National Association of Realtors, also known as the NAR. The NAR is a professional organization of real estate brokers that abides by a specific Code of Ethics that all REALTOR®s are required to follow.
A real estate agent works under a brokerage, but is not necessarily a licensed NAR member.
Let’s Find Your Dream Condo Together
We’ll never hide behind big words when it comes to helping you find the place that’s right for you.
Give us a call today at 734-761-3060 or email info@condohotline.com to begin your home-buying journey.