
What Are Contingencies in a Condo Purchase?
Quick answer: Contingencies are conditions written into a Real Estate purchase agreement that must be met before the sale can close. They protect both buyers and sellers by creating defined exit points if specific circumstances, like a failed inspection or financing issue, arise during the transaction.
Buying a condo in Ann Arbor is an exciting step. But between signing the offer and getting the keys, there’s a lot that can happen. That’s where contingencies come in.
If you’ve been browsing listings on Condo Hotline or talking with a Realtor, you’ve probably heard the term thrown around. But what does it actually mean, and why does it matter so much when purchasing a condo specifically? This guide breaks it all down: what contingencies are, why they exist, which types apply to condo purchases, and how they protect everyone at the table.
What Does “Contingency” Mean in Real Estate?
A contingency is a clause in a purchase agreement that makes the sale conditional on certain events or criteria being met. Think of it as a built-in safety net. If the condition isn’t satisfied within the agreed timeframe, the buyer typically has the right to walk away from the deal. Often, their earnest money deposit will be returned.
Contingencies aren’t a sign of distrust. They’re standard practice. They simply acknowledge that real estate transactions are complex, and things don’t always go as expected.
Why Are Contingencies Necessary When Buying an Ann Arbor Condo?
Purchasing a condo differs from buying a single-family home in important ways. You’re not just buying the unit itself. You’re also buying into a homeowners association (HOA), shared amenities, and a collectively managed building or complex. That adds layers of due diligence that make contingencies especially valuable.
For example, a condo association might have underfunded reserves, pending special assessments, or restrictions that affect your ability to finance the purchase. Without contingencies in place, you could find yourself legally obligated to complete a purchase that no longer makes financial sense.
Contingencies give you time to uncover these issues, and an exit strategy if you find them.
What Are the Most Common Types of Contingencies in a Condo Transaction?
Financing Contingency
Also called a mortgage contingency. This clause gives you a set period, typically 21 to 30 business days, to secure financing for the purchase. If your loan falls through, the financing contingency allows you to cancel the contract without forfeiting your earnest money.
This is particularly relevant in condo transactions because lenders evaluate not just your financial profile, but also the condo association itself. Factors like the percentage of owner-occupied units, the association’s financial health, and pending litigation can all affect loan approval.
Inspection Contingency
A home inspection contingency gives you the right to have the property professionally inspected within a defined window, usually 5-7 business days after the offer is accepted. If the inspection reveals significant issues, you can negotiate repairs, request a price reduction, or back out of the deal entirely.
For condos, inspections typically cover the interior of the unit, including HVAC systems, plumbing, electrical, and appliances. Common areas and building structure are often the association’s responsibility, but that doesn’t mean you shouldn’t ask questions about their condition.
Condo Document Review Contingency
This one is unique to condo purchases and is among the most important. Michigan law entitles buyers to receive the condo association’s governing documents. This includes bylaws, rules and regulations, the master deed, and the most recent budget and meeting minutes. You then have a defined period, per the contract, to review them.
During this review, you’re looking for red flags such as:
- High delinquency rates among unit owners
- Inadequate reserve funds
- Pending or recent special assessments
- Restrictions on rentals, pets, or renovations
- Ongoing litigation involving the association
If you discover something that changes your decision, this contingency gives you a legal path to exit the contract.
Appraisal Contingency
If you’re financing your purchase, your lender will require an appraisal to confirm the property’s market value. An appraisal contingency protects you if the home appraises for less than the agreed purchase price. Without it, you’d be required to make up the difference in cash or risk losing your earnest money by walking away.
In a competitive Ann Arbor market, some buyers choose to waive this contingency to make their offer more attractive. That’s a decision best made with guidance from an experienced local Realtor who understands current market conditions.
Sale of Current Home Contingency
If you’re purchasing while simultaneously selling your current home, a home sale contingency allows you to back out if your existing property doesn’t sell within a specified timeframe. Sellers are generally less favorable to this type of contingency, especially in a hot market, so it’s important to discuss your options with your agent before including it.
Attorney Approval Contingency
The attorney review contingency gives you a set window of time, usually a few days after signing, to have a Real Estate Attorney review the contract. If your attorney spots something they don’t like, they can request changes or even cancel the deal. You’d walk away with your earnest money intact. It’s a smart layer of protection, especially for a big purchase. Not every buyer uses one, but it can give you real peace of mind. Your Realtor can help you decide if it’s the right move for your situation.
How Do Contingencies Protect the Buyer?
Contingencies are primarily designed with the buyer’s interests in mind. They create structured off-ramps that allow you to exit a transaction, without financial penalty, if something unexpected comes up. Whether that’s a lender declining your mortgage application, an inspector uncovering water damage, or the condo documents revealing a looming $15,000 special assessment, contingencies ensure you’re never trapped.
They also create negotiating leverage. If an inspection reveals needed repairs, for instance, you can use the inspection contingency to re-open discussions rather than simply accepting the property as-is.
How Do Contingencies Protect the Seller?
Sellers benefit from contingencies too, perhaps less obviously, but meaningfully. Clear contingency terms define exactly what conditions must be met and by when. This reduces ambiguity and the risk of a buyer backing out late in the process for reasons not outlined in the contract.
Sellers can also negotiate the terms of contingencies, including timeframes and what outcomes are acceptable, to minimize disruption to their sale timeline. A well-structured offer with defined contingencies is often more reliable than one with vague or open-ended conditions.
What Happens When a Contingency Isn’t Met?
So, what happens if a contingency isn’t met in time? Don’t worry, you’ve got options. You can ask for an extension, or you can walk away from the contract. If you choose to leave, you’ll usually get your full earnest money deposit back. Just be sure to follow the steps laid out in your contract.
But here’s the important part. If you try to back out for a reason your contingencies don’t cover, things get tricky. You could lose your earnest money. In some cases, you might even face legal trouble. That’s exactly why having a great Realtor in your corner matters so much. A knowledgeable Realtor makes sure your contingencies are written clearly and timed just right. It’s one more way we help you buy with confidence and peace of mind.
Start Your Ann Arbor Condo Search with Confidence
Understanding contingencies is one of the most important steps you can take before making an offer. They give you room to breathe, do your due diligence, and make a fully informed decision, without putting your earnest money or financial future at risk.
At The Bouma Group, Realtors, we’ve been the Ann Arbor condo experts for 41 years. We know the local market, the condo associations, and exactly how to structure an offer that protects your interests. Whether you’re buying your first condo or your fifth, we’re here to guide you through the entire process.
Ready to get started? Contact The Bouma Group today:
📞 734-761-3060
✉️ info@condohotline.com
🌐 condohotline.com
Unpacking the Real Cost of Condo Living: A Guide to Understanding Condo HOA Fees
A Condo Buyers Guide to HOA Fees
For potential condo buyers, the allure of low-maintenance luxury living often comes with a not-so-glamorous caveat—monthly condo association fees, otherwise known as HOA (Homeowners’ Association) fees. Beyond the catchy “lock-and-leave” lifestyle advertised, these fees can significantly impact your financial obligations and the value you receive from your investment. In this comprehensive guide, we’ll demystify the sometimes murky waters of HOA fees so you can make the most informed decisions about your future condo purchase.
The ABCs of Condo HOA Fees
Defining the Terms
Before you can truly grasp the implications of HOA fees, it’s essential to understand what they are. These fees are recurring payments made by condo or single-family home owners within a particular community or building. The fees cover shared expenses, from maintenance and repairs to community amenities and even insurance for common areas.
The Financial Breakdown
Condo fees can vary significantly based on various factors such as the location, age, and building amenities. The key is transparency—potential buyers should be provided with a detailed breakdown of these costs before closing day. Remember, not all HOA fees are created equal. Some may seem hefty at first glance, but if they include utilities and significant community perks, they could actually offer a better deal than seemingly lower fees that hide additional costs.
Understanding the Purpose
What exactly are you paying for with your HOA fees? Typically, these funds are allocated to address the following:
- Maintenance: Routine upkeep of the building’s exterior, common areas, and shared amenities is a non-negotiable component of HOA fees.
- Utilities: Heating, water, waste removal, and electricity for common areas may be covered, reducing individual expenses.
- Reserve Funds: For future repairs and major projects, the association should set aside a portion of fees to avoid special assessments.
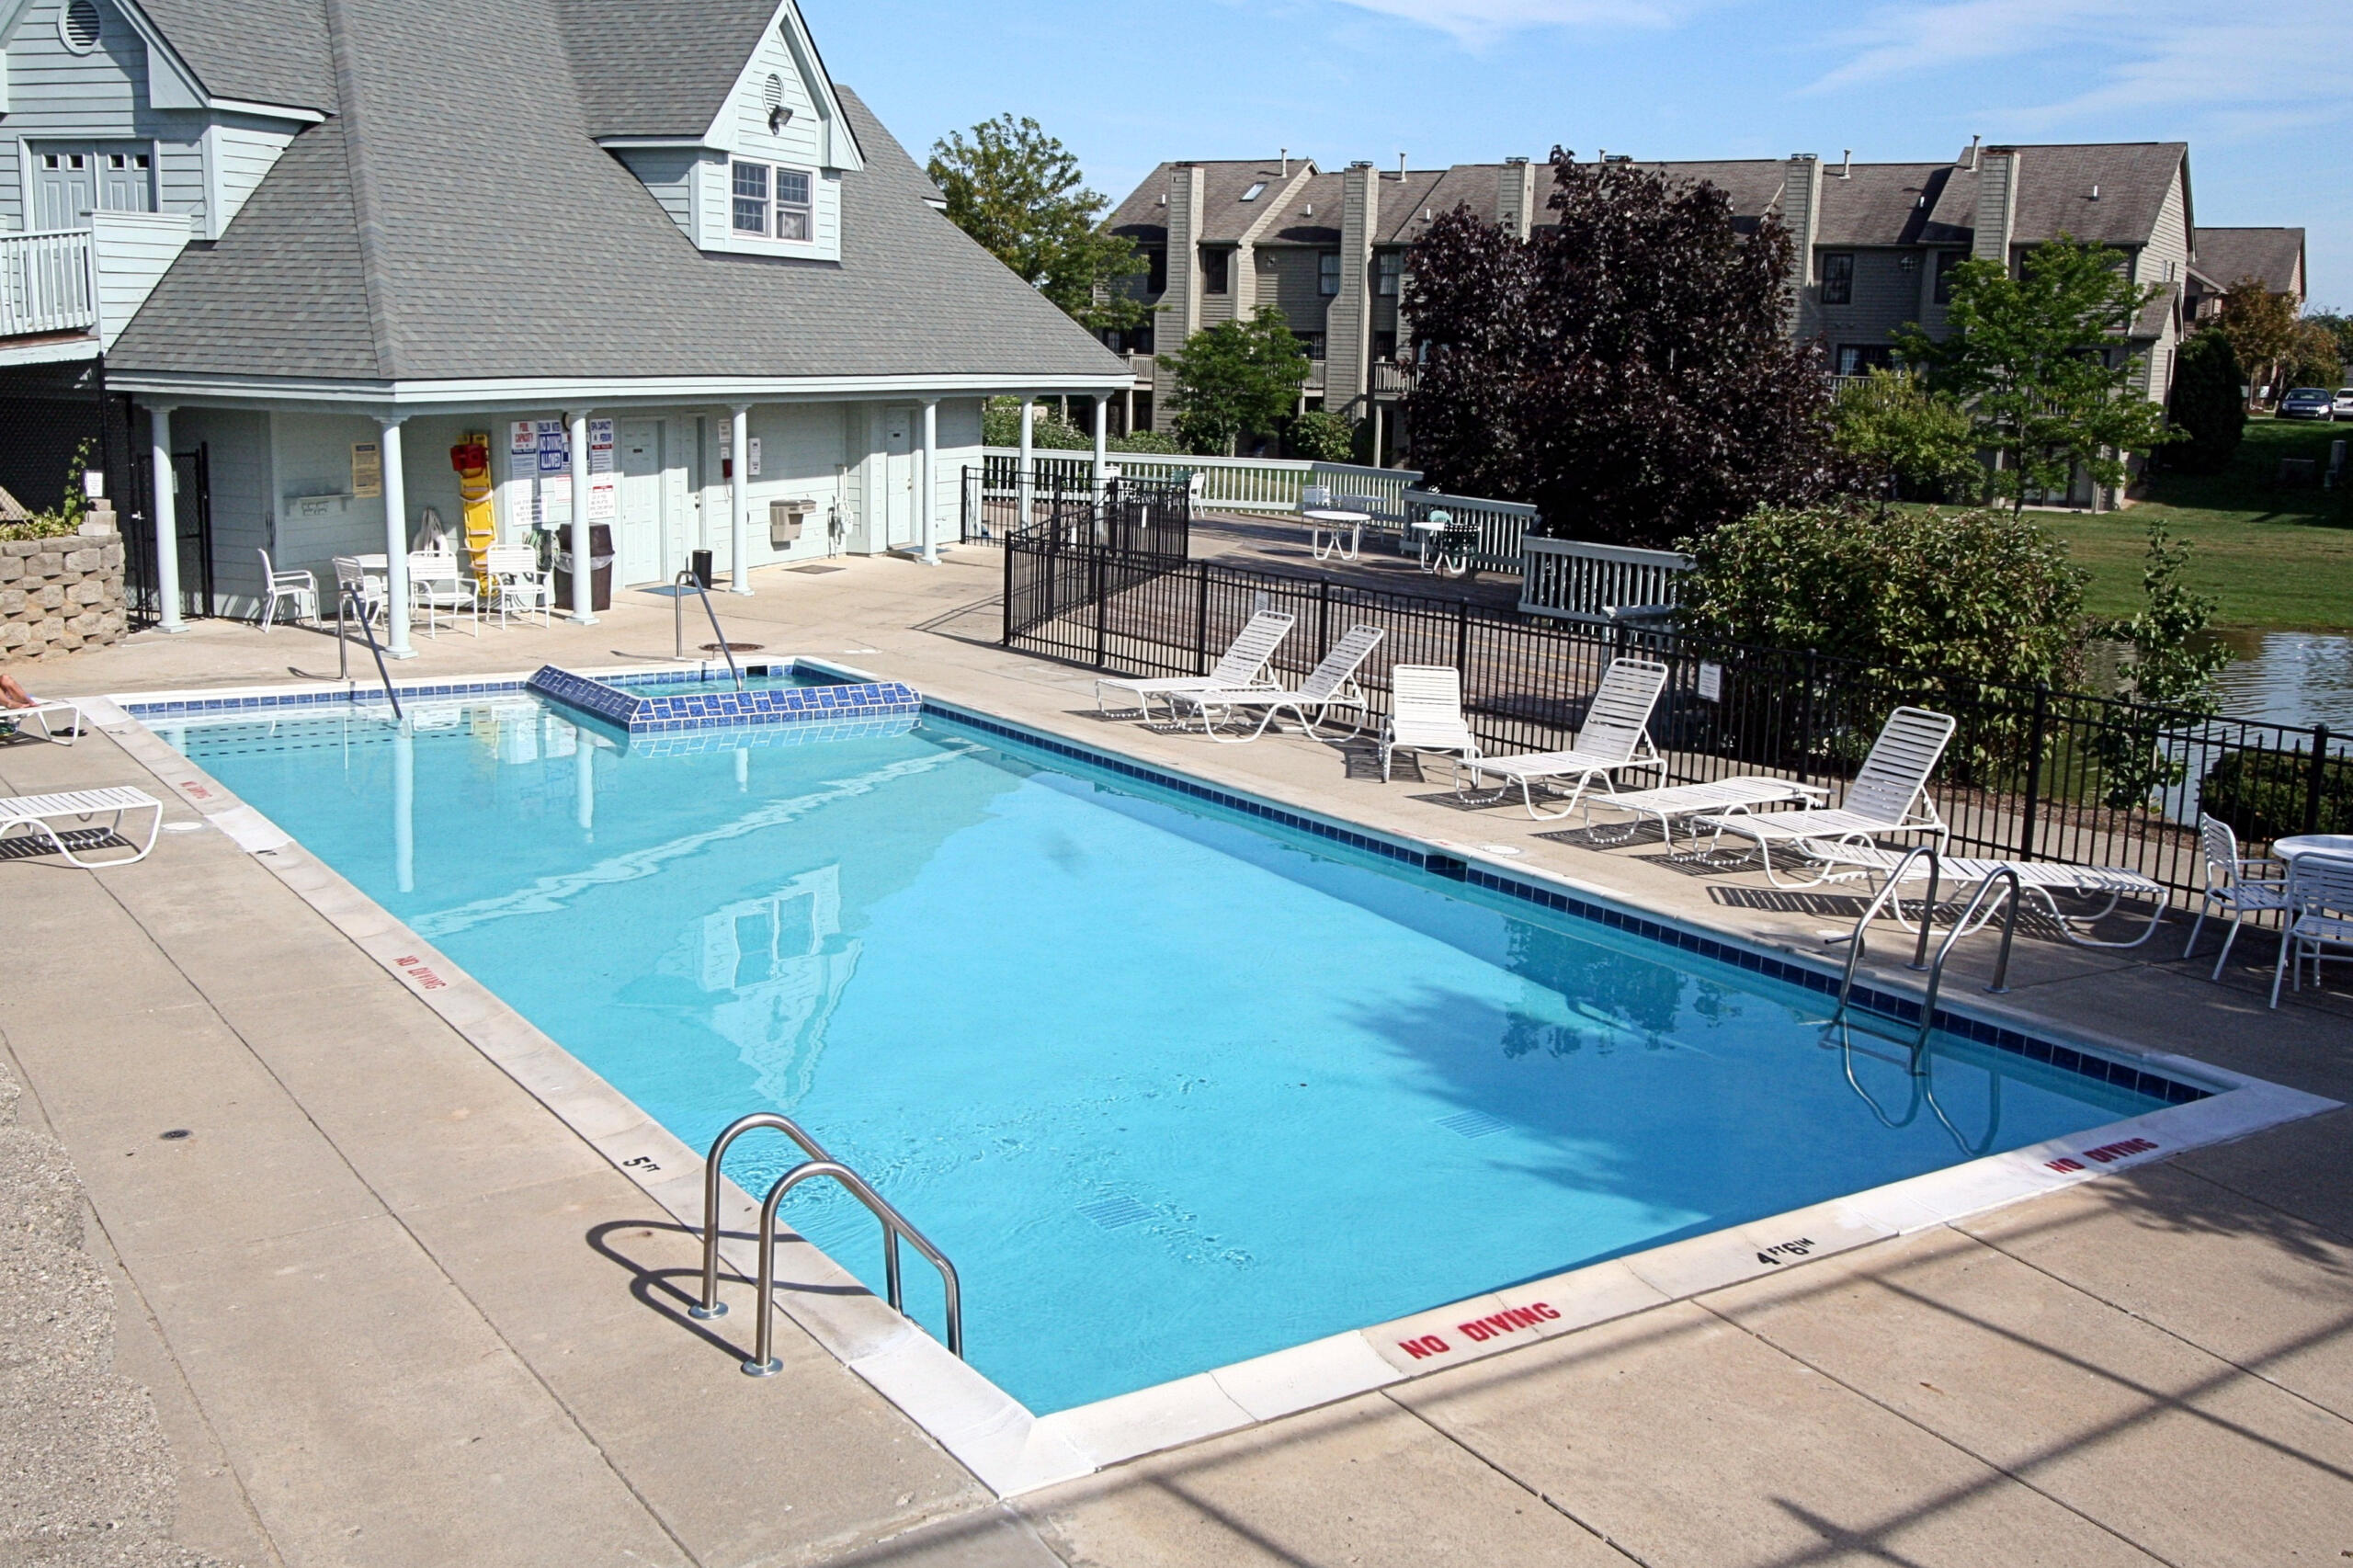
- Amenities: Pools, gyms, community rooms, and other facilities often require ongoing maintenance and insurance.
The Condo Association: Your Fee Guardians
The Role of the Association Board
The condo association board is a critical player in the management of your HOA fees. Elected by unit owners, the board establishes the annual budget, enforces community rules, and makes both minor and major decisions about the building’s operations. Engage with the board and attend meetings to ensure that your financial contributions are being used effectively and reflect your needs and desires as a member of the community.
Decoding the Association Documents
Before you even start calculating your budget with HOA fees in mind, it’s essential to review the association’s financial documents. The master deed and bylaws will detail how fees are determined, any limitations on increasing fees, and what rights and responsibilities the association has in spending these funds.
Special Assessments and Your Pocket
In some instances, HOA fees won’t be enough to cover significant unforeseen expenses, or the association may decide to undertake a large-scale improvement project. This is where special assessments come in, extra fees charged to unit owners to cover these costs. To protect your finances, ensure the association maintains a solid reserve fund and has a clear policy on when special assessments may be levied.
Additional Considerations for Prospective Condo Buyers
Planning for Future HOA Fee Hikes
HOA fees are not stagnant. They can—and often do—increase over time. It’s crucial to understand the underlying reasons for increases and budget for these changes. Factors that may lead to fee hikes include rising insurance costs, aging building infrastructure, or new amenities.
The Fine Print on Pet Policies and Parking
Some fees may not be explicitly labeled as HOA fees and can contribute significantly to your living expenses. Non-refundable pet deposits, monthly pet rent, or charges for dedicated parking spaces can add up quickly and should be factored into your housing budget.
The Social and Lifestyle Value of HOA Fees
While the financial aspects of these fees are critical, don’t overlook the social and lifestyle benefits they can offer. Access to well-maintained amenities and the community’s shared environment are significant perks. They can enhance your quality of life and often justify the associated costs.
In conclusion, condo HOA fees can be a source of contention or a ticket to a fulfilling housing experience. It all comes down to knowledge and participation. You can turn what might seem like a financial burden into a wise investment in your future home by understanding what HOA fees encompass, being well-informed about your association’s practices, and making choices that align with your financial and lifestyle goals. Take the time to dig deep and when the time comes to commit, do so with confidence and a complete understanding of what you’re getting into. Your dream condo may be waiting for you – HOA fees and all. So, carefully consider all aspects before making a decision. To learn more about the condo-buying process, contact us at 734-761-3060 or info@condohotline.com. Search for your dream condo here!
Are Higher Mortgage Rates Here To Stay?
Higher Mortgage Rates Are Affecting Purchase Power
Mortgage rates have been back on the rise recently and that’s getting a lot of attention from the press. If you’ve been following the headlines, you may have even seen rates recently reached their highest level in over two decades (see graph below):

That can feel like a little bit of a gut punch if you’re thinking about making a move. If you’re wondering whether or not you should delay your plans, here’s what you really need to know.
How Higher Mortgage Rates Impact You
There’s no denying rates are higher right now than they were in recent years. And, when rates are up, that affects overall home affordability. It works like this. The higher the rate, the more expensive it is to borrow money when you buy a home. That’s because, as rates trend up, your monthly mortgage payment for your future home loan also increases.
Urban Institute explains how this is impacting buyers and sellers right now:
“When mortgage rates go up, monthly housing payments on new purchases also increase. For potential buyers, increased monthly payments can reduce the share of available affordable homes . . . Additionally, higher interest rates mean fewer homes on the market, as existing homeowners have an incentive to hold on to their home to keep their low interest rate.”
Basically, some people are deciding to put their plans on hold because of where mortgage rates are right now. But what you want to know is: is that a good strategy?
Where Will Mortgage Rates Go From Here?
If you’re eager for rates to drop, you’re not alone. A lot of people are waiting for that to happen. But here’s the thing. No one knows when it will. Even the experts can’t say with certainty what’s going to happen next.
Forecasts project rates will fall in the months ahead, but what the latest data says is that rates have been climbing lately. This disconnect shows just how tricky mortgage rates are to project.
The best advice for your move is this: don’t try to control what you can’t control. This includes trying to time the market or guess what the future holds for mortgage rates. As CBS News states:
“If you’re in the market for a new home, experts typically recommend focusing your search on the right home purchase — not the interest rate environment.”
Instead, work on building a team of skilled professionals, including a trusted lender and real estate agent, who can explain what’s happening in the market and what it means for you. If you need to move because you’re changing jobs, want to be closer to family, or are in the middle of another big life change, the right team can help you achieve your goal, even now.
Bottom Line
The best advice for your move is: don’t try to control what you can’t control – especially mortgage rates. Even the experts can’t say for certain where they’ll go from here. Instead, focus on building a team of trusted professionals who can keep you informed. When you’re ready to get the process started, let’s connect today at 734-761-3060 or info@condohotline.com.