What is Earnest Money? A Condo Buyer’s Guide
What is Earnest Money and Why Do I Need It?
You have finally found the perfect property after weeks of searching. The location is ideal, the amenities match your lifestyle, and you are ready to make an offer. As you sit down to draft the purchase agreement, your real estate agent mentions you need to provide an earnest money deposit. If this is your first time navigating the home-buying process, you might feel slightly overwhelmed.
Purchasing a condo involves navigating a maze of new terms and financial requirements. Earnest money is one of the first and most critical components of your real estate transaction. It shows the seller you are a serious buyer and helps secure your offer.
In this insightful guide, we will break down exactly what earnest money is, why you need it, and how to protect your funds. You will learn how much you should expect to pay, under what conditions you can get your money back, and how these funds apply to your final closing costs.
What Exactly is Earnest Money?
At its core, earnest money is a “good faith” deposit you make when signing a purchase agreement. When you submit an offer on a condo, this deposit proves to the seller that you are genuinely interested in buying the property.
Think of it as a security deposit for purchasing a home. When a seller accepts your offer, they must take their property off the market. This creates a period of risk for the seller. If you suddenly decide to walk away from the deal simply because you changed your mind, the seller loses valuable time and potential other buyers. Your earnest money provides them with financial reassurance.
Once you and the seller sign the contract, you do not hand this money directly to the seller. Instead, you deposit the funds into a secure escrow account managed by a neutral third party, such as a title company or real estate brokerage. The money stays in this account until the sale finalizes.
Why Do I Need Earnest Money for a Condo Purchase?
If you want to secure your dream condo in a competitive market, an earnest money deposit is practically mandatory. While the law rarely requires it, sellers will almost never accept an offer without one.
Here are the primary reasons you need to provide an earnest money deposit:
It Makes Your Offer Competitive
A strong earnest money deposit helps your offer stand out. If a seller receives multiple offers with similar purchase prices, they will look at the terms. A buyer offering a larger good faith deposit appears more financially stable and committed to the purchase.
It Protects the Seller
As mentioned, sellers take a significant risk when they accept an offer. They halt their marketing efforts and stop showing the condo to other potential buyers. If the deal falls through without a valid contractual reason, the seller keeps the earnest money as compensation for their lost time and effort.
It Keeps the Transaction Moving
Putting your own cash on the line creates a strong incentive to complete your financing applications, schedule your inspections, and follow through on the purchase timeline. It ensures a seamless progression from the accepted offer to the closing table.
How Much Earnest Money is Typical?
The amount of earnest money you need to put down varies depending on the local real estate market, the condition of the property, and the overall purchase price.
Generally, you can expect to pay between 1% and 3% of the total purchase price. For example, if you are purchasing a $400,000 condo, your deposit would typically range from $4,000 to $12,000.
However, in highly competitive markets where multiple buyers are bidding on the same properties, buyers often increase their earnest money to 5% or even 10% to make their offer more attractive. A higher deposit signals strong financial health and firm intent. Your Realtor can provide expert market insights to help you determine the exact amount that makes sense for your specific situation.
Is My Earnest Money Deposit Refundable?
One of the biggest concerns buyers have is whether they can lose their deposit. Fortunately, standard real estate contracts include built-in protections called contingencies. These contingencies outline specific conditions that must be met for the transaction to proceed. If a condition fails, you can back out of the deal and receive a full refund of your earnest money.
Here are the most common contingencies that protect your deposit:
The Home Inspection Contingency
Even if a condo looks perfect during a virtual tour or an in-person visit, hidden issues might exist. The inspection contingency gives you a specific window of time to hire a professional to evaluate the property. If the inspector finds significant structural issues, plumbing problems, or electrical faults, you can ask the seller to make repairs. If the seller refuses, you can cancel the contract and get your deposit back.
The Financing Contingency
Unless you are paying in cash, you will need to secure a mortgage. The financing contingency protects you if your lender ultimately denies your loan application. Even with a pre-approval letter, your final financing depends on various factors, including a final review of your credit and income. If you cannot secure financing within the agreed-upon timeframe, your earnest money remains safe.
The Appraisal Contingency
Lenders require an appraisal to ensure the condo is worth the amount you agreed to pay. If you offer $350,000 but the appraiser determines the market value is only $320,000, the lender will not finance the full amount. A comparative market analysis early in the process helps predict this, but if a low appraisal happens, you can renegotiate the price or walk away with your deposit intact.
The Condo Association Document Review
When buying a condo, you are also buying into a community governed by a Homeowners Association (HOA). You typically have a contingency period to review the association’s bylaws, financial health, and community rules. If you discover the association has massive debt, pending lawsuits, or restrictive rules that you cannot live with, you can withdraw your offer and retain your earnest money.
What Happens to the Earnest Money at Closing?
Your earnest money does not just disappear, and it is not an extra fee paid on top of your purchase price. When you reach the closing table, the funds held in the escrow account are applied directly toward your final financial obligations.
Usually, the title company applies the earnest money to your down payment or your closing costs. For instance, if you provided a $5,000 earnest money deposit and your total down payment is $40,000, you will only need to bring $35,000 to closing. It acts as an early, accessible installment toward your new home.
Common Earnest Money Mistakes to Avoid
Navigating the real estate market requires sharp attention to detail. Avoid these common pitfalls to keep your deposit safe:
- Waiving Contingencies Blindly: In a hot market, you might feel tempted to waive your inspection or financing contingencies to win a bidding war. Do this only under expert Realtor guidance, as waiving these protections means you could lose your deposit if something goes wrong.
- Missing Contract Deadlines: Purchase agreements include strict timelines for inspections, appraisals, and financing approvals. If you miss a deadline and try to back out later, the seller has the right to keep your money.
- Giving Money Directly to the Seller: Never hand a personal check or cash directly to the seller. Always ensure your funds go to a verified escrow account managed by a reputable third party.
- Making Emotional Decisions: Always rely on comparative market data rather than emotion when deciding how much earnest money to offer.
Frequently Asked Questions
What happens if the seller backs out of the contract?
If the seller decides to cancel the sale for a reason not covered in the contract, you will receive a full refund of your earnest money. In some cases, you may also have legal grounds to sue the seller for breach of contract.
Can I use a credit card for earnest money?
Typically, no. Title companies and brokerages usually require a certified check, a personal check, or a wire transfer to accept earnest money deposits.
How long does it take to get earnest money back if a deal falls through?
If you back out for a valid reason covered by a contingency, both you and the seller must sign a release form. Once signed, the escrow holder usually returns the funds within a few business days.
Is an earnest money deposit the same as a down payment?
No. Earnest money is an upfront deposit to show good faith when making an offer. A down payment is the total cash amount you pay toward the property’s purchase price at closing. However, your earnest money is usually applied toward your down payment when the sale finalizes.
Secure Your Ideal Condo with Confidence
Understanding how earnest money works is a crucial step in your condo purchasing journey. It empowers you to make strong, competitive offers while ensuring your hard-earned savings remain protected by the right contract contingencies.
You do not have to navigate the complex world of real estate alone. Expert Realtor guidance makes all the difference when drafting purchase agreements, negotiating terms, and exploring accessible financing options.
If you are looking to explore vibrant condos in the Ann Arbor area and want a seamless buying experience, our team is ready to help you every step of the way. Contact us at The Bouma Group, Realtors today at 734-761-3060 or info@condohotline.com to start your journey toward your perfect place.
Mortgage Rates Just Saw Their Biggest Drop in a Year

You’ve been waiting for what feels like forever for mortgage rates to finally budge. And last week, they did – in a big way.
On Friday, September 5th, the average 30-year fixed mortgage rate fell to the lowest level since October 2024. It was the biggest one-day decline in over a year.
What Sparked the Drop?
According to Mortgage News Daily, this was a reaction to the August jobs report, which came out weaker-than-expected for a second month in a row. That sent signals across the financial markets, and then mortgage rates came down as a result.
Basically, we’re seeing signs the economy may be slowing down, and as certainty grows in the direction the economy is going, the markets are reacting to what is likely ahead. That historically brings mortgage rates down.
Why Buyers Should Pay Attention Now
But this isn’t just about one day of headlines or one report. It’s about what the drop means for you.
This recent change saves you money when you buy a home or condo. The chart below shows you an example of what a monthly mortgage payment (principal and interest) would be at 7% (where mortgage rates were in May) versus where rates roughly are now:
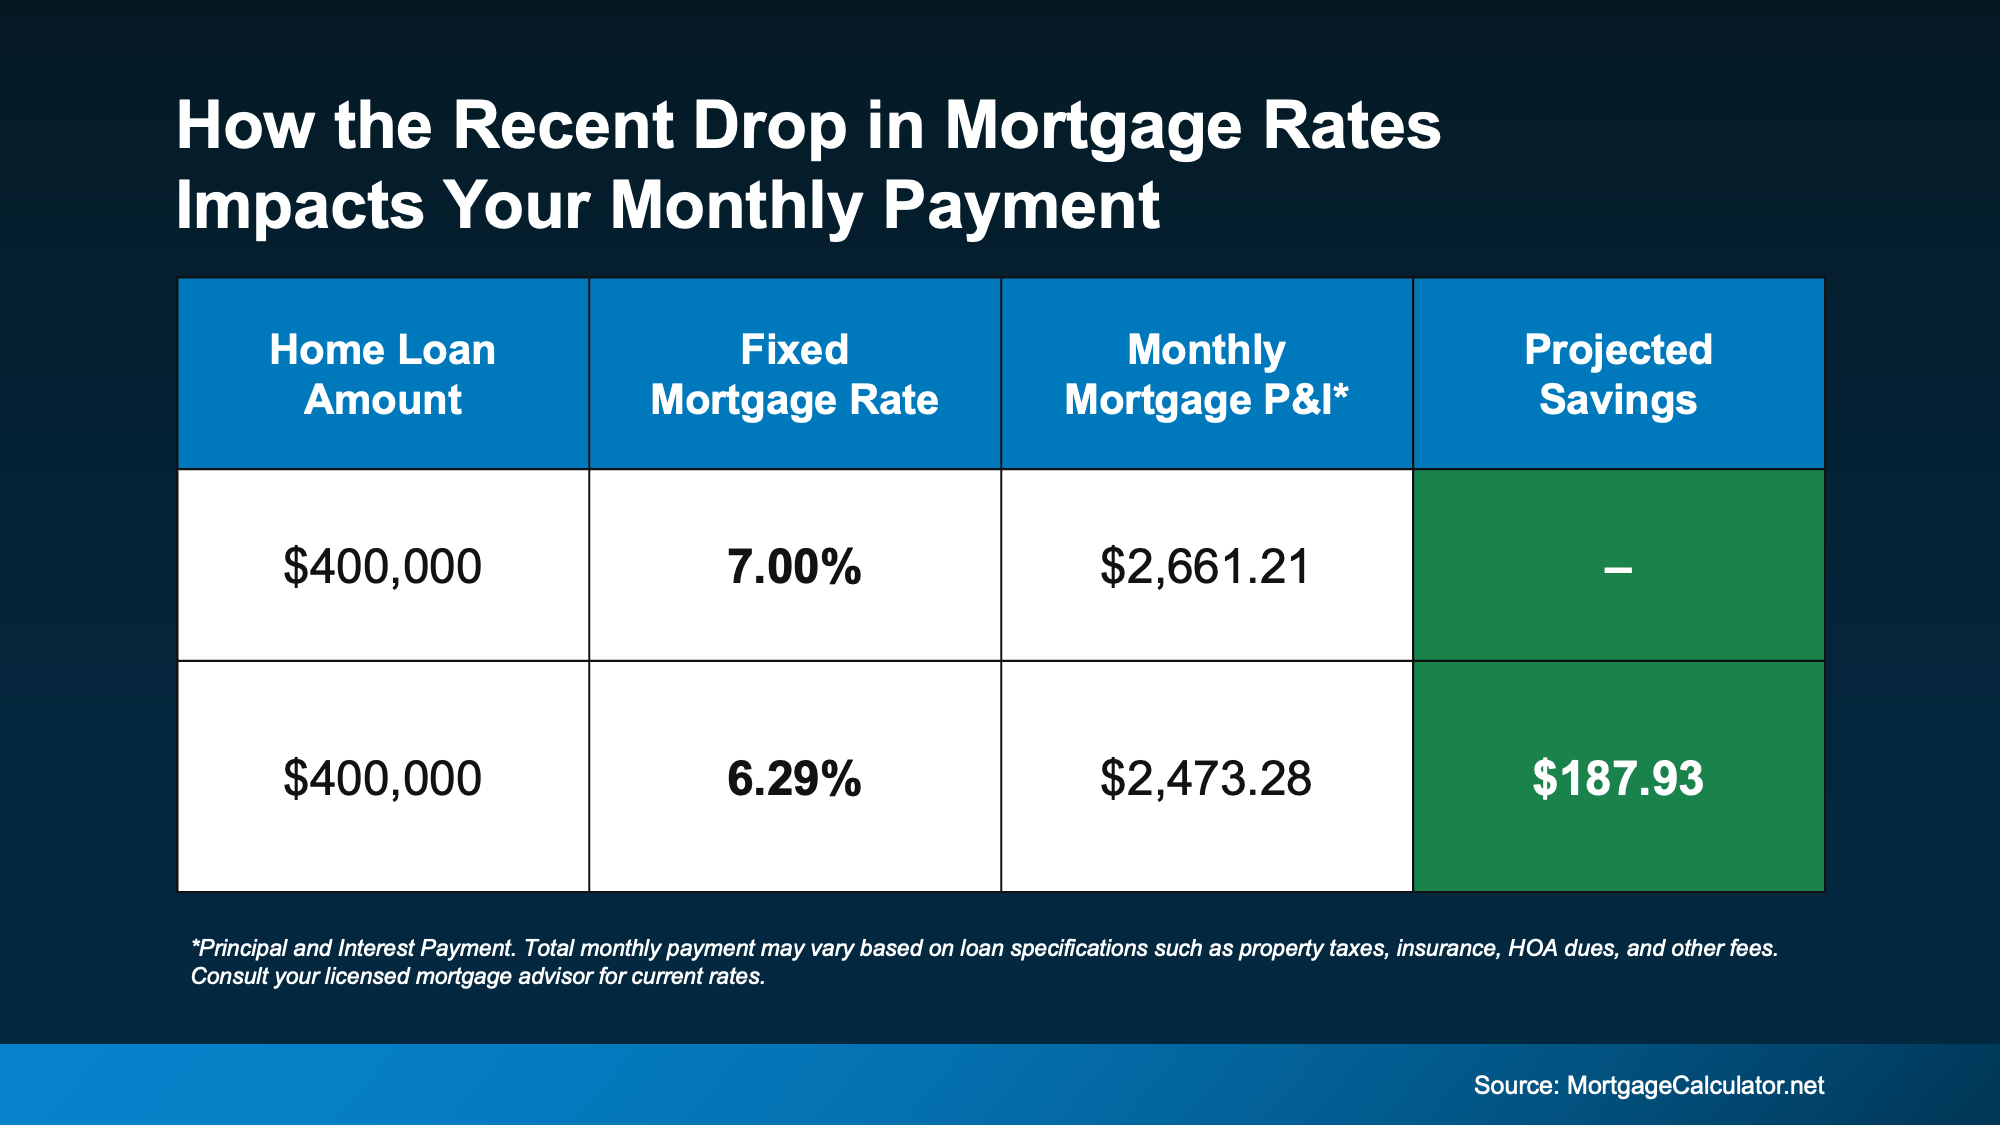
Compared to just 4 months ago, your future monthly payment would be almost $200 less per month. That’s close to $2,400 a year in savings.
How Long Will It Last?
That really depends on where the economy and inflation go from here. Rates could drop lower, or they could inch up slightly.
So, make sure you’re connected with a good agent and trusted lender. We keep a close eye on inflation indicators, job market updates, and reactions to upcoming Fed policy to gauge where mortgage rates may go from here.
But for now, focus on this. While no one can say for sure where rates are headed, the fact that rates broke out of their months-long rut is a good thing. If you’ve been feeling stuck, this could make the start of a new chapter. As Diana Olick, Senior Real Estate and Climate Correspondent at CNBC, says:
“Rates are finally breaking out of the high 6% range, where they’ve been stuck for months.”
And that’s gives you more reason to hope than you’ve had in quite some time.
Bottom Line
This is the shift you’ve been waiting for.
Mortgage rates just saw their biggest decline in over a year. And if rates stay near this level, it could make a home or condo you couldn’t afford just a few months ago feel possible again.
What would today’s rates save you on your future monthly payment? Let’s connect so you can find out. Contact us today at The Bouma Group, Realtors at 734-761-3060 or info@condohotline.com and we’ll make a plan together. See what condo communities Ann Arbor has to offer and start dreaming about your new home!
Maximize Your Ann Arbor Condo Search with Condo Hotline
When it comes to finding the perfect condo in Ann Arbor, diligent research can make all the difference. However, navigating the condo market can be overwhelming, with so many communities, amenities, and listings to explore. That’s where Condo Hotline comes in. It offers a user-friendly platform that empowers Ann Arbor condo buyers with the tools they need to find their dream home, all in one convenient place.
The All-in-One Solution for Ann Arbor Condo Buyers
Condo Hotline is your one-stop shop for everything you need to know about Ann Arbor condos. Whether you’re seeking detailed information or inspiration for your search, Condo Hotline provides access to essential resources for informed decision-making. Here’s what you’ll find on the platform:
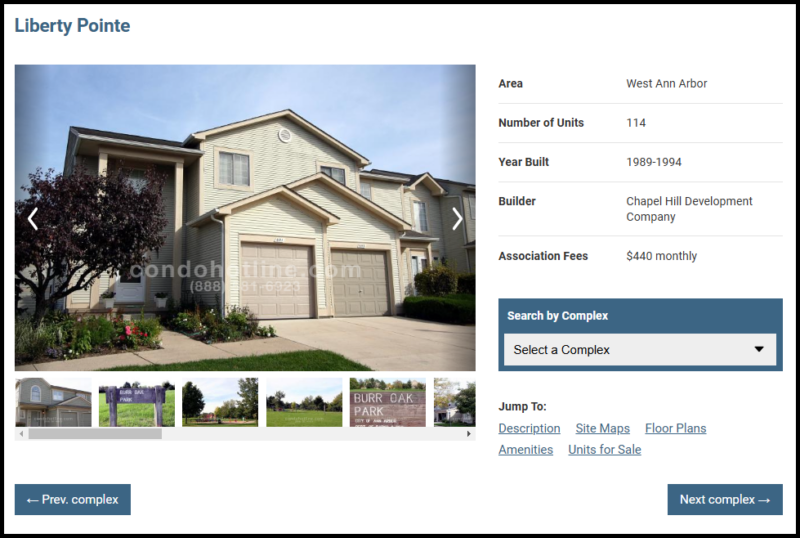
- Comprehensive Community Information – Learn about Ann Arbor condo communities, their amenities, and what makes each one unique.
- Community Photos and Descriptions – Get a feel for each condo community with in-depth descriptions and photos that bring the neighborhoods to life.
- Real-Time Listings – View units currently for sale in your desired communities and find the options that best suit your preferences.
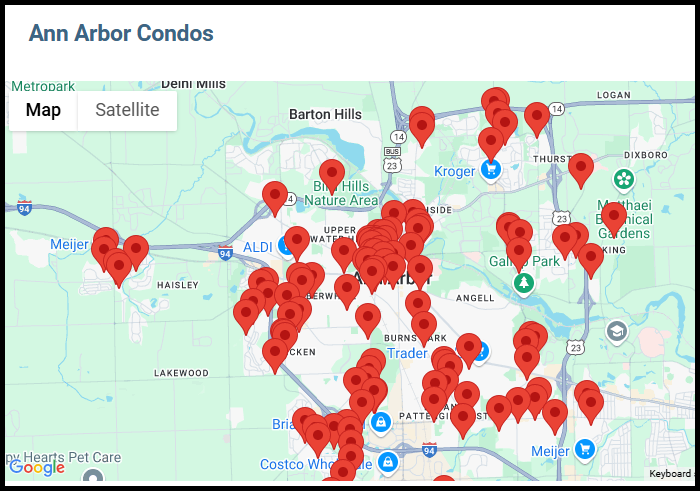
- Interactive Maps and Site Maps – Whether you’re navigating downtown or looking for the perfect suburban location, Condo Hotline’s maps help you visualize each community and its surroundings.
- Floor Plans and Bylaws – Get access to important details like floor layouts and community bylaws to ensure everything meets your expectations.
By consolidating all of this information, Condo Hotline eliminates the hassle of jumping between platforms. It’s all here, ready for you to explore.
Empowering Buyers with Smart Tools
Condo Hotline isn’t just about providing information—it’s designed to give buyers an edge in today’s competitive Ann Arbor condo market. Our platform offers powerful tools tailored to your condo-buying needs, including:
- Instant Listing Alerts: Stay ahead of the game by signing up for notifications when new condos hit the market in your preferred communities.
- Downtown Ann Arbor Market Reports: Gain insight into current market trends, pricing, and the state of the local real estate market.
- Interactive Maps for Your Search: Search communities across Ann Arbor with an easy-to-use map feature that puts you in control.
These tools empower buyers to act quickly and confidently, making the search for your dream condo seamless and efficient.
Expert Insights at Your Fingertips
Condo Hotline goes beyond listings by offering an extensive collection of resources to help you make informed decisions. Our blog features over 100 articles covering topics like:
- Buying and selling strategies tailored to the Ann Arbor condo market.
- Financing and mortgage advice for buyers.
- Guides on new condo developments in Ann Arbor.
- Insights into why Ann Arbor is one of the best places to live.
Whether you’re new to the market or a seasoned buyer, our blog offers in-depth knowledge to enhance your condo-buying experience. It’s like having a trusted advisor right at your fingertips.
Why Ann Arbor Condo Buyers Love Condo Hotline
By combining an easy-to-navigate platform, expert insights, and useful tools, Condo Hotline provides everything you need to streamline your search. The platform doesn’t just save time and energy—it ensures better outcomes by enabling smarter decision-making.
Imagine finding your perfect condo while feeling confident about every step of the process. That’s what Condo Hotline offers.
Start Your Journey with Condo Hotline
Finding the right condo in Ann Arbor doesn’t have to be a daunting task. With Condo Hotline, you’ll have access to all the tools, insights, and details you need to make your search stress-free. For any Real Estate questions, contact The Bouma Group today at 734-761-3060 or info@bouma.com.
Visit Condo Hotline today to explore Ann Arbor condos, set up listing alerts, and learn more about the market. Your dream condo could be just a few clicks away!
Stop Wondering What Your Budget Is & Get Pre-Approved!

In many markets across the country, the number of buyers searching for their dream home or condo outnumbers the number for sale. This has led to a competitive marketplace where buyers often need to stand out. One way to show that you are serious about purchasing is to get pre-approved for a mortgage before starting your search.
Even if you are not in an incredibly competitive market, understanding your budget will give you the confidence of knowing whether or not your dream condo is within your reach.
Freddie Mac lays out the advantages of pre-approval in the ‘My Home’ section of their website:
“It’s highly recommended that you work with your lender to get pre-approved before you begin house hunting. Pre-approval will tell you how much home you can afford and can help you move faster, and with greater confidence, in competitive markets.”
One of the many advantages of working with a local real estate professional is that many have relationships with lenders who will be able to help you through this process. Once you have selected a lender, you will need to fill out their loan application and provide them with important information regarding “your credit, debt, work history, down payment and residential history.”
Freddie Mac describes the ‘4 Cs’ that help determine the amount you will be qualified to borrow:
- Capacity: Your current and future ability to make your payments
- Capital or cash reserves: The money, savings, and investments you have that can be sold quickly for cash
- Collateral: The home, or type of home, that you would like to purchase
- Credit: Your history of paying bills and other debts on time
Getting pre-approved is one of many steps that will show sellers that you are serious about buying, and it often helps speed up the process once your offer has been accepted.
Bottom Line
Many potential buyers overestimate the down payment and credit scores necessary to qualify for a mortgage. If you are ready and willing to buy, you may be pleasantly surprised at your ability to do so today. Contact us at The Bouma Group, Realtors and we can give you a list of local mortgage lenders that have wowed our clients! 734-761-3060 or info@condohotline.com Check out Ann Arbor Condos here!
