Mortgage 101: What To Know Before You Apply
Everybody loves talking about mortgages. They’re fun, easy to understand, and a great icebreaker, right?….Wrong. Thanks to their lengthy process, technical jargon, and confusing options, mortgages have a bit of an intimidating reputation—but it doesn’t have to be that way!
If you’re in the process of buying a new condo and dreading the mortgage application process, here’s what you need to know to keep things running smoothly.
Know How Much You Can Spend
If you’re feeling antsy about getting started and want a general idea of how much loan you might qualify for, consider the 28/36 rule, or the Debt-to-Income ratio—AKA what most lenders use to help calculate your mortgage.
Essentially, the 28/36 rule means that your monthly mortgage payment shouldn’t be more than 28% of your gross income. Additionally, your outstanding debts—like mortgage, car loans, student loans—shouldn’t account for more than 36% of your gross income.
Get Your Finances in Order
Not seeing the numbers you were hoping for after calculating your Debt-to-Income ratio? Then, hopefully, you’ve given yourself a little time to shift things in your favor. Paying off loans, improving your credit score, avoiding big purchases—these will all help you change those numbers.
Of course, completing those tasks is a little harder to do in practice than in theory, so you may have to take a look at your budget and see where you can cut out some extras—at least temporarily!
What You’ll Need to Apply
In the weeks before you plan on applying for a mortgage, you should start collecting all of the documents you need. Since a lender will be telling you exactly how much money they’re willing to loan, they’ll need a comprehensive understanding of your finances beforehand. Start gathering things like:
- W2s/tax returns
- Photo ID
- Your two most recent pay stubs
- Current and prior addresses
- Asset information (retirement funds, 401(k), stocks and bonds, other investments)
- Gift letters
Depending on the lender you choose, you may need additional documents, so consider calling in to double-check beforehand.
Find the Right Mortgage
Once it’s time to start thinking more concretely about applying for a mortgage, you have several options to consider. While all the mortgage options out there could easily fill a whole blog post on their own, here’s a quick rundown to give you a general idea:
- Conventional/Fixed-rate: The interest rate of a fixed-rate loan won’t change over time, making it a popular choice for its predictability. Conventional loans typically require a 20% down payment or mortgage insurance for smaller down payments.
- Adjustable-rate: The interest rate of adjustable-rate mortgage will fluctuate over time, sometimes lower than fixed-rate, sometimes higher. There is a cap in place so the rate doesn’t get too out of control, but ARMs are typically more popular with those who plan to refinance.
- FHA: If you are struggling to come up with a down payment, you may have options with an FHA mortgage. Provided by the Federal Housing Administration, these loans come with a low down payment requirement and built-in mortgage insurance.
- USDA: Live in a rural area? Then check out your USDA eligibility! A surprising amount of areas qualify for USDA loans, even if you aren’t living in the countryside. Plus, USDA loans don’t require a down payment and offer lower insurance premiums.
These aren’t the only options you’ll have, just the most common. If none of these sound right or you aren’t sure which to choose, just ask your lender!
Choose the Right Lender
When it comes time to decide who to work with, you’ll have to do your research. Each lender is different, meaning they’ll likely offer you different rates, charges, and loan options.
Luckily, we’ve been working in real estate around the area for years, so we know exactly which lenders are right for which buyers. If you need a few suggestions before you kick off your search, just let us know!
Still Have Questions?
That’s okay—we get it. Applying for mortgage is confusing and challenging, especially if it’s your first time. If you have any questions about the process, we’re here to help, give us a call at The Bouma Group, Realtors at 734-761-3060 or info@condohotline.com.
Ready to start looking at a few homes in your price range? We can help with that, too! Check out our specialized search tool to narrow down your options, and give us a call to start seeing a few in person! Start your Search here!
Stop Wondering What Your Budget Is & Get Pre-Approved!

In many markets across the country, the number of buyers searching for their dream home or condo outnumbers the number for sale. This has led to a competitive marketplace where buyers often need to stand out. One way to show that you are serious about purchasing is to get pre-approved for a mortgage before starting your search.
Even if you are not in an incredibly competitive market, understanding your budget will give you the confidence of knowing whether or not your dream condo is within your reach.
Freddie Mac lays out the advantages of pre-approval in the ‘My Home’ section of their website:
“It’s highly recommended that you work with your lender to get pre-approved before you begin house hunting. Pre-approval will tell you how much home you can afford and can help you move faster, and with greater confidence, in competitive markets.”
One of the many advantages of working with a local real estate professional is that many have relationships with lenders who will be able to help you through this process. Once you have selected a lender, you will need to fill out their loan application and provide them with important information regarding “your credit, debt, work history, down payment and residential history.”
Freddie Mac describes the ‘4 Cs’ that help determine the amount you will be qualified to borrow:
- Capacity: Your current and future ability to make your payments
- Capital or cash reserves: The money, savings, and investments you have that can be sold quickly for cash
- Collateral: The home, or type of home, that you would like to purchase
- Credit: Your history of paying bills and other debts on time
Getting pre-approved is one of many steps that will show sellers that you are serious about buying, and it often helps speed up the process once your offer has been accepted.
Bottom Line
Many potential buyers overestimate the down payment and credit scores necessary to qualify for a mortgage. If you are ready and willing to buy, you may be pleasantly surprised at your ability to do so today. Contact us at The Bouma Group, Realtors and we can give you a list of local mortgage lenders that have wowed our clients! 734-761-3060 or info@condohotline.com Check out Ann Arbor Condos here!
2 Myths Holding Back Condo Buyers
Freddie Mac recently released a report entitled, “Perceptions of Down Payment Consumer Research.” Their research revealed that,
“For many prospective homebuyers, saving for a down payment is the largest barrier to achieving the goal of homeownership. Part of the challenge for those planning to purchase a home is their perception of how much they will need to save for the down payment…
…Based on our recent survey of individuals planning to purchase a home in the next three years, nearly a third think they need to put more than 20% down.”
Myth #1: “I Need a 20% Down Payment”
Buyers often overestimate the funds needed to qualify for a home loan. According to the same report:
22% of renters and 31% of homeowners believe lenders require 20% or more of a sale price as a down payment for a typical mortgage today. And,
“If a 20% down payment was required, 70% of those who were planning to buy a home in the next three years said it would delay them from purchasing and nearly 30% indicated they would never be able to afford a home.”
While many believe at least 20% down is necessary to buy the home or condo of their dreams, they do not realize programs are available which permit as little as 3%. Many renters may actually be able to enter the housing market sooner than they ever imagined!
Myth #2: “I Need a 780 FICO® Score or Higher to Buy”
Many either don’t know or are misinformed concerning the FICO® score necessary to qualify, believing a ‘good’ credit score is 780 or higher.
To debunk this myth, let’s take a look at Ellie Mae’s latest Origination Insight Report, which focuses on recently closed (approved) loans. As indicated in the chart above, 52.4% of approved mortgages had a credit score of 600-749.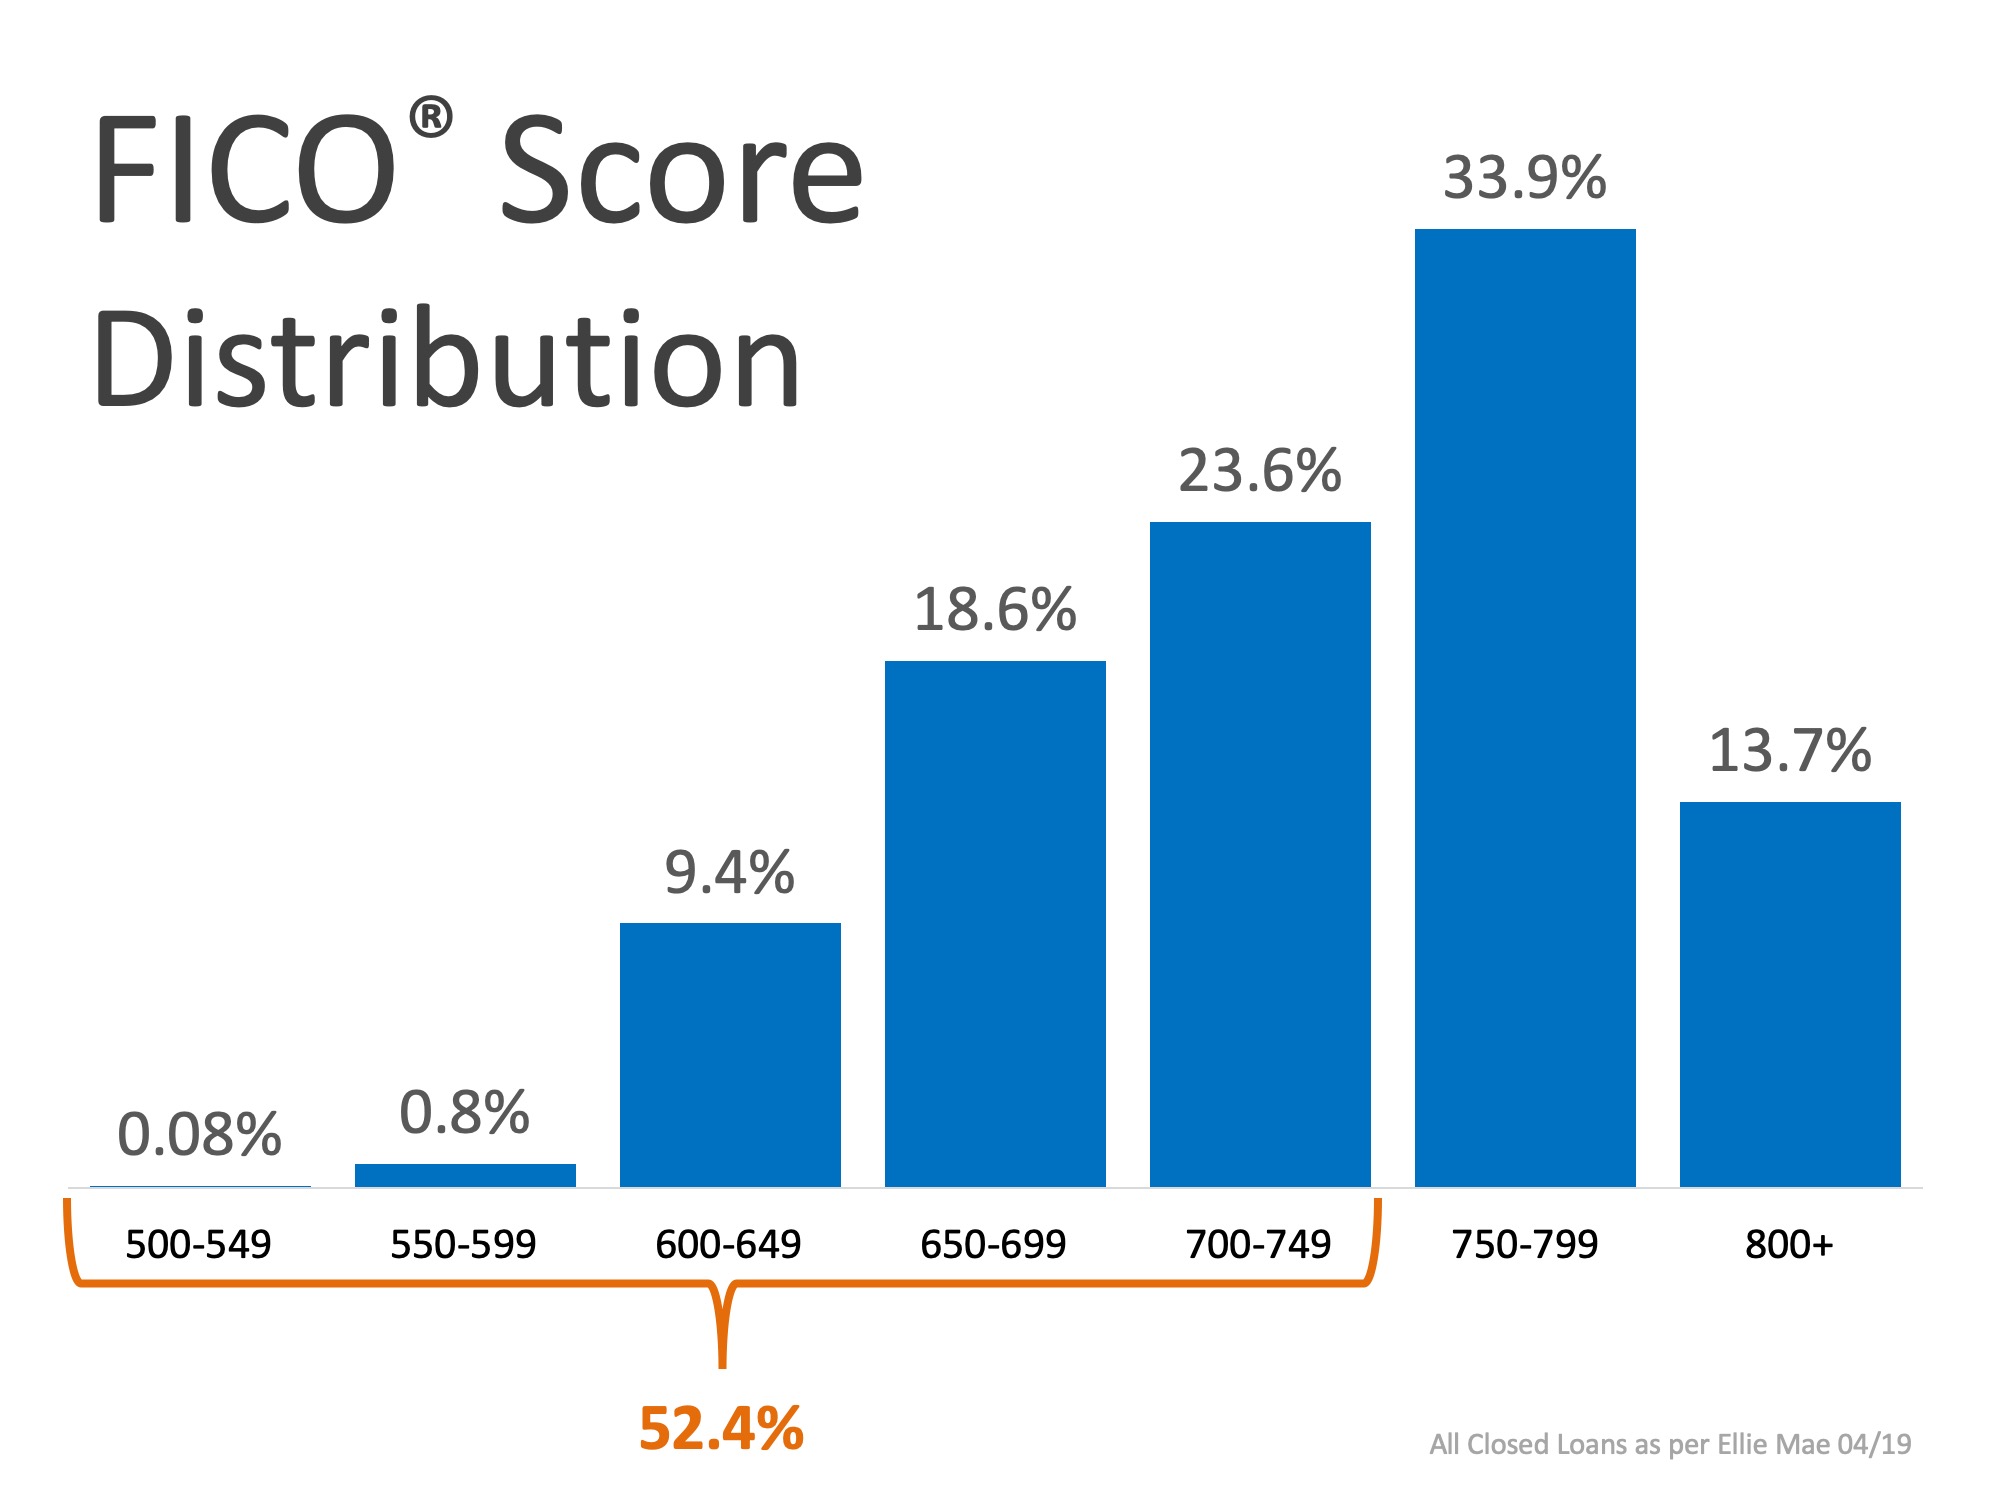
Bottom Line
Whether buying your first condo or moving up to your dream home, knowing your options will make the mortgage process easier. Your dream may already be within your reach! Contact us, the Ann Arbor Condo specialists to begin your new condo search at 734-761-3060 or info@condohotline.com.