
Understanding Today’s Mortgage Rates: Is 3% Coming Back?
Are 3% Mortgage Rates Coming Back?
Many buyers are holding off on their plans these days, hoping that mortgage rates will drop – perhaps even back to the historic low of 3% from a few years ago. But here’s the thing: those rates were never meant to last. They were a short-term response to a very specific moment in time. And as the market finds its footing again, it’s time to reset expectations.
Back in 2020 and 2021, 3% mortgage rates gave buyers a serious boost: more affordability, more buying power, and more opportunity. But those rates were a result of emergency economic policies during the height of a global pandemic. Now that the economy is in a different place, we’re seeing mortgage rates in the high 6% to low 7% range.
And while experts currently project a slight easing in the months ahead, most industry leaders agree: rates are not going back to 3%.
Instead, many forecasts suggest mortgage rates will settle in the mid-6% range by the end of the year, pending any major economic shifts. As Kara Ng, Senior Economist at Zillow, says:
“While Zillow expects mortgage rates to end the year near mid-6%, barring any unforeseen shocks, that path might be bumpy.”
What Buyers Should Know
Basically, waiting for 3% rates might mean waiting longer than you’d expect – and missing out along the way. Instead of putting off homebuying indefinitely, make a plan to get there and focus on what you can control: your budget, your credit, and working with a trusted professional who can explain exactly what’s happening in the current market – and how to navigate it.
Your local real estate agent and a trusted lender make all the difference in this process. The experts have insights into down payment assistance programs, alternative financing options, negotiation strategies, and overall – the experience you need on your side to understand creative ways that will make your plans work.
And here’s the biggest thing to keep in mind. Since rates are projected to ease slightly later this year, if that happens, it could bring some more buyers back into the market. Acting now gives you a head start, especially with more homes on the market than we’ve seen in years.
Think about it: if mortgage rates do come down, what do you think everyone else is going to do? That’s right – they’ll jump back in too.
Getting ahead of that rush could put you in a stronger position to find the right home with less competition. Realtor.com sums it up well:
“Staying out of the market in hopes of a rate drop that never comes can lead to missed opportunities . . . Rising home prices, rent increases, and inflation might outpace any future savings on interest. And if rates do fall sharply again, buyers could face an entirely different challenge: surging competition.”
Bottom Line
Those 3% rates everyone remembers from a few years ago were the exception, not the rule.
Now that they’re settling into new territory, it’s a good time to adjust your expectations and learn more about where things are heading as this market shifts.
A local real estate agent and a trusted lender will be your best resources, always keeping you up-to-date and informed, so you can make sense of your options and build a game plan that works for you. See Ann Arbor Condo complexes here and start dreaming about your new home! Contact The Bouma Group today at 734-761-3060 or info@condohotline.com.
Why Pre-Approval Is More Important Than Ever This Spring

Spring is here, and so is the busiest season in real estate. More buyers are out looking for homes, which means more competition for you. If you want to put yourself in the best position to buy, there’s one step you can’t afford to skip, and that’s getting a pre-approval letter for a mortgage.
Some buyers think they can wait until they’ve found a home they love before talking to a lender. But in a season where homes can sell fast, that’s a risky move. Getting pre-approved before you start your search is a much better bet.
Here’s what you need to know about this early step in the buying process.
What Is a Pre-Approval Letter?
Pre-approval gives you a sense of how much a lender is willing to let you borrow for your home loan. To determine that number, a lender starts by looking at your financial history. Here are some of the things that can have an impact, according to Yahoo Finance:
- Your debt-to-income (DTI) ratio: This is how much money you owe divided by how much money you make. Usually, you can borrow more if you have a lower DTI.
- Your income and employment status: They’re looking to verify you have a steady income coming in – that way they feel confident in your ability to repay the loan.
- Your credit score: If your score is higher, you may qualify to borrow more.
- Your payment history: Do you consistently pay your bills on time? Lenders want to know you’re not a risky borrower.
After their review, you’ll get a pre-approval letter showing what you can borrow. Having this peace of mind is a big deal – it helps you feel a lot more confident in your ability to get a home loan. And the fringe benefit is it can also speed up the road to closing day because the lender will already have a lot of your information.
It Helps You Figure Out Your Budget
Spring is a competitive season, and emotions can run high if you find yourself up against other buyers. Having a firm budget in mind is so important. You don’t want to get too attached and end up maxing out what you can borrow. As Freddie Mac explains:
“Keep in mind that the loan amount in the pre-approval letter is the lender’s maximum offer. Ultimately, you should only borrow an amount you are comfortable repaying.”
So, use this time to really buckle down on your numbers. And be sure to factor in other homeownership costs – like property taxes, insurance, and maybe even homeowner’s association fees – so you know what you can comfortably afford.
Then, partner with your agent to tailor your search to homes that match your budget. That way, you don’t fall in love with a condo or house that’s out of your financial comfort zone.
It Helps Your Offer Stand Out During the Busy Season
Spring buyers aren’t just competing for homes. They’re competing for the seller’s attention, too. And a pre-approval letter can help you stand out by showing sellers you’ve already gone through a financial check. Zillow explains it like this:
“Having a pre-approval letter handy while you’re shopping for a home can also help you act quickly once you’ve found a home you love. The letter shows potential sellers that you’re a serious buyer who has the financial means to close on the home. In a competitive market, an offer with a pre-approval letter attached will stand out among other offers that don’t include one — increasing the chances of your offer being accepted.”
That means when sellers are choosing among multiple offers, yours could rise to the top simply because you’ve already taken this step.
And here’s one final tip for you. After you receive your letter, avoid switching jobs, applying for new credit cards or other loans, co-signing for loans, or moving money in or out of your savings. That’s because any changes to your finances can affect your pre-approval status.
Bottom Line
If you’re thinking about buying a home this spring, getting pre-approved should be your first move. It’ll help you understand your budget, show sellers you’re serious, and keep you from falling in love with a house that’s out of reach. Talk to a lender to get started, we have a list of trusted people we’ve worked with that we’d be happy to share. To get started on your condo or home buying journey, contact us today at The Bouma Group, Realtors at 734-761-3060 or info@condohotline.com. Search for Ann Arbor area condos here!
What’s Behind Today’s Mortgage Rate Volatility?
If you’ve been keeping an eye on mortgage rates lately, you might feel like you’re on a roller coaster ride. One day rates are up; the next they dip down a bit. So, what’s driving this constant change? Let’s dive into just a few of the major reasons why we’re seeing so much volatility, and what it means for you.
The Market’s Reaction to the Election
A significant factor causing fluctuations in mortgage rates is the general reaction to the political landscape. Election seasons often bring uncertainty to financial markets, and this one is no different. Markets tend to respond not only to who won but also to the economic policies they are expected to implement. And when it comes to what’s been happening with mortgage rates over the past couple of weeks, as the National Association of Home Builders (NAHB) says:
“. . . the primary reason interest rates have been on the rise pertains to the uncertainty surrounding the presidential election. Although the election is now complete, there continue to be growing concerns over budget deficits.”
In the short term, this anticipation has caused a slight uptick in mortgage rates as the markets adjust and react. Additionally, factors like international tensions, supply chain disruptions, and trade policies can drive investor sentiment, causing them to seek safer assets like bonds, which can indirectly impact mortgage rates. Essentially, the more global or domestic uncertainty, the greater the chance that mortgage rates may shift.
The Economy and the Federal Reserve
Inflation and unemployment are two other big drivers of mortgage rates. The Federal Reserve (the Fed) has been working to bring inflation under control, and has been closely monitoring the economy as they do. And as long as inflation continues to moderate and the job market shows signs of maximum employment, the Fed will continue its plans to cut the Federal Funds Rate.
Although the Fed doesn’t set mortgage rates, their decisions do have an impact, and typically a cut leads to a mortgage rates response. And in their November 6-7th meeting, the Fed had the data they needed to make another cut to the Federal Funds Rate. And while that decision was expected and much of the mortgage rate movement happened prior to that meeting, there was a slight dip in rates.
What To Expect in the Coming Months
As we look ahead, mortgage rates will respond to changes in the Fed’s policies and other economic indicators. The markets will likely remain in a wait-and-see mode, reacting to each new development. And, with the transition of a new administration comes an element of unpredictability. A recent article from The Mortgage Reports explains:
“Today’s economic indicators come with mixed pressures on mortgage rates and we’re likely to be in for a good amount of volatility as markets adjust and respond to the election . . .”
The best way to navigate this landscape is to have a team of real estate experts by your side. Professionals will help you understand what’s happening and can provide you with the guidance you need to make informed housing market decisions along the way.
Bottom Line
The takeaway? Today’s mortgage rate volatility is going to continue to be driven by economic factors and political changes.
Now is the time to lean on experienced professionals. A trusted real estate agent and mortgage lender can help you navigate through it. And with the right guidance, you can make informed decisions. Contact us today at 734-761-3060 or info@condohotline.com.
Ann Arbor Condo Market Update – Fall 2024
A Deep Dive into Ann Arbor Condo Market Trends in 2024

Ann Arbor’s condo market is bustling with activity as we move through 2024. In the first three quarters alone, the data shows interesting patterns and trends that both current condo owners and potential buyers should consider. Here’s a detailed look at what you need to know.
Overview of the Ann Arbor Condo Market
- New Listings: 604 new listings have been recorded, representing a modest increase of 1.7% compared to the same period last year.
- Pending Sales: There have been 482 pending sales, showing a slight dip of 1%.
- Closed Sales: 470, marking a decrease of 2.5%.
- Days on Market: Condos are selling faster, with an average of just 35 days on the market, an impressive drop of 35%.
Pricing Trends
- Median Sales Price: The median sales price has increased by 13%, now standing at $356,000.
- Average Sales Price: This year, the average sales price has risen to $416,563, which is a 7% increase.
- Percent of List Price Received: Sellers are receiving on average 100.8% of their asking prices, a slight decrease of 0.5%.
Downtown Ann Arbor Condo Market
- Currently Active: There are 36 active listings in downtown Ann Arbor.
- Pending Listings: 26 condos are currently under contract.
- Sales Activity: There have been 77 closed sales. Notably, seven of these sales have been over $1,000,000, including four new construction units.
- Affordable Options: For those seeking more affordable options, 30 units sold under $300,000, predominantly located in Tower Plaza.
- Median and Average Sales Prices: The median sales price is $451,000, and the average sales price is $534,562.
Spotlight on Notable Sales
Most Expensive Condo Sold

101 N. Main St. #906, Downtown Ann Arbor
One North Main Condos
2,316 square feet with 3 bedrooms and 2 baths
Listed for $1,195,000
Sold for $1,625,000
13 days on market
The top-tier properties in Ann Arbor’s market continue to command significant attention. One of the most expensive condos sold this year was a luxurious unit in the heart of downtown, fetching well over $1,000,000 and showcasing the continued demand for high-end urban living.
Average Condo Sale
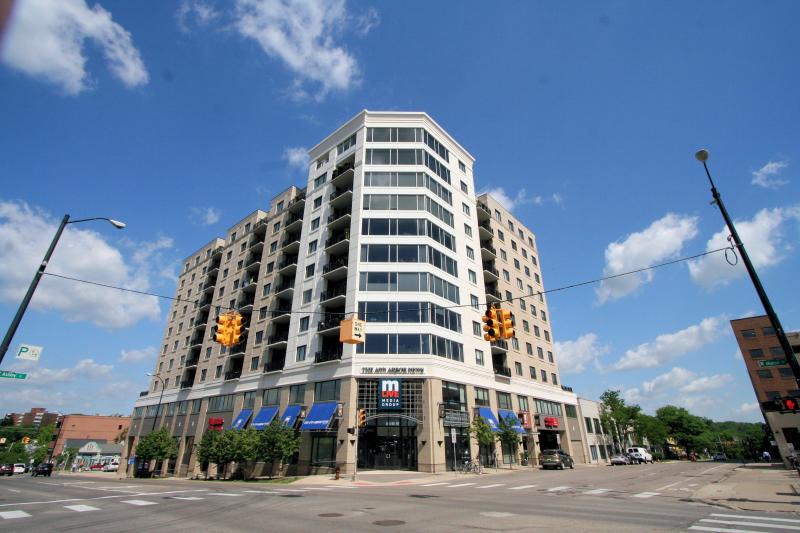
111 N. Ashley St. #604, Downtown Ann Arbor
Ashley Terrace Condos
863 square feet with 1 bedroom and 1 bath
Listed for $439,900
Sold for $420,000
27 days on market
The average condo sale in Ann Arbor reflects the broader trends of increasing prices, with typical units selling at around $416,563. These average-priced condos often offer a balanced mix of location, amenities, and value, making them appealing to a wide range of buyers.
Least Expensive Condo Sold
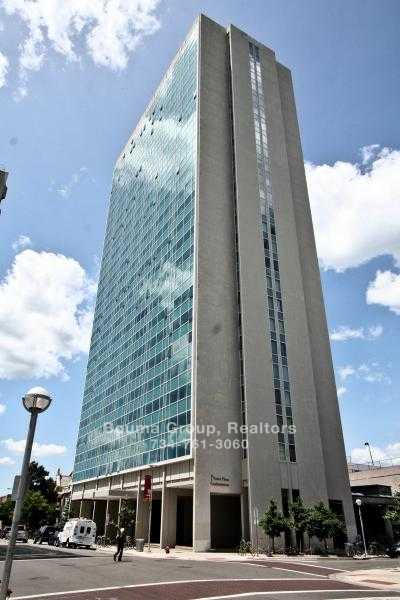
555 E. William St. #5L, Downtown Ann Arbor
Tower Plaza
430 square feet, studio with 1 full bath
Listed for $185,000
Sold for $185,000
1 Day on Market
At the other end of the spectrum, some of the least expensive condos, particularly in areas like Tower Plaza, provide affordable entry points into the Ann Arbor real estate market. These units, selling for under $300,000, offer great opportunities for first-time buyers or those looking for investment properties.
Key Takeaways for Buyers and Sellers
For buyers, the Ann Arbor condo market remains competitive, but opportunities exist across various price points. It’s essential to move quickly, given the reduced days on market. Sellers, meanwhile, can take advantage of the appreciating prices and quick sales, although it’s important to price realistically to ensure swift transactions.
Whether you’re considering buying or selling a condo in Ann Arbor, understanding these trends can help you make informed decisions. Stay tuned for more updates as the year progresses, and don’t hesitate to reach out if you’re ready to explore the Ann Arbor condo market further. Contact us today at The Bouma Group at 734-761-3060 or info@condohotline.com.
The 5 Biggest Mistakes Sellers Are Making Right Now
5 Mistakes Sellers Are Making
The housing market is going through a transition. Higher mortgage rates are causing more moderate buyer activity at the same time the supply of condos and homes for sale is growing.
And if you aren’t working with an agent, you may not realize that. Here’s the downside. You can’t adjust your strategy or expectations to today’s market if you’re not informed. And that can lead to a number of costly mistakes.
Here’s a look at some of the most common mistakes sellers are making – and how an agent will help you avoid them when you sell.
1. Overpricing Your Condo or House
Many sellers set their asking price too high and that’s why there’s an uptick in homes with price reductions today. An unrealistic price will deter potential buyers, cause an appraisal issue, or lead to your property sitting on the market longer. An article from the National Association of Realtors (NAR) explains:
“Some sellers are pricing their homes higher than ever just because they can, but this may drive away serious buyers and result in unapproved appraisals . . .”
To avoid falling into this trap, partner with a pro. An agent uses recent sales of similar properties, the condition of your property, local market trends, and so much more to find the price that’ll attract more buyers and open the door for multiple offers and a faster sale.
2. Skipping the Small Stuff
You may try to skip important repairs, thinking you can pass the task on to your buyer. But visible issues (even if they’re small) can turn off potential buyers and result in lower offers or demands for concessions. As Money Talks News says:
“Home shoppers like to turn on lights, flush toilets and run the water. If these basic things don’t work, they may assume you’ve skipped other maintenance. Homes that appear neglected aren’t likely to fetch top price.”
If you want to get your place ready to sell, the best place to turn to for advice is your agent. They’ll be able to do a walk-through with you and point out anything you’ll need to tackle before the photographer comes in.
3. Not Looking at Things Objectively
Buyers today are feeling the pinch of high prices and mortgage rates. With affordability that tight, they may come in with an offer that’s lower than you’d want to see – especially if you didn’t stage, price, or market the house well.
It’s important you don’t take this personally. Getting overly emotional can put the sale at risk. As an article from Ramsey Solutions says:
“Remember, a buyer’s offer is not a reflection of their opinion of your home or your housekeeping abilities. . . The sale of your home is strictly a business transaction. If they start out with a low offer, don’t take it personally and get emotional. Instead, channel that energy toward negotiating. Work with your agent and make a counteroffer.”
4. Being Unwilling To Negotiate
The supply of condos and homes for sale has grown. That means buyers have more options, and with that comes more negotiation power. As a seller, you may see more buyers getting an inspection, requesting repairs, or asking for help with closing costs today. You need to be prepared to have those conversations. As U.S. News Real Estate explains:
“If you’ve received an offer for your house that isn’t quite what you’d hoped it would be, expect to negotiate . . . the only way to come to a successful deal is to make sure the buyer also feels like he or she benefits . . . consider offering to cover some of the buyer’s closing costs or agree to a credit for a minor repair the inspector found.”
An agent will walk you through what levers you may want to pull based on your own goals, budget, and timeframe.
5. Not Using a Real Estate Agent
Notice anything? For each of these mistakes, partnering with an agent helps prevent them from happening in the first place. That makes trying to sell your condo or house without an agent’s help the biggest mistake of all.
Real estate agents have experience and expertise in pricing, marketing, negotiating, and more. That knowledge streamlines the selling process and usually results in drumming up more interest and ultimately can get you a higher final price.
Bottom Line
If you want to avoid these mistakes sellers are making, let’s connect to make sure you’re set up for success. Contact us at The Bouma Group at 734-761-3060 or info@condohotline.com today! We can help you navigate this ever-changing market and personalize a plan for you.
Pre-Approval in 2023: What You Need To Know
Pre-Approval in 2023: What You Need To Know
One of the first steps in your condo or home-buying journey is getting pre-approved. To understand why it’s such an important step, you need to understand what pre-approval is and what it does for you. Business Insider explains:
“In a preapproval [sic], the lender tells you which types of loans you may be eligible to take out, how much you may be approved to borrow, and what your rate could be.”
Basically, pre-approval gives you critical information about the buying process that’ll help you understand your options and what you may be able to borrow.
How does it work? As part of the pre-approval process, a lender will look at your finances to determine what they’d be willing to loan you. From there, your lender will give you a pre-approval letter to help you understand how much money you can borrow. That can make it easier when you set out to search for condos or homes because you’ll know your overall numbers. And with higher mortgage rates impacting affordability for many buyers today, a solid understanding of your numbers is even more important.
Pre-Approval Helps Show You’re a Serious Buyer
Another added benefit is pre-approval can help a seller feel more confident in your offer because it shows you’re serious about buying their property. A recent article from Forbes notes:
“From the seller’s perspective, a preapproval [sic] letter from a reputable local lender often can make the difference between accepting and rejecting an offer.”
This goes to show, even though you may not face the intense bidding wars you saw if you tried to buy during the pandemic, pre-approval is still an important part of making a strong offer. In fact, Christy Bieber, Personal Finance Writer at The Motley Fool explains it may be the most important part of making an offer:
“Pre-approval maximizes the chances you’ll be able to actually close the deal – and sellers want to see that.
The fact that a pre-approval gives you a better chance of getting your offer accepted is undoubtedly the most important reason to complete this step . . .”
Bottom Line
Getting pre-approved is an important first step toward buying a condo or home. It lets you know what you can borrow and shows sellers you’re serious about purchasing their condo or home. Connect with a local real estate professional and a trusted lender so you have the tools you need to purchase in today’s market. Contact us at 734-761-3060 or info@condohotline.com to discuss your path to ownership!