
Gen Z: The Next Generation Is Making Moves in the Housing Market
Gen Z: The Next Generation Is Making Moves in the Housing Market
Gen Z (Generation Z) is eager to put down their own roots and achieve financial independence. As a result, they’re turning to homeownership. According to the latest Home Buyers and Sellers Generational Trends Report from the National Association of Realtors (NAR), 30% of Gen Z buyers transitioned straight from living under their parents’ roofs to owning their own homes.
If you’re a member of this generation, and you’re interested in pursuing your own dream of homeownership, here’s some information you may find helpful on why and where your peers are buying.
The Reasons Gen Z Want To Become Homeowners
A recent survey by Rocket Mortgage identifies some of the top motivators driving Gen Z buyers to purchase a home:
“Of those surveyed, 34% said that starting or growing their family was their main motivation to buy a home. . . . Along with growing a family comes establishing a home base.”
Another key reason the survey says Gen Z wants to buy is because homeownership can give them more stability (20.8%). That’s because buying a home allows you to stabilize what’s typically your biggest monthly expense: your housing cost.
When you have a fixed-rate mortgage on your home, you can lock in your monthly payment for the duration of your loan, often 15 to 30 years. If you keep renting, you don’t have that same benefit, and you won’t be protected from rising housing costs.
So, if you’re ready to start a new chapter in your life or if you’re craving more stability, know that your peers feel the same way, and those motivators are why they’re turning to homeownership.
Gen Z’s Next Stop: Where Are They Making Their Moves?
If those reasons have you feeling ready to buy, here’s some information on where your peers are finding their homes that could help you with your search. According to a recent Lending Tree survey, Gen Z buyers are focusing on more affordable areas to help boost their buying power and offset the challenges that come with today’s mortgage rates.
Many Gen Z buyers still want the convenience and excitement of city life, but also value the affordability, open air, and space more suburban areas offer. Jacob Channel, Senior Economist at LendingTree, explains:
“. . . they want to live in a city, but they also want to be close to nature.”
Locating a home that offers both of those things requires expertise. Working with a trusted real estate professional can help you find a home in your budget and desired area. Your agent will know the most affordable neighborhoods to search in. They can also highlight the amenities and features that the location offers and how those are aligned with your goals. They’ll also be able to walk you through how things like remote work can help you cast a broader net for your search.
Bottom Line
If you’re a member of Gen Z and are just getting started on your homebuying journey, or if you want to learn more about the process, let’s connect. That way, you have a guide to help you find a home that fits both your lifestyle and your budget. Contact us at The Bouma Group, Realtors today at 734-761-3060 or info@condohotline.com, and let’s get started!
Keys to Success for First-Time Homebuyers
Keys to Success for First-Time Homebuyers
Buying your first home is an exciting decision and a major milestone that has the power to change your life for the better. As a first-time homebuyer, it’s a vision you can bring to life, but, as the National Association of Realtors (NAR) shares, you’ll have to overcome some factors that have made it more challenging in recent years:
“Since 2011, the share of first-time home buyers has been under the historical norm of 40% as buyers face tight inventory, rising home prices, rising rents and high student debt loads.”
That said, if you’re looking to purchase your first home, here are two things you can consider to help make your dreams a reality.
1. Save Money with First-Time Homebuyer Programs
As a first-time homeowner, the initial costs and fees can seem overwhelming and insurmountable. From securing a loan to putting together a down payment and covering closing costs, the expenses can feel like a significant obstacle to overcome.
Fortunately, there are a lot of public and private first-time homebuyer programs that can help you get a loan with little-to-no money upfront. CNET explains:
“A first-time homebuyer program can help make homeownership more affordable and accessible by offering lower mortgage rates, down payment assistance and tax incentives.”
As Bankrate says, many of these programs are offered by state and local governments:
“Many states and local governments have programs that offer down payment or closing cost assistance – either low-interest-rate loans, deferred loans or even forgivable loans (aka grants) – to people looking to buy their first house . . .”
To take advantage of these programs, contact the housing authority in your state and browse sites like Down Payment Resource.
2. The Supply of Homes for Sale Is Low, So Explore Every Possibility
In today’s real estate market, it’s a challenge for buyers to find the right home due to limited supply. However, there are ways to expand your options and increase your chances of finding a home that fits your needs. One option is to consider townhomes or condominiums, which are often more affordable than single-family homes. While they may be smaller, they still offer the opportunity to own a home and build equity. Additionally, they typically require less maintenance, which can be a major advantage. To ensure a successful home-buying experience, especially if you’re a first-time buyer, it’s wise to seek the guidance of a trusted real estate agent. They can provide valuable insights about the home buying process, help you locate suitable options in your area, and assist you in making competitive offers.
Bottom Line
If you are a first-time homebuyer, navigating today’s seller’s market can be difficult. However, there are solutions available to help you achieve your goals, such as utilizing first-time homebuyer programs and exploring all of your housing options. If you need guidance, feel free to reach out to us at The Bouma Group, Realtors at 734-761-3060 or info@condohotline.com. We’re here to provide expert assistance and support throughout the process.
Have You Considered Adding Condos to Your Home Search?
Reasons To Consider Condos in Your Home Search
Are you having trouble finding a home that fits your needs and your budget? If so, you should know there’s an option worth considering – condominiums, also known as condos. According to Bankrate:
“A condo can be a more affordable entry point to homeownership than a single-family home. And as a homeowner, you’ll build equity over time and have access to tax benefits that a renter wouldn’t.”
That’s why expanding your search to include additional housing types, like condominiums, could help you accomplish your homeownership goals this spring, especially if you can be flexible about the space you need. Condos are typically smaller than a single-family home, but that’s part of what can make them more budget-friendly (see graph below):

In addition to providing more options in your home search and possibly your price point, there are several other benefits to condo living. They tend to require less upkeep and lower maintenance – and that can give you more time to spend doing the things you enjoy. Plus, since many condos are in or near city centers, they offer the added benefit of being in close proximity to work and leisure.
Condo Price vs. Home Price in the Ann Arbor Area
In the Ann Arbor Area, we are seeing the median sales price a bit lower than nationally. For sales in 2023 Year to Date, condos have a Median Sales Price of $269,500 vs. $350,000 for Single Family Homes.
Remember, your first home doesn’t have to be your forever home. The important thing is to get your foot in the door as a homeowner so you can start building wealth in the form of home equity. In time, the equity you develop can fuel a future purchase if your needs change.
Ultimately, owning and living in a condo can be a lifestyle choice. And if that appeals to you, they could provide the added options you need in today’s market.
Bottom Line
It could make a lot of sense to add condos to your home search. Let’s connect today at 734-761-3060 or info@condohotline.com if you’re ready to check out the options in the Ann Arbor area!
Taking the Fear out of Saving for a Condo or Home
If you’re planning to buy a condo or home, knowing what to budget for and how to save may sound scary at first. But it doesn’t have to be. One way to take the fear out of budgeting is to understand some of the costs you might encounter. And to do that, turn to trusted real estate professionals. They can help you plan your finances and prepare your budget.
Here are just a few costs experts say you can expect.
1. Down Payment
Saving for your down payment is likely top of mind as you set out to buy a condo or home. But do you know how much you’ll need to save? While each situation is different, there’s a common misconception that putting 20% down toward your purchase is required. An article from the Mortgage Reports explains why that’s not always the case:
“The idea that you have to put 20% down on a house is a myth. . . . The right amount depends on your current savings and your home buying goals.”
To understand your options, partner with a trusted real estate professional to go over the various loan types, down payment assistance programs, and what each one requires.
2. Closing Costs
Make sure you also budget for closing costs, which are a collection of fees and payments made to the various people involved in your transaction. Bankrate explains:
“Closing costs are the fees you pay when finalizing a real estate transaction, whether you’re refinancing a mortgage or buying a new home. These costs can amount to 2 to 5 percent of the mortgage so it’s important to be financially prepared for this expense.”
The best way to understand what you’ll need at the closing table is to work with a trusted lender. They can provide you with answers to the questions you might have.
3. Earnest Money Deposit
If you want to cover all your bases, you can also consider saving for an earnest money deposit (EMD). An EMD is money you pay as a show of good faith when you make an offer on a house. According to realtor.com, it’s usually between 1% and 2% of the total home price.
This deposit works like a credit. It’s not an added expense – it’s paying a portion of your costs upfront. You’re using some of the money you already saved for your purchase to show the seller you’re committed and serious about their house. Realtor.com describes how it works as part of your sale:
“It tells the real estate seller you’re in earnest as a buyer, . . . . Assuming that all goes well and the buyer’s good-faith offer is accepted by the seller, the earnest money funds go toward the down payment and closing costs. In effect, earnest money is just paying more of the down payment and closing costs upfront.”
Keep in mind, an EMD isn’t required, and it doesn’t guarantee your offer will be accepted. It’s important to work with a real estate advisor to understand what’s best for your situation and any specific requirements in your area. They’ll help you determine what moves you should make in the home-buying process to have the greatest success.
Bottom Line
Budgeting for your condo or home purchase doesn’t have to be scary! Let’s connect so you’ll have an expert on your side to answer any questions you have along the way. Contact us today at The Bouma Group, Realtors to learn more at 734-761-3060 or info@bouma.com.
What You Should Know About Closing Costs
How to Plan Ahead for Closing Costs
Before you buy a home, it’s important to plan ahead. While most buyers consider how much they need to save for a down payment, many are surprised by the extra fees they have to pay. To ensure you aren’t caught off guard when it’s time to close on your home, you need to understand what closing costs are and how much you should budget for.
What Are Closing Costs?
People are sometimes surprised by closing costs because they don’t know what they are. According to Bankrate:
“Closing costs are the fees and expenses you must pay before becoming the legal owner of a house, condo or townhome . . . Closing costs vary depending on the purchase price of the home and how it’s being financed . . .”
In other words, your closing costs are a collection of fees and payments involved with your transaction. According to Freddie Mac, while they can vary by location and situation, they typically include:
- Government recording costs
- Appraisal fees
- Credit report fees
- Lender origination fees
- Title services
- Tax service fees
- Survey fees
- Attorney fees
- Underwriting Fees
How Much Will You Need To Budget for Closing Costs?
Understanding what they include is important, but knowing what you’ll need to budget to cover them is critical, too. According to the Freddie Mac article mentioned above, the costs to close are typically between 2% and 5% of the total purchase price of your condo or home. With that in mind, here’s how you can get an idea of what you’ll need to cover your closing costs.
Let’s say you find a condo or home you want to purchase for the median price of $366,900. Based on the 2-5% Freddie Mac estimate, your closing fees could be between roughly $7,500 and $18,500.
Keep in mind, if you’re in the market for a condo or home above or below this price range, your closing costs will be higher or lower.
What’s the Best Way To Make Sure You’re Prepared at Closing Time?
Freddie Mac provides great advice for homebuyers, saying:
“As you start your homebuying journey, take the time to get a sense of all costs involved – from your down payment to closing costs.”
Work with a team of trusted real estate professionals to understand exactly how much you’ll need to budget for everything. We can help connect you with a trusted, local lender, and together we can answer any questions you might have.
Bottom Line
It’s important to plan for the fees and payments you’ll be responsible for at closing. Let’s connect so I can help you feel confident throughout the process. Contact us today at The Bouma Group, Realtors at 734-761-3060 or info@condohotline.com.
Pre-Approval in 2023: What You Need To Know
Pre-Approval in 2023: What You Need To Know
One of the first steps in your condo or home-buying journey is getting pre-approved. To understand why it’s such an important step, you need to understand what pre-approval is and what it does for you. Business Insider explains:
“In a preapproval [sic], the lender tells you which types of loans you may be eligible to take out, how much you may be approved to borrow, and what your rate could be.”
Basically, pre-approval gives you critical information about the buying process that’ll help you understand your options and what you may be able to borrow.
How does it work? As part of the pre-approval process, a lender will look at your finances to determine what they’d be willing to loan you. From there, your lender will give you a pre-approval letter to help you understand how much money you can borrow. That can make it easier when you set out to search for condos or homes because you’ll know your overall numbers. And with higher mortgage rates impacting affordability for many buyers today, a solid understanding of your numbers is even more important.
Pre-Approval Helps Show You’re a Serious Buyer
Another added benefit is pre-approval can help a seller feel more confident in your offer because it shows you’re serious about buying their property. A recent article from Forbes notes:
“From the seller’s perspective, a preapproval [sic] letter from a reputable local lender often can make the difference between accepting and rejecting an offer.”
This goes to show, even though you may not face the intense bidding wars you saw if you tried to buy during the pandemic, pre-approval is still an important part of making a strong offer. In fact, Christy Bieber, Personal Finance Writer at The Motley Fool explains it may be the most important part of making an offer:
“Pre-approval maximizes the chances you’ll be able to actually close the deal – and sellers want to see that.
The fact that a pre-approval gives you a better chance of getting your offer accepted is undoubtedly the most important reason to complete this step . . .”
Bottom Line
Getting pre-approved is an important first step toward buying a condo or home. It lets you know what you can borrow and shows sellers you’re serious about purchasing their condo or home. Connect with a local real estate professional and a trusted lender so you have the tools you need to purchase in today’s market. Contact us at 734-761-3060 or info@condohotline.com to discuss your path to ownership!
Mortgage Rates Are Dropping. What Does That Mean for You?
Mortgage Rates Are Dropping. What Does That Mean for You?
Mortgage rates have been a hot topic in the housing market over the past 12 months. Compared to the beginning of 2022, rates have risen dramatically. Now they’re dropping, and that has to do with everything happening in the economy.
Nadia Evangelou, Senior Economist and Director of Forecasting at the National Association of Realtors (NAR), explains it well by saying:
“Mortgage rates dropped even further this week as two main factors affecting today’s mortgage market became more favorable. Inflation continued to ease while the Federal Reserve switched to a smaller interest rate hike. As a result, according to Freddie Mac, the 30-year fixed mortgage rate fell to 6.31% from 6.33% the previous week.”
So, what does that mean for your homeownership plans? As mortgage rates fluctuate, they impact your purchasing power by influencing the cost of buying a home. Even a small dip can help boost your purchasing power. Here’s how it works.
The median-priced home according to the National Association of Realtors (NAR) is $379,100. So, let’s assume you want to buy a $400,000 home. If you’re trying to shop at that price point and keep your monthly payment about $2,500-2,600 or below, here’s how your purchasing power can change as mortgage rates move up or down (see chart below). The red shows payments above that threshold and the green indicates a payment within your target range.
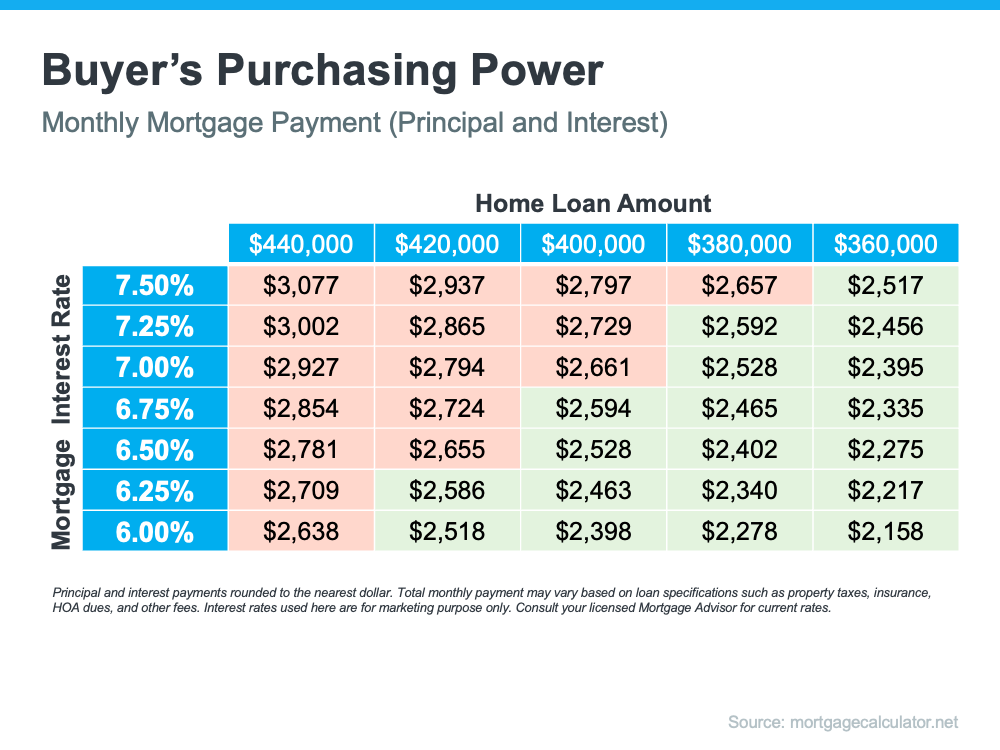
This goes to show, even a small quarter-point change in mortgage rates can impact your monthly mortgage payment. That’s why it’s important to work with a trusted real estate professional who follows what the experts are projecting for mortgage rates for the days, months, and year ahead.
Bottom Line
Mortgage rates are likely to fluctuate depending on what happens with inflation moving forward, but they have dropped slightly in recent weeks. If a 7% rate was too high for you, it may be time to contact a lender to see if the current rate is more in line with your goal for a monthly housing expense. Contact us today at 734-761-3060 to discuss your condo or home-owning plans and let our team of specialists help you achieve them! 734-761-3060 or info@condohotline.com.
You May Have More Negotiation Power in Today’s Condo Market
Did the frequency and intensity of bidding wars over the past two years make you put your home search on hold? If so, you should know the hyper-competitive market has cooled this year as buyer demand has moderated and housing supply has grown. Those two factors combined mean you may see less competition from other buyers leading to better negotiations.
And with less competition comes more opportunity. Here are two trends that may be the news you need to reenter the market.
1. The Return of Contingencies
Over the last two years, more buyers were willing to skip important steps in the homebuying process, like the appraisal or the inspection, in hopes of gaining an advantage in a bidding war. But now, things are different.
The latest data from the National Association of Realtors (NAR) shows the percentage of buyers waiving their home inspection or appraisal is down. And a recent article from realtor.com points out more sellers are accepting contingencies:
“A year ago, sellers were calling all the shots and buyers were launching legendary bidding wars, waiving contingencies, and paying for homes in cash. But now, the shoe is on the other foot, and 92% of home sellers are accepting some buyer-friendly terms (frequently related to home inspections, financing, or appraisals), . . .”
This doesn’t mean we’re in a buyers’ market now, but it does mean you have a bit more leverage when it comes time to negotiate with a seller. The days of feeling like you may need to waive contingencies or pay drastically over asking price to get your offer considered may be coming to a close.
2. Sellers Are More Willing To Help with Closing Costs
Before the pandemic, it was a common negotiation tactic for sellers to cover some of the buyer’s closing costs to sweeten the deal. This didn’t happen as much during the peak buyer frenzy over the past two years.
Today, data suggests this is making a comeback. A realtor.com survey shows 32% of sellers paid some or all of their buyer’s closing costs. This may be a negotiation tool you’ll see as you purchase a home. Just keep in mind, limits on closing cost credits are set by your lender and can vary by state and loan type. Work closely with your loan advisor to understand how much a seller can contribute to closing costs in your area.
Bottom Line
Despite the extremely competitive housing market of the past several years, today’s data suggests negotiations are starting to come back to the table. Let’s connect today to find out how the market is shifting in our area. Contact us, the Ann Arbor Condo Specialists at The Bouma Group at 734-761-3060 or info@condohotline.com.
3 Trends That Are Good News for Today’s Condo and Home Buyers
While higher mortgage rates are creating affordability challenges for condo and homebuyers this year, there is some good news for those people still looking to buy a home.
As the market has cooled this year, some of the intensity buyers faced during the peak frenzy of the pandemic has cooled too. Here are 3 trends that may benefit you when you buy a home today.
1. More Homes To Choose from
During the pandemic, housing supply hit a record low while buyer demand skyrocketed. This combination made finding a condo or home difficult because there just wasn’t enough to meet buyer demand. According to Calculated Risk, the supply of homes for sale increased by 39.5% for the week ending October 28 compared to the same week last year.
Even though it’s still a sellers’ market and supply is still lower than more normal levels, you have more to choose from in your home search. That makes finding your dream home a bit less difficult.
2. Bidding Wars Have Eased
One of the top stories in real estate over the past two years was the intensity and frequency of bidding wars. But today, things are different. With more options, you’ll likely see less competition from other buyers. According to the National Association of Realtors (NAR), the average number of offers on recently sold homes has declined. This September, the average was 2.5 offers per sale. In contrast, last September, the average was 3.7 offers per sale.
If you tried to buy a house or condo over the past two years, you probably experienced the bidding war frenzy firsthand and may have been outbid on several homes along the way. Now you have a chance to jump back into the market and enjoy searching with less competition.
3. More Negotiation Power
And when you have less competition, you also have more negotiating power as a buyer. Over the last two years, more buyers were willing to skip essential steps in the home buying process, like the appraisal or inspection, to try to win a bidding war. But the latest data from the National Association of Realtors (NAR) shows the percentage of buyers waiving those contingencies is going down.
As a buyer, this is good news. The appraisal and the inspection give you important information about the value and condition of the condo or home you’re buying. And if something turns up in the inspection, you have more power today to renegotiate with the seller.
A survey from realtor.com confirms more sellers are accepting offers that include contingencies today. According to that report, 95% of sellers said buyers requested a home inspection, and 67% negotiated with buyers on repairs as a result of the inspection findings.
Bottom Line
If you are on the fence about whether or not to begin your condo or home search, consider these 3 trends that favor the buyer! While buyers still face challenges today, they’re not necessarily the same ones you may have been up against just a year or so ago. If you were outbid or had trouble finding a condo or home in the past, now may be the moment you’ve been waiting for. Let’s connect to start the homebuying process today. Contact us at 734-761-3060 or info@condohotline.com to start your search!
Four Things That Help Determine Your Mortgage Rate
Four Things That Help Determine Your Mortgage Rate
If you’re looking to buy a condo or a home, you probably want to secure the lowest interest rate possible for your mortgage loan. Over the last couple of years, that was easier to do as the housing market saw record-low mortgage rates, but this year rates have risen dramatically.
If you’re looking for ways to combat today’s higher rates and lock in the lowest one you can, here are a few factors to focus on. Since approval opportunities can vary, connect with a trusted lender for customized advice.
Your Credit Score
Credit scores can play a big role in your mortgage rate. Freddie Mac explains:
“When you build and maintain strong credit, mortgage lenders have greater confidence when qualifying you for a mortgage because they see that you’ve paid back your loans as agreed and used your credit wisely. Strong credit also means your lender is more apt to approve you for a mortgage that has more favorable terms and a lower interest rate.”
That’s why it’s important to maintain a good credit score. If you want to focus on improving your score, your trusted advisor can give you expert advice to help.
Your Loan Type
There are many types of loans, each offering different terms for qualified buyers. The Consumer Financial Protection Bureau (CFPB) says:
“There are several broad categories of mortgage loans, such as conventional, FHA, USDA, and VA loans. Lenders decide which products to offer, and loan types have different eligibility requirements. Rates can be significantly different depending on what loan type you choose.”
When working with your real estate advisor, make sure you find out what’s available in your area and which types of loans you may qualify for.
Your Loan Term
Another factor to consider is the term of your loan. Just like with location and loan types, you have options. Freddie Mac says:
“When choosing the right home loan for you, it’s important to consider the loan term, which is the length of time it will take you to repay your loan before you fully own your home. Your loan term will affect your interest rate, monthly payment, and the total amount of interest you will pay over the life of the loan.”
Depending on your situation, the length of your loan can also change your mortgage rate.
Your Down Payment
If you’re a current homeowner looking to sell and make a move, you can use the home equity you’ve built over time toward the down payment on your next home. The CFPB explains:
“In general, a larger down payment means a lower interest rate, because lenders see a lower level of risk when you have more stake in the property. So if you can comfortably put 20 percent or more down, do it—you’ll usually get a lower interest rate.”
To learn more, connect with a lender to find out the difference a higher down payment can make for your new mortgage. We have a terrific list of local lenders, just ask us!
Bottom Line
These are just a few factors that can help determine your mortgage rate if you’re buying a condo or home. The best thing you can do is have a team of professionals on your side. Connect with us, The Bouma Group, your local real estate professionals, and a trusted lender so you have the expert advice you need at each step of the process. Contact us today at 734-761-3060 or info@condohotline.com.