
Unpacking the Real Cost of Condo Living: A Guide to Understanding Condo HOA Fees
A Condo Buyers Guide to HOA Fees
For potential condo buyers, the allure of low-maintenance luxury living often comes with a not-so-glamorous caveat—monthly condo association fees, otherwise known as HOA (Homeowners’ Association) fees. Beyond the catchy “lock-and-leave” lifestyle advertised, these fees can significantly impact your financial obligations and the value you receive from your investment. In this comprehensive guide, we’ll demystify the sometimes murky waters of HOA fees so you can make the most informed decisions about your future condo purchase.
The ABCs of Condo HOA Fees
Defining the Terms
Before you can truly grasp the implications of HOA fees, it’s essential to understand what they are. These fees are recurring payments made by condo or single-family home owners within a particular community or building. The fees cover shared expenses, from maintenance and repairs to community amenities and even insurance for common areas.
The Financial Breakdown
Condo fees can vary significantly based on various factors such as the location, age, and building amenities. The key is transparency—potential buyers should be provided with a detailed breakdown of these costs before closing day. Remember, not all HOA fees are created equal. Some may seem hefty at first glance, but if they include utilities and significant community perks, they could actually offer a better deal than seemingly lower fees that hide additional costs.
Understanding the Purpose
What exactly are you paying for with your HOA fees? Typically, these funds are allocated to address the following:
- Maintenance: Routine upkeep of the building’s exterior, common areas, and shared amenities is a non-negotiable component of HOA fees.
- Utilities: Heating, water, waste removal, and electricity for common areas may be covered, reducing individual expenses.
- Reserve Funds: For future repairs and major projects, the association should set aside a portion of fees to avoid special assessments.
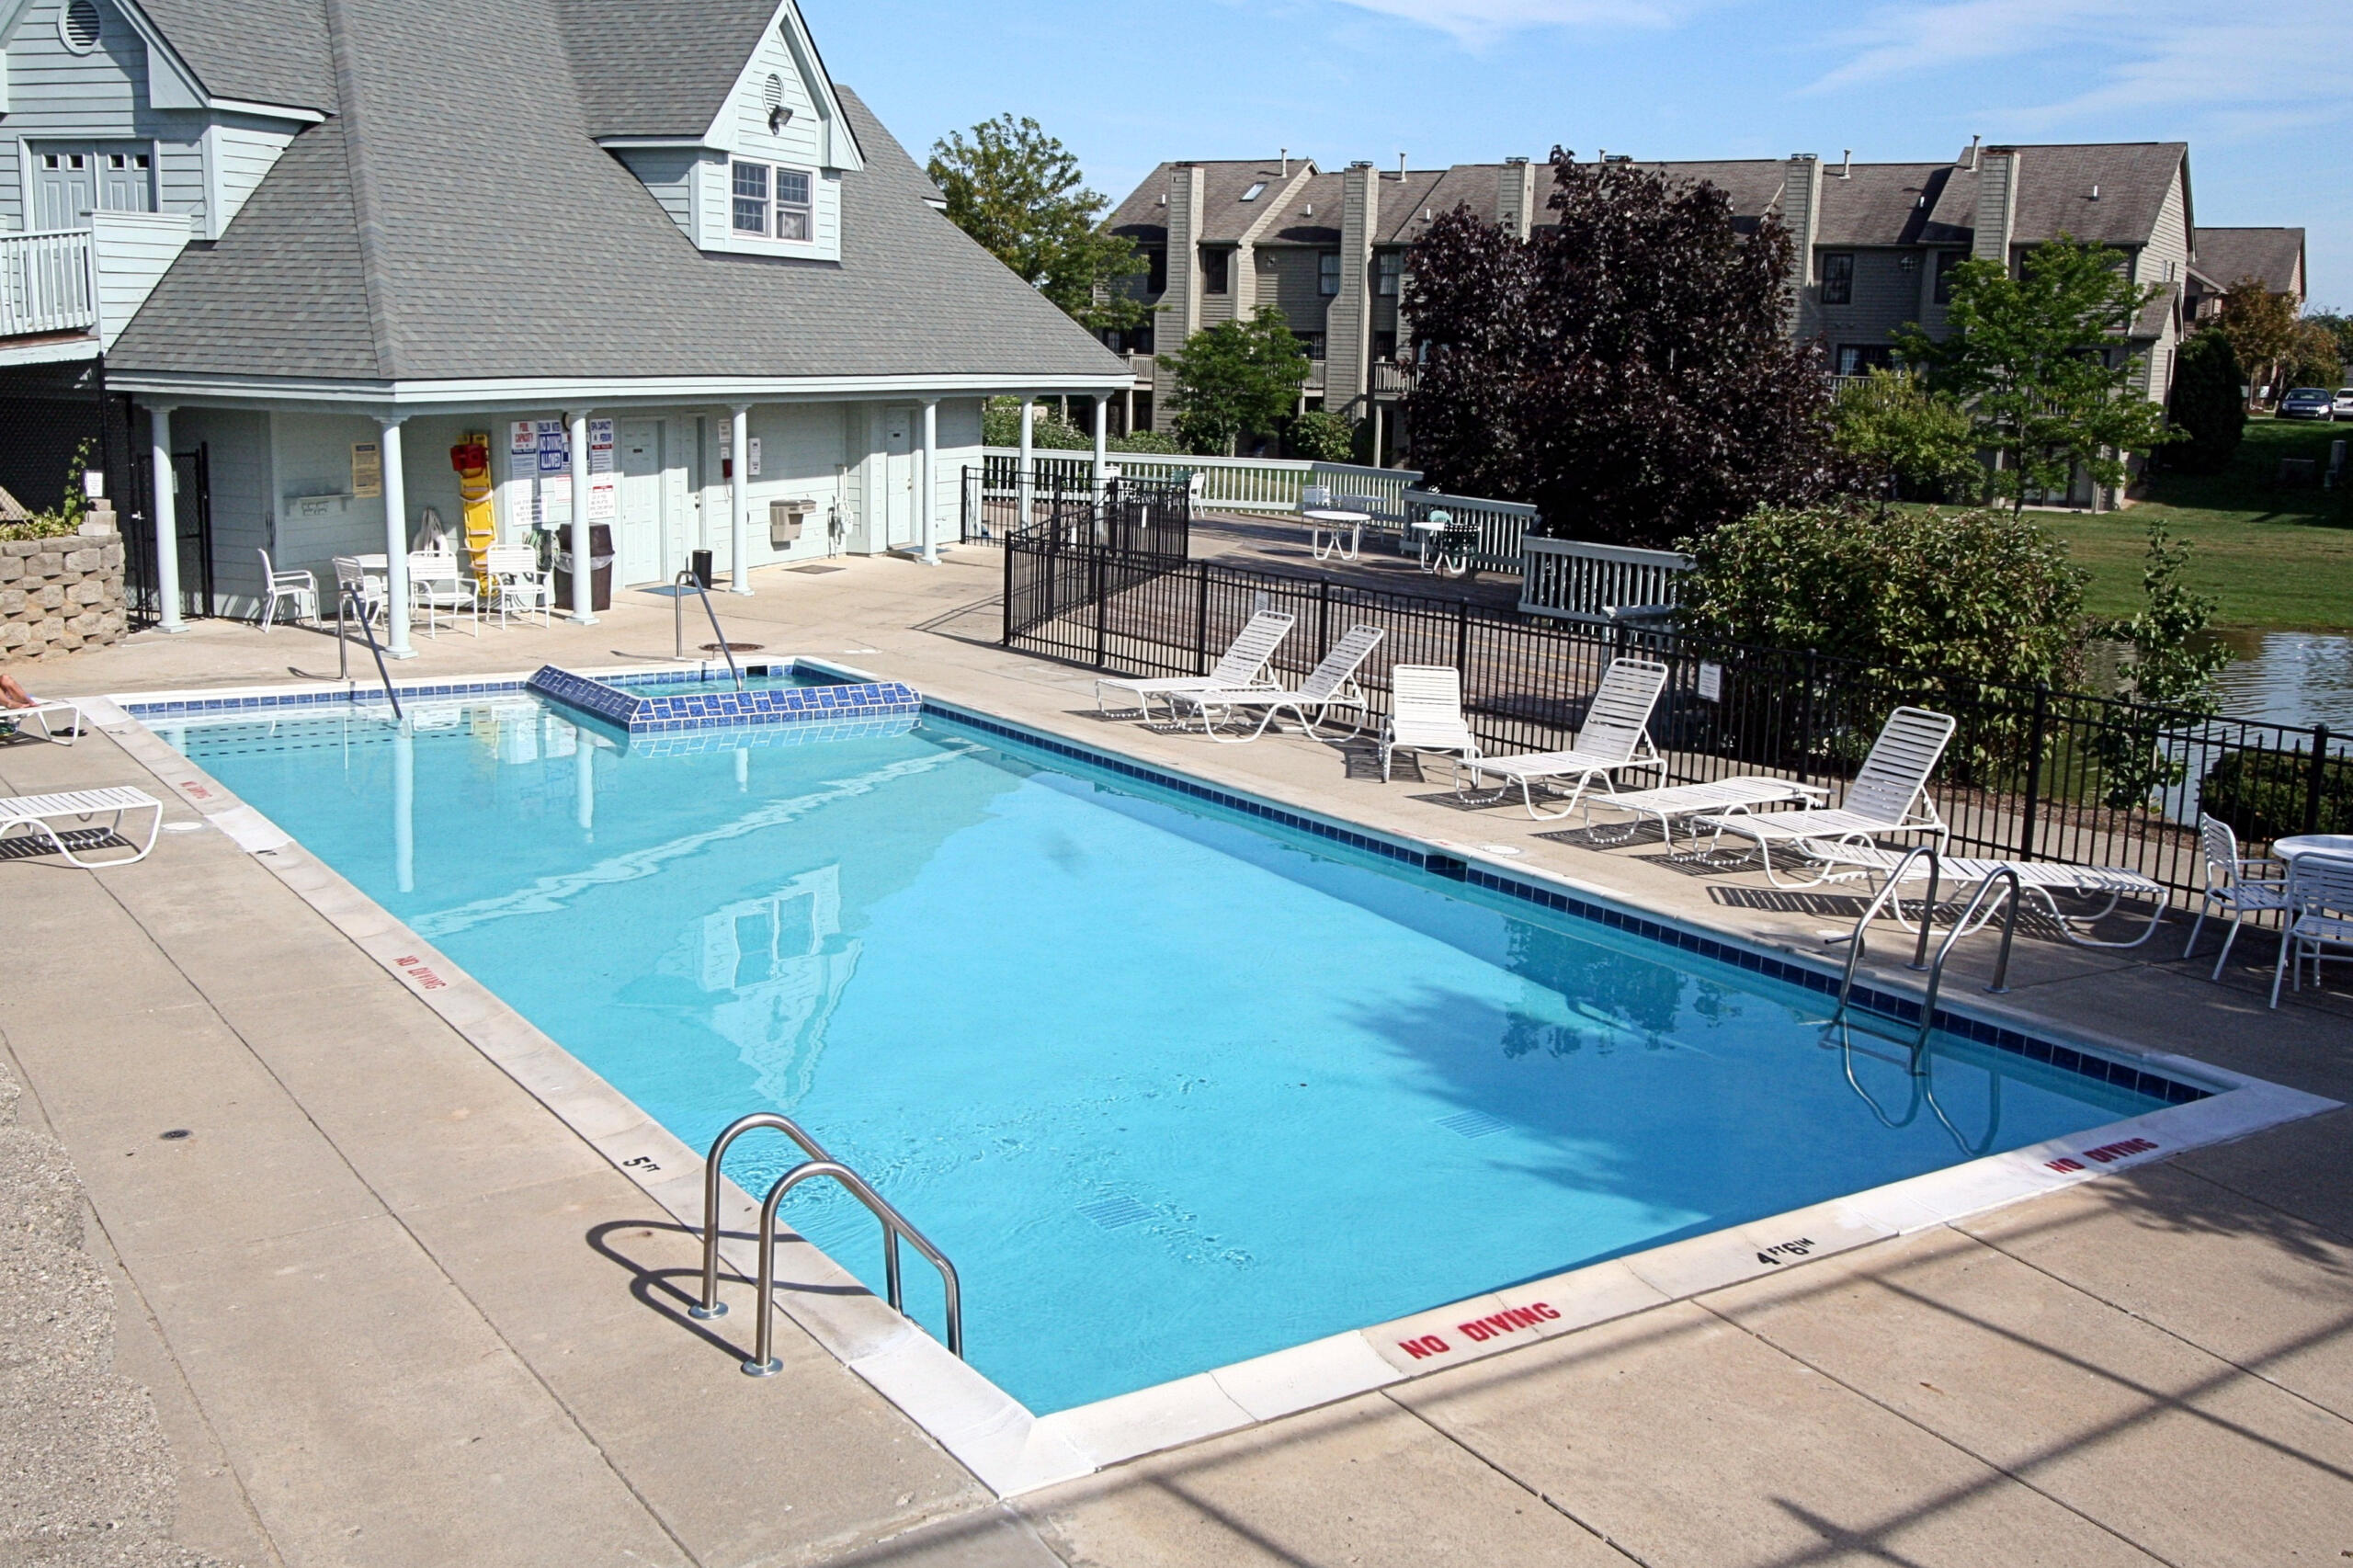
- Amenities: Pools, gyms, community rooms, and other facilities often require ongoing maintenance and insurance.
The Condo Association: Your Fee Guardians
The Role of the Association Board
The condo association board is a critical player in the management of your HOA fees. Elected by unit owners, the board establishes the annual budget, enforces community rules, and makes both minor and major decisions about the building’s operations. Engage with the board and attend meetings to ensure that your financial contributions are being used effectively and reflect your needs and desires as a member of the community.
Decoding the Association Documents
Before you even start calculating your budget with HOA fees in mind, it’s essential to review the association’s financial documents. The master deed and bylaws will detail how fees are determined, any limitations on increasing fees, and what rights and responsibilities the association has in spending these funds.
Special Assessments and Your Pocket
In some instances, HOA fees won’t be enough to cover significant unforeseen expenses, or the association may decide to undertake a large-scale improvement project. This is where special assessments come in, extra fees charged to unit owners to cover these costs. To protect your finances, ensure the association maintains a solid reserve fund and has a clear policy on when special assessments may be levied.
Additional Considerations for Prospective Condo Buyers
Planning for Future HOA Fee Hikes
HOA fees are not stagnant. They can—and often do—increase over time. It’s crucial to understand the underlying reasons for increases and budget for these changes. Factors that may lead to fee hikes include rising insurance costs, aging building infrastructure, or new amenities.
The Fine Print on Pet Policies and Parking
Some fees may not be explicitly labeled as HOA fees and can contribute significantly to your living expenses. Non-refundable pet deposits, monthly pet rent, or charges for dedicated parking spaces can add up quickly and should be factored into your housing budget.
The Social and Lifestyle Value of HOA Fees
While the financial aspects of these fees are critical, don’t overlook the social and lifestyle benefits they can offer. Access to well-maintained amenities and the community’s shared environment are significant perks. They can enhance your quality of life and often justify the associated costs.
In conclusion, condo HOA fees can be a source of contention or a ticket to a fulfilling housing experience. It all comes down to knowledge and participation. You can turn what might seem like a financial burden into a wise investment in your future home by understanding what HOA fees encompass, being well-informed about your association’s practices, and making choices that align with your financial and lifestyle goals. Take the time to dig deep and when the time comes to commit, do so with confidence and a complete understanding of what you’re getting into. Your dream condo may be waiting for you – HOA fees and all. So, carefully consider all aspects before making a decision. To learn more about the condo-buying process, contact us at 734-761-3060 or info@condohotline.com. Search for your dream condo here!
How to Stop Renting and Become a First-Time Homebuyer
The First-Time Homebuyer Plan
Key Takeaways:
- Renting doesn’t help build a future
- Homeownership can be accessible
- Contact your trusted local agents for more on being a first-time homebuyer
Many renters discover a universal truth—renting can often feel like it lacks long-term benefits. However, each monthly rent payment potentially reduces a landlord’s mortgage while increasing their home equity. This revelation may inspire some to transition from renters to first-time homebuyers. If you’re contemplating this life-changing decision, now is an opportune time to consider buying a home.
The appeal of escaping ever-increasing rental rates motivates many first-time condo buyers. Ready to join this progressive march towards homeownership? We are here to guide you through each step of the process. Here’s a simple guide to get you started on your homeownership journey.
Identify Your Ideal Location
Do you enjoy your current neighborhood? If you do, don’t assume that you can’t afford to buy in the same area simply because rental rates may be rising. In many cases, owning a home can be more affordable than renting, potentially allowing you to consider areas previously thought to be beyond your reach.
Once you’ve identified your preferred locales, let us know your chosen zip codes and specific preferences. We’ll compile a list of suitable properties for your personal viewing.
Examine Your Finances
Before embarking on your homeownership journey, take a comprehensive look at your financial situation. Here are some key steps:
- Review your credit report and report any inaccuracies
- Calculate your debts
- Evaluate your savings and future saving capacity
Lenders consider your financial health when deciding on mortgage approval. Can you afford the mortgage payment and additional costs comfortably? Keeping a debt-to-income ratio of less than 40% is generally advisable, as it widens your opportunities.
Assemble Necessary Documents
While reviewing your finances, gather these important documents for potential lenders:
- W-2 and 1099 forms
- Monthly bank statements
- Asset statements
- 401(k), 403(b), mutual funds, stocks, bonds, and IRAs
- Last two tax returns
- Landlord reference
Choose the Right Lender
Securing a lender is a crucial step that should be undertaken early in the process. A lender can accurately determine what you can afford and offer valuable advice on improving your financial profile and selecting the best mortgage plan. Some lenders also offer specific incentives for first-time homebuyers.
If you need recommendations for lenders, we can provide you with a list. Give us a call at 734-761-3060, and we’ll provide you with a list of lenders that may suit your needs.
Time Your Purchase Perfectly
Even when transitioning to homeownership, remember to fulfill the terms of your current lease. If it requires a 30-day notice of non-renewal, try to time your purchase so that your lease ends around the time you close on your new home. If the timing doesn’t align, consider discussing a month-to-month rental option with your landlord.
Embrace the Excitement of Homeownership
Stepping into the role of a first-time homebuyer is a thrilling milestone, and we’re delighted to be part of your journey. If you’ve considered buying a condo or home, now is the time to act. Follow this guide and reach out to us for expert assistance in navigating the rewarding adventure of homeownership. Contact us today at info@condohotline.com or 734-761-3060.