
Buying Your First Home? It’s Okay to Feel Nervous

Buying your first home or condo is exciting, but let’s be real – it can also feel overwhelming. It’s a big step, and with that comes plenty of questions. Am I making the right decision? Can I really afford this right now? Will I be able to make ends meet if I have unexpected repairs? What if I lose my job?
Here’s the thing: every first-time homebuyer has these thoughts.
The homebuying process has always been a mix of excitement and nerves, and that’s completely normal. Here’s some information that can give you a bit of perspective, so you don’t have these concerns.
Focus on What You Can Control
Since homeownership is new to you, you’re probably feeling like it’s hard to know what to budget for. And that can be a bit scary. You’ll have the mortgage, home insurance, and maintenance to think about – maybe even lawn care or homeowner’s association (HOA) fees. It’s easy to let the dollar signs be overwhelming. As Zillow says:
“Buying a house is a big decision, and you might feel confused and indecisive as you assess your current financial situation and try to work through whether or not the timing is right. Making big life choices might come with some self-doubt, but crunching the numbers and thinking about what you want your life to look like will help guide you down the right path.”
The important thing is to focus on what you can control. By partnering with a local agent and a trusted lender, you can get a clear understanding of what you can borrow for your home loan, what your monthly payment would be, and how your mortgage rate can impact it. And since that payment will likely be your biggest recurring expense, the key is to make sure the number works for you.
Don’t Stress About Repairs
The maintenance and repairs? Those can be a little bit harder to anticipate. But don’t forget you’ll get an inspection during the homebuying process to give you a better look at the condition of your future house. And with your inspection report in hand, you’ll have a good idea of what needs work. This way, you can start saving up so that you’re ready if and when something breaks.
But even then, if this is something that’s still really nagging at you, talk to your agent about asking the seller to throw in a home warranty. Those can cover repairs for some of the bigger systems in the house, like the HVAC, if they break within a specific time frame. While this isn’t a huge expense for the seller, the likelihood of a seller agreeing to one depends on what’s happening in your local market and how competitive it is right now.
It’s Okay To Stretch – Just Not Too Far
And remember, chances are that money will be a little tight – at least at first. And that’s kind of to be expected. A lot of times when someone buys their first home, they cut down on things like shopping and eating out for a while until they get a better idea of how their expenses will shake out in the new home.
But if you’re crunching the numbers and you won’t have enough money left for things like gas, food, etc. – it’s a sign you’d be stretching yourself too far. The last thing you want is to take on a payment that’s too much to handle. But stretching a little? That’s different. That’s normal.
Your Job Will Probably Change – And That’s Okay
And don’t forget, you’ll likely earn more down the road, so that slight stretch now won’t seem so bad as time wears on. As you advance in your career, you’ll probably start to make more money too. So, as your paycheck grows, the payments will get easier. Renting is a short-term option – and it’s one you deserve to get out of. Buying a home is a long-term play.
And just in case you’re worried about what happens if you do lose your job, you should know there are options, like forbearance, designed to help you temporarily pause payments on your home loan due to hardship.
Bottom Line
Buying your first home or condo is a big decision, and it’s okay to feel a little nervous about it. But if you’re financially ready, don’t let fear keep you from moving forward. These emotions are normal, and great agents help their buyers get through them.
What makes you nervous when you think about buying your first home?
Let’s connect so you have an expert on your side to explain everything along the way. From finding the perfect community for your needs to guiding you through the process, we’re here to help! Contact us today at The Bouma Group, Realtors at 734-761-3060 or info@condohotline.com.
Why a Condo May Be a Great Option for Your First Home
An Ann Arbor Condo is a Great First Home
Having a hard time finding a first home that’s right for you and your wallet, especially in Ann Arbor? Well, here’s a tip – think about condominiums, or condos for short.
They’re usually smaller than single-family homes, but that’s exactly why they can be easier on your budget. According to the latest data from the National Association of Realtors (NAR), condos are typically less expensive than single-family homes (see graph below):
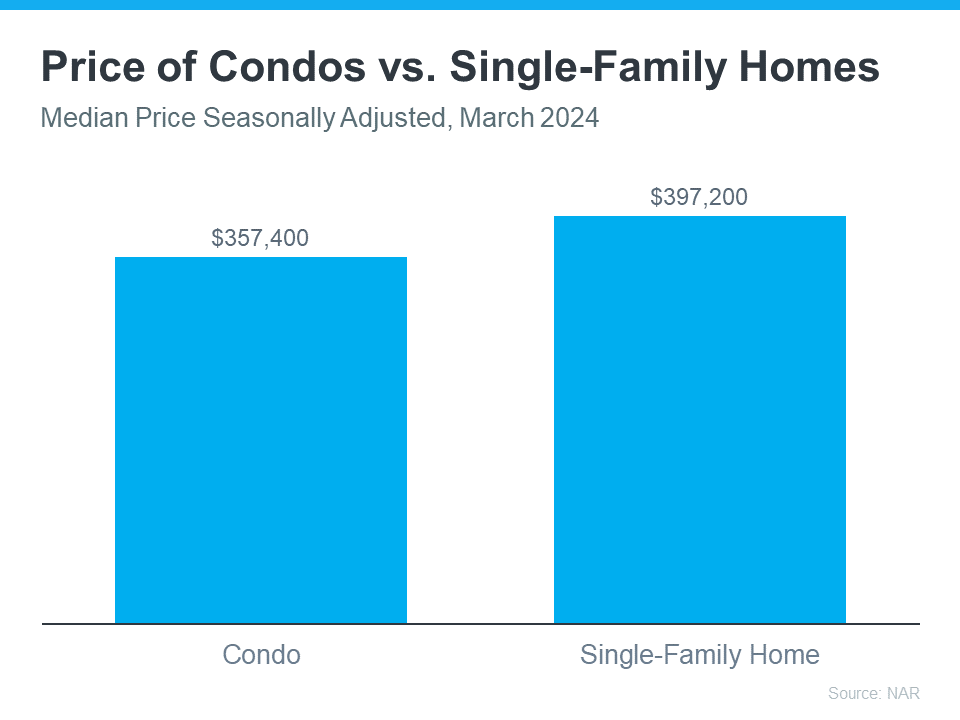
So, if you’re comfortable with a smaller space and want to buy your first home this year, adding condos to your search might be easier on your wallet.
Besides giving you more options for your home search and maybe fitting your budget better, living in a condo has many other perks. According to Rocket Mortgage:
“From community living to walkable urban areas, condos are great options for first-time home buyers and people looking to enjoy homeownership without extensive upkeep.”
Benefits of Condo Living
Let’s dive into a few of the draws of condos for first-time buyers from Bankrate:
- They require less maintenance. Condos are great if you want to own your place but don’t want to mow the lawn, shovel snow, or fix the roof. Your real estate agent can help explain any associated fees and details for the condos you’re interested in.
- They allow you to start building equity. When you buy a condo, you build equity and your net worth as you make your mortgage payments and as your condo’s value goes up over time.
- They often come with added amenities. Your condo might have access to amenities like a pool, dog park, or parking. And the best part? You don’t have to take care of any of them.
- They provide you with a sense of community. Buying a condo means you’ll be living close to other people, which is nice if you enjoy having neighbors around and making friends. Many condo communities hold fun events like barbecues and holiday parties for everyone to enjoy.
Remember, your first home doesn’t have to be the one you stay in forever. The important thing is to get your foot in the door as a homeowner so you can start to gain home equity. Later on, that equity can help you buy another place if you need something different.
Ultimately, owning and living in a condo is a lifestyle choice. And if it’s one that appeals to you, they could provide the added options you need in today’s market.
Bottom Line
It might be a good idea to think about condos in your home search. If you’re ready to see what’s out there, let’s get in touch today. Contact us at The Bouma Group, Realtors at 734-761-3060 or info@condohotline.com.
How to Stop Renting and Become a First-Time Homebuyer
The First-Time Homebuyer Plan
Key Takeaways:
- Renting doesn’t help build a future
- Homeownership can be accessible
- Contact your trusted local agents for more on being a first-time homebuyer
Many renters discover a universal truth—renting can often feel like it lacks long-term benefits. However, each monthly rent payment potentially reduces a landlord’s mortgage while increasing their home equity. This revelation may inspire some to transition from renters to first-time homebuyers. If you’re contemplating this life-changing decision, now is an opportune time to consider buying a home.
The appeal of escaping ever-increasing rental rates motivates many first-time condo buyers. Ready to join this progressive march towards homeownership? We are here to guide you through each step of the process. Here’s a simple guide to get you started on your homeownership journey.
Identify Your Ideal Location
Do you enjoy your current neighborhood? If you do, don’t assume that you can’t afford to buy in the same area simply because rental rates may be rising. In many cases, owning a home can be more affordable than renting, potentially allowing you to consider areas previously thought to be beyond your reach.
Once you’ve identified your preferred locales, let us know your chosen zip codes and specific preferences. We’ll compile a list of suitable properties for your personal viewing.
Examine Your Finances
Before embarking on your homeownership journey, take a comprehensive look at your financial situation. Here are some key steps:
- Review your credit report and report any inaccuracies
- Calculate your debts
- Evaluate your savings and future saving capacity
Lenders consider your financial health when deciding on mortgage approval. Can you afford the mortgage payment and additional costs comfortably? Keeping a debt-to-income ratio of less than 40% is generally advisable, as it widens your opportunities.
Assemble Necessary Documents
While reviewing your finances, gather these important documents for potential lenders:
- W-2 and 1099 forms
- Monthly bank statements
- Asset statements
- 401(k), 403(b), mutual funds, stocks, bonds, and IRAs
- Last two tax returns
- Landlord reference
Choose the Right Lender
Securing a lender is a crucial step that should be undertaken early in the process. A lender can accurately determine what you can afford and offer valuable advice on improving your financial profile and selecting the best mortgage plan. Some lenders also offer specific incentives for first-time homebuyers.
If you need recommendations for lenders, we can provide you with a list. Give us a call at 734-761-3060, and we’ll provide you with a list of lenders that may suit your needs.
Time Your Purchase Perfectly
Even when transitioning to homeownership, remember to fulfill the terms of your current lease. If it requires a 30-day notice of non-renewal, try to time your purchase so that your lease ends around the time you close on your new home. If the timing doesn’t align, consider discussing a month-to-month rental option with your landlord.
Embrace the Excitement of Homeownership
Stepping into the role of a first-time homebuyer is a thrilling milestone, and we’re delighted to be part of your journey. If you’ve considered buying a condo or home, now is the time to act. Follow this guide and reach out to us for expert assistance in navigating the rewarding adventure of homeownership. Contact us today at info@condohotline.com or 734-761-3060.
More Young People Are Buying Condos and Homes
There’s a common misconception that younger generations aren’t interested in homeownership. Many people point to the fact that millennials put off purchasing their first home as a reason for this belief.
Odeta Kushi, Deputy Chief Economist for First American, explains why millennials have put off certain milestones linked to homeownership. Those delays led to their homeownership rates trailing slightly behind older generations:
“Historically, millennials have delayed the critical lifestyle choices often linked to buying a first home, including getting married and having children, in order to further their education. This is clear in cross-generational comparisons of homeownership rates which show millennials lagging their generational predecessors.”
So, it’s partially true that some millennials have waited on homeownership to focus on other things in their lives – and that’s impacting certain housing market trends.
Data from the National Association of Realtors (NAR) indicates the average age of a first-time homebuyer is higher today than it’s been over the past 40 years. As the graph below shows, homebuyers today are purchasing their first home an average of 4 years later than people in the 1980s and early 1990s: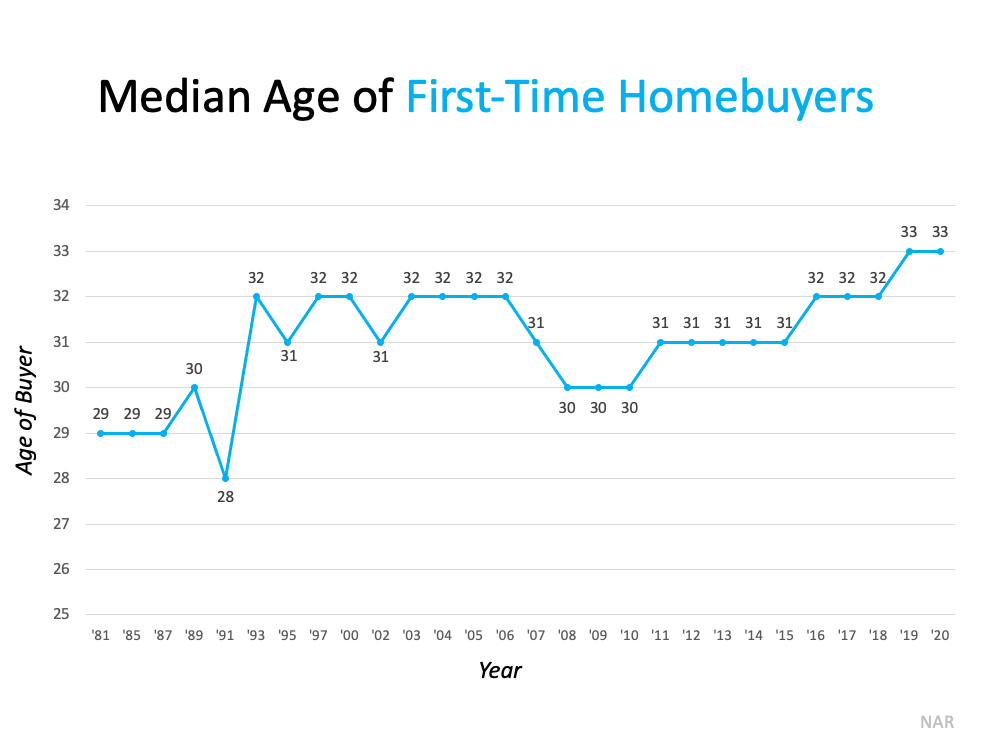
But just because millennials are hitting certain milestones later in life doesn’t mean they’re not interested in becoming homeowners. The recent U.S. Census reveals a significant increase in homeownership rates for millennials and other young homebuyers.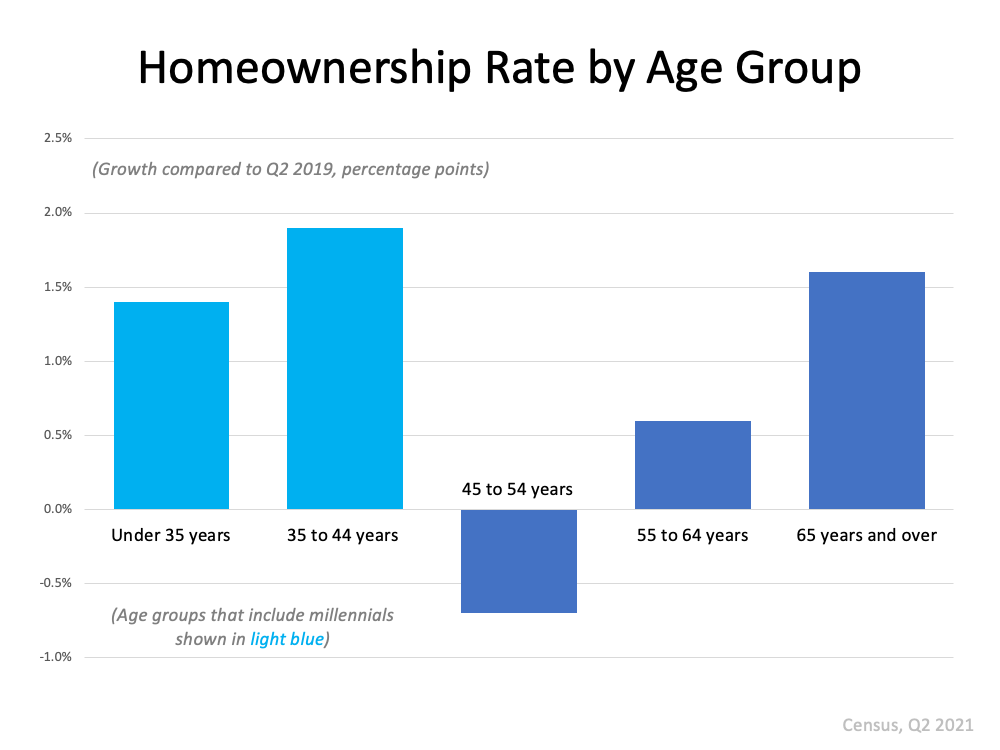
As the graph above shows, millennials are entering the market in full force, and their share of the market is growing. Based on the data, the belief that younger generations don’t want to buy homes is a misconception. In fact, the recent Capital Market Outlook report from Merrill-Lynch further drives home this point, as it specifically mentions the effect millennials are having on demand:
“Demand is very strong because the biggest demographic cohort in history is moving through the household-formation and peak home-buying stages of its life cycle.”
Kushi is following the trend of millennial homeownership and puts it more simply, saying:
“. . . it’s clear that younger households (millennials!) are driving homeownership growth.”
As the largest generation, millennials’ impact on the market is growing as more and more people from that generation reach homebuying age – and Generation Z isn’t far behind, either. That means younger generations will likely continue to drive demand in the housing market for years to come.
Bottom Line
If you’re a member of a younger generation and interested in purchasing a home, you’re not alone. Many of your peers are on their path to homeownership, too. Let’s connect today and discuss what you can do to accomplish your homebuying goals. 734-761-3060 or info@condohotline.com