
Don’t Miss Out on the Growing Number of Down Payment Assistance Programs
With rising home prices and volatile mortgage rates, it’s important you know about every resource that could help make buying a condo or home possible. One thing you’ll want to be aware of is how much the number of down payment assistance (DPA) programs has grown lately.
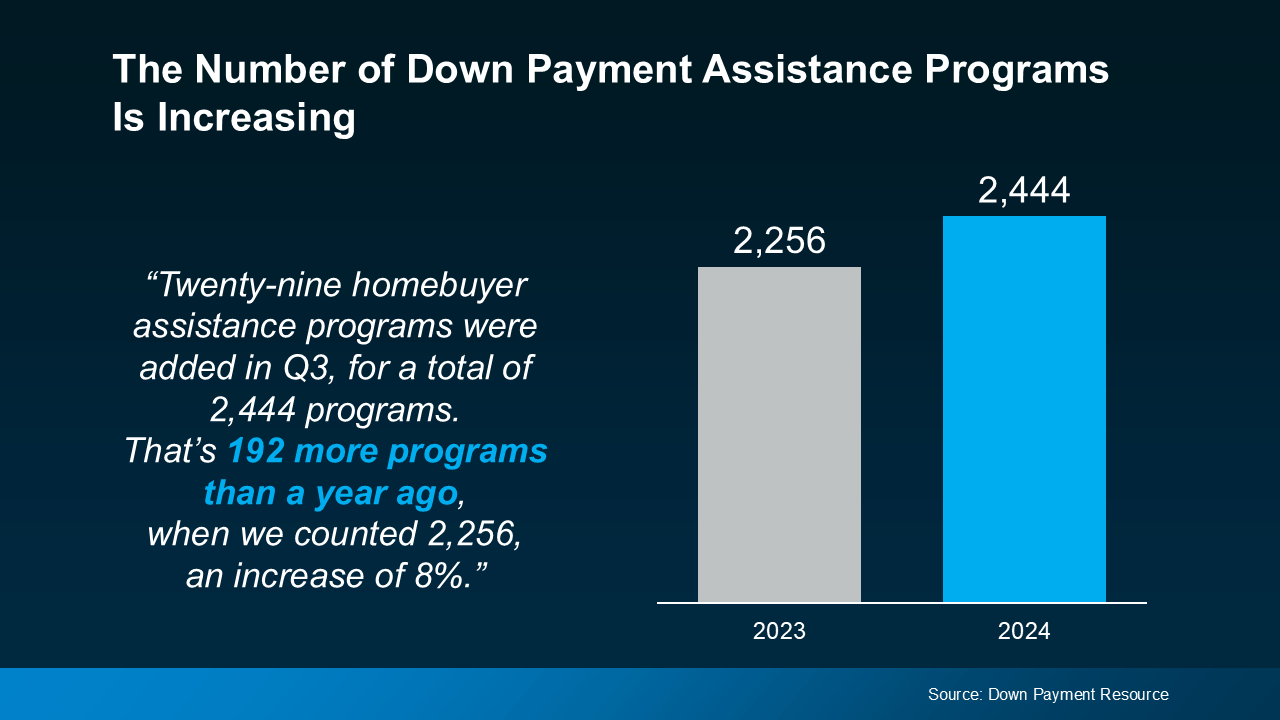
Take a look at the graph below to see how many new programs have been added in the last year, according to data from Down Payment Resource:
More Programs, More Opportunities for You
So, what does this increase mean for you? With more programs available, there’s a higher likelihood that one of them could help you reach your homeownership goals.
And these programs aren’t small-scale help either – the benefits can go a long way toward covering a chunk of your costs. As Rob Chrane, Founder and CEO of Down Payment Resource, shares:
“We are pleased to see a growing number of these programs, and think they are becoming a targeted way to help first-time and first-generation homebuyers struggling to save for a down payment get into a home they can afford. Our data shows the average DPA benefit is roughly $17,000. That can be a nice jump-start for saving for a down payment and other costs of homeownership.”
Imagine being able to qualify for $17,000 toward your down payment. That’s a big boost, especially if you’re looking to buy your first place. With that level of help, buying a condo or home may be more within reach than you think.
But it’s worth calling out that the growth in DPA options isn’t just focused on first-time and first-generation buyers. Many of the new programs are also aimed at supporting affordable housing initiatives, which include manufactured and multi-family homes. This means that more people, and a wider variety of home types, can qualify for down payment assistance. This will make it easier for you to find an option that fits your needs.
Talk to a Real Estate Expert About What’s Available for You
With so many DPA programs out there, you need to make sure you’re finding the right one for you. That’s why it’s key to lean on your real estate and lending professionals for guidance. The Mortgage Reports says:
“The best way to find down payment assistance programs for which you qualify is to speak with your loan officer or broker. They should know about local grants and loan programs that can help you out.”
A great loan officer will know what’s available in your area and can point you toward programs that align with your goals. We work with some fantastic lenders and can help match you with the perfect one.
Bottom Line
With more down payment assistance programs than ever before, now’s a great time to explore how these options can help on your homebuying journey. Let’s work together to make sure you’ve got a team of expert advisors in place. Contact us today at The Bouma Group, Realtors at 734-761-3060 or info@bouma.com.
Start your search now!
How to Stop Renting and Become a First-Time Homebuyer
The First-Time Homebuyer Plan
Key Takeaways:
- Renting doesn’t help build a future
- Homeownership can be accessible
- Contact your trusted local agents for more on being a first-time homebuyer
Many renters discover a universal truth—renting can often feel like it lacks long-term benefits. However, each monthly rent payment potentially reduces a landlord’s mortgage while increasing their home equity. This revelation may inspire some to transition from renters to first-time homebuyers. If you’re contemplating this life-changing decision, now is an opportune time to consider buying a home.
The appeal of escaping ever-increasing rental rates motivates many first-time condo buyers. Ready to join this progressive march towards homeownership? We are here to guide you through each step of the process. Here’s a simple guide to get you started on your homeownership journey.
Identify Your Ideal Location
Do you enjoy your current neighborhood? If you do, don’t assume that you can’t afford to buy in the same area simply because rental rates may be rising. In many cases, owning a home can be more affordable than renting, potentially allowing you to consider areas previously thought to be beyond your reach.
Once you’ve identified your preferred locales, let us know your chosen zip codes and specific preferences. We’ll compile a list of suitable properties for your personal viewing.
Examine Your Finances
Before embarking on your homeownership journey, take a comprehensive look at your financial situation. Here are some key steps:
- Review your credit report and report any inaccuracies
- Calculate your debts
- Evaluate your savings and future saving capacity
Lenders consider your financial health when deciding on mortgage approval. Can you afford the mortgage payment and additional costs comfortably? Keeping a debt-to-income ratio of less than 40% is generally advisable, as it widens your opportunities.
Assemble Necessary Documents
While reviewing your finances, gather these important documents for potential lenders:
- W-2 and 1099 forms
- Monthly bank statements
- Asset statements
- 401(k), 403(b), mutual funds, stocks, bonds, and IRAs
- Last two tax returns
- Landlord reference
Choose the Right Lender
Securing a lender is a crucial step that should be undertaken early in the process. A lender can accurately determine what you can afford and offer valuable advice on improving your financial profile and selecting the best mortgage plan. Some lenders also offer specific incentives for first-time homebuyers.
If you need recommendations for lenders, we can provide you with a list. Give us a call at 734-761-3060, and we’ll provide you with a list of lenders that may suit your needs.
Time Your Purchase Perfectly
Even when transitioning to homeownership, remember to fulfill the terms of your current lease. If it requires a 30-day notice of non-renewal, try to time your purchase so that your lease ends around the time you close on your new home. If the timing doesn’t align, consider discussing a month-to-month rental option with your landlord.
Embrace the Excitement of Homeownership
Stepping into the role of a first-time homebuyer is a thrilling milestone, and we’re delighted to be part of your journey. If you’ve considered buying a condo or home, now is the time to act. Follow this guide and reach out to us for expert assistance in navigating the rewarding adventure of homeownership. Contact us today at info@condohotline.com or 734-761-3060.
Pre-Approval in 2023: What You Need To Know
Pre-Approval in 2023: What You Need To Know
One of the first steps in your condo or home-buying journey is getting pre-approved. To understand why it’s such an important step, you need to understand what pre-approval is and what it does for you. Business Insider explains:
“In a preapproval [sic], the lender tells you which types of loans you may be eligible to take out, how much you may be approved to borrow, and what your rate could be.”
Basically, pre-approval gives you critical information about the buying process that’ll help you understand your options and what you may be able to borrow.
How does it work? As part of the pre-approval process, a lender will look at your finances to determine what they’d be willing to loan you. From there, your lender will give you a pre-approval letter to help you understand how much money you can borrow. That can make it easier when you set out to search for condos or homes because you’ll know your overall numbers. And with higher mortgage rates impacting affordability for many buyers today, a solid understanding of your numbers is even more important.
Pre-Approval Helps Show You’re a Serious Buyer
Another added benefit is pre-approval can help a seller feel more confident in your offer because it shows you’re serious about buying their property. A recent article from Forbes notes:
“From the seller’s perspective, a preapproval [sic] letter from a reputable local lender often can make the difference between accepting and rejecting an offer.”
This goes to show, even though you may not face the intense bidding wars you saw if you tried to buy during the pandemic, pre-approval is still an important part of making a strong offer. In fact, Christy Bieber, Personal Finance Writer at The Motley Fool explains it may be the most important part of making an offer:
“Pre-approval maximizes the chances you’ll be able to actually close the deal – and sellers want to see that.
The fact that a pre-approval gives you a better chance of getting your offer accepted is undoubtedly the most important reason to complete this step . . .”
Bottom Line
Getting pre-approved is an important first step toward buying a condo or home. It lets you know what you can borrow and shows sellers you’re serious about purchasing their condo or home. Connect with a local real estate professional and a trusted lender so you have the tools you need to purchase in today’s market. Contact us at 734-761-3060 or info@condohotline.com to discuss your path to ownership!