
What Home Buyers Need to Know About Credit Scores
Credit Scores are a Big Piece of the Lending Puzzle
If you’re thinking about buying a condo or home, you should know your credit score’s a critical piece of the puzzle when it comes to qualifying for a loan. Lenders review your credit to assess your ability to make payments on time, pay back debts, and more. It’s also a factor that helps determine your mortgage rate. An article from Bankrate explains:
“Your credit score is one of the most important factors lenders consider when you apply for a mortgage. Not just to qualify for the loan itself, but for the conditions: Typically, the higher your score, the lower the interest rates and better terms you’ll qualify for.”
This means your credit score may feel even more important to your homebuying plans right now since mortgage rates are a key factor in affordability, especially today. According to the Federal Reserve Bank of New York, the median credit score in the U.S. for those taking out a mortgage is 765. But, that doesn’t mean your credit score has to be perfect. An article from Business Insider explains generally how your FICO score range can make an impact:
“. . . you don’t need a perfect credit score to buy a house. . . . Aiming to get your credit score in the ‘Good’ range (670 to 739) would be a great start towards qualifying for a mortgage. But if you’re wanting to qualify for the lowest rates, try to get your score within the ‘Very Good’ range (740 to 799).”
Working with a trusted lender’s the best way to get more information on how your credit score could factor into your home loan and the mortgage rate you’re able to get. As FICO says:
“While many lenders use credit scores like FICO Scores to help them make lending decisions, each lender has its own strategy, including the level of risk it finds acceptable. There is no single “cutoff score” used by all lenders and there are many additional factors that lenders may use to determine your actual interest rates.”
If you’re looking for ways to improve your score, Experian highlights some things you may want to focus on:
- Your Payment History: Late payments can have a negative impact by dropping your score. Focus on making payments on time and paying any existing late charges quickly.
- Your Debt Amount (relative to your credit limits): When it comes to your available credit amount, the less you’re using, the better. Focus on keeping this number as low as possible.
- Credit Applications: If you’re looking to buy, don’t apply for other credit. When you apply for new credit, it could result in a hard inquiry on your credit that drops your score.
When you’re ready to start the homebuying process, a lender will be able to assess which range your score falls in and tell you more about the specifics for each loan type.
Bottom Line
With affordability challenges today, prioritizing ways you can have a positive impact on your credit score could help you get a better mortgage rate. To learn more, let’s connect today at 734-761-3060 or info@condohotline.com.
Looking for a Place To Call Home? Consider a Condominium.
It’s no secret that one of the top stories in today’s real estate market is low housing supply and high buyer demand. If you’re a first-time buyer looking for a starter home or are someone who’s interested in downsizing, it may be worth considering a condominium (condo) as a worthwhile option.
In fact, trends indicate condos are gaining popularity among buyers. In the latest Existing Homes Sales Report from the National Association of Realtors (NAR), the data shows condo sales rising throughout the first half of this year (see graph below):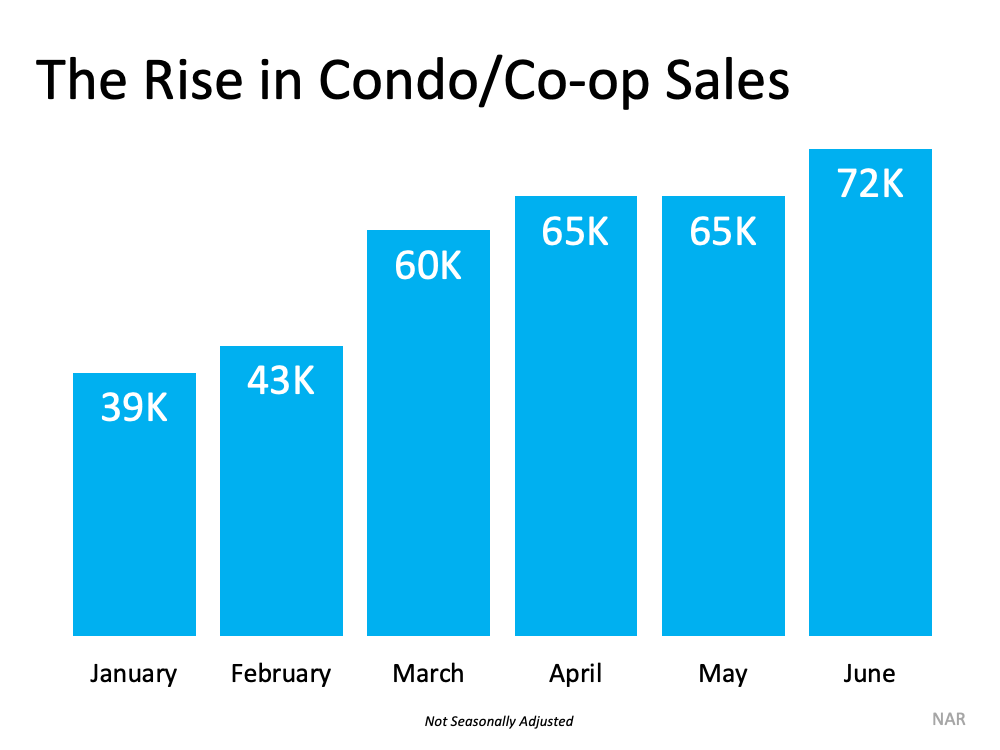
There are a few reasons more and more people are opting to buy condos – the benefits of condo life can be quite compelling. Let’s explore the main perks to find out if a condo is a good fit for you.
Affordability
According to the NAR report, the median sales price of a condo is roughly $59,000 less than the median price of a single-family detached home (see graph below). This makes condos a great option for first-time homebuyers, those with limited down payment savings, or those looking to save money by downsizing.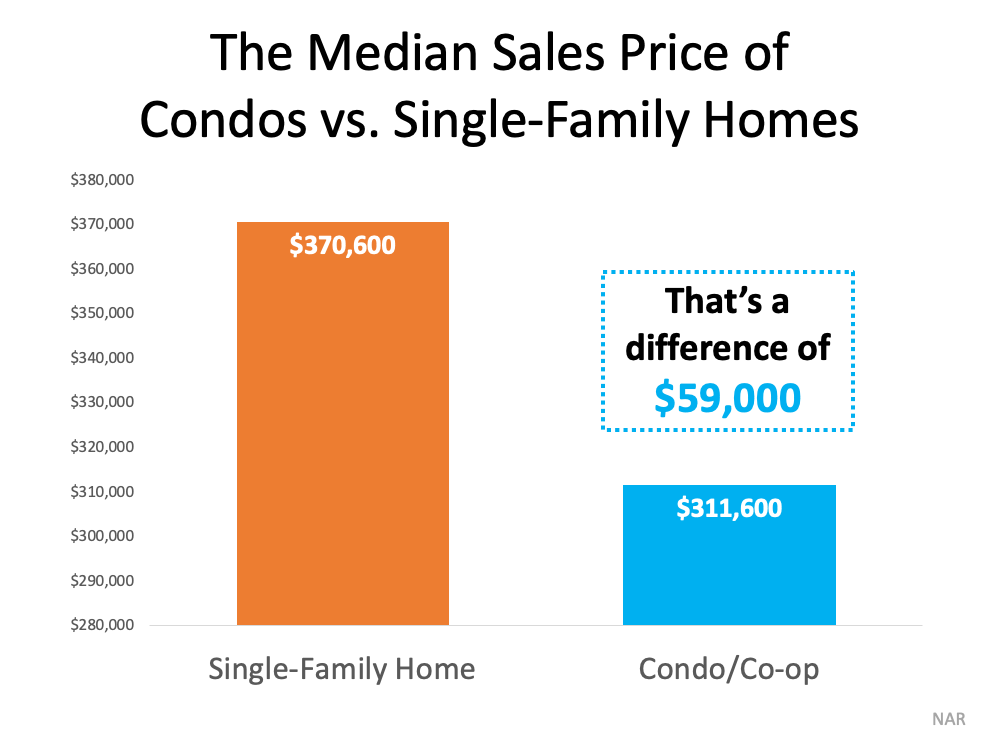
Maintenance
A recent article from BankRate adds low maintenance as another perk of a condo lifestyle. Generally, exterior maintenance for condos is handled by a Homeowner’s Association (HOA). This can include things like landscaping and upholding a certain standard of cleanliness and condition for walkways, siding, and roofs. If you’re looking for a lower-maintenance option or see the appeal in being hands-off with upkeep, condos may be a good choice for you. With exterior maintenance off your plate, you’ll have more time for yourself and your hobbies.
Amenities
You can use that free time to enjoy some of the value-adding features your condo community may have, which could include dog parks, pools, a rentable clubhouse and grilling area for events, and more. If being able to host or attend community social outings is important to you, condos may give you more opportunities to enjoy the company of your neighbors. As a bonus, some condos even have gyms and on-site security teams.
Ultimately, the choice is yours. Condos are great options that often come with various features and benefits that may be important for your lifestyle. Fannie Mae sums up the appeal nicely:
“Condominiums, or condos, can be great alternatives to detached homes. City dwellers, singles, couples, seniors, and many others may find condos that suit their needs and budgets. Others may simply prefer low-maintenance living. Buyers who feel ‘priced out’ of homes may discover condos offer an affordable homeownership alternative.”
Bottom Line
If you’re looking for a home, it may be time to consider a condo as an option. Let’s connect today at 734-761-3060 or info@condohotline.com to explore if one would be a good fit for your homeownership needs.