
Would You Let $80 a Month Hold You Back from Buying a Condo or Home?
Should $80 a Month Stop You From Investing?
A lot of buyers are stuck in “wait and see” mode right now. They’re watching rates hover a little above 6% and thinking, I’ll buy once they hit the 5s. Because who doesn’t want a better rate?
But here’s the thing: that 5.99% number might not save you as much as you think.
Affordability is still a challenge. There’s no question about that. But the market has given savvy buyers a head start. Mortgage rates have already come down over the past few months. And the drop we’ve seen saves you more than you’d think.
How Much You’ve Already Saved, Without Realizing It
Let’s put some real numbers to it. Rates peaked for the year in May when they inched above 7%. But since then, they’ve been slowly declining. Now, they’re sitting in the low 6s. And while that may not sound like a big deal, that change translates to real dollars.
According to data coming out of Redfin, the typical monthly payment on a $400,000 home is already down almost $400 since May.
That means if you’re buying a home now, you’re saving hundreds of dollars every month compared to what you would have been able to get earlier this spring. That’s real money that makes a real difference for buyers who paused their plans because they thought homeownership was out of reach.
And while it may be tempting to wait even longer to see bigger savings, that’s a gamble that could cost you. Here’s why.
Where Experts Say Rates Are Headed
For starters, most experts say mortgage rates are likely to stay pretty much where we are today throughout 2026. So, there’s no guarantee we’ll see a rate much lower than what we have now. Only one expert forecaster is saying rates could fall into the upper 5s next year (see graph below):
 And even if rates do dip below 6%, the extra savings you’re holding out for won’t move the needle as much as you might expect.
The Real Math Behind a 5.99% Rate
Let’s break it down. If rates come down to 5.99% from where they’ve been lately that’s a difference of only about $80 a month on an average priced home – give or take a bit based on your price point and the rate your lender quotes you (see chart below):
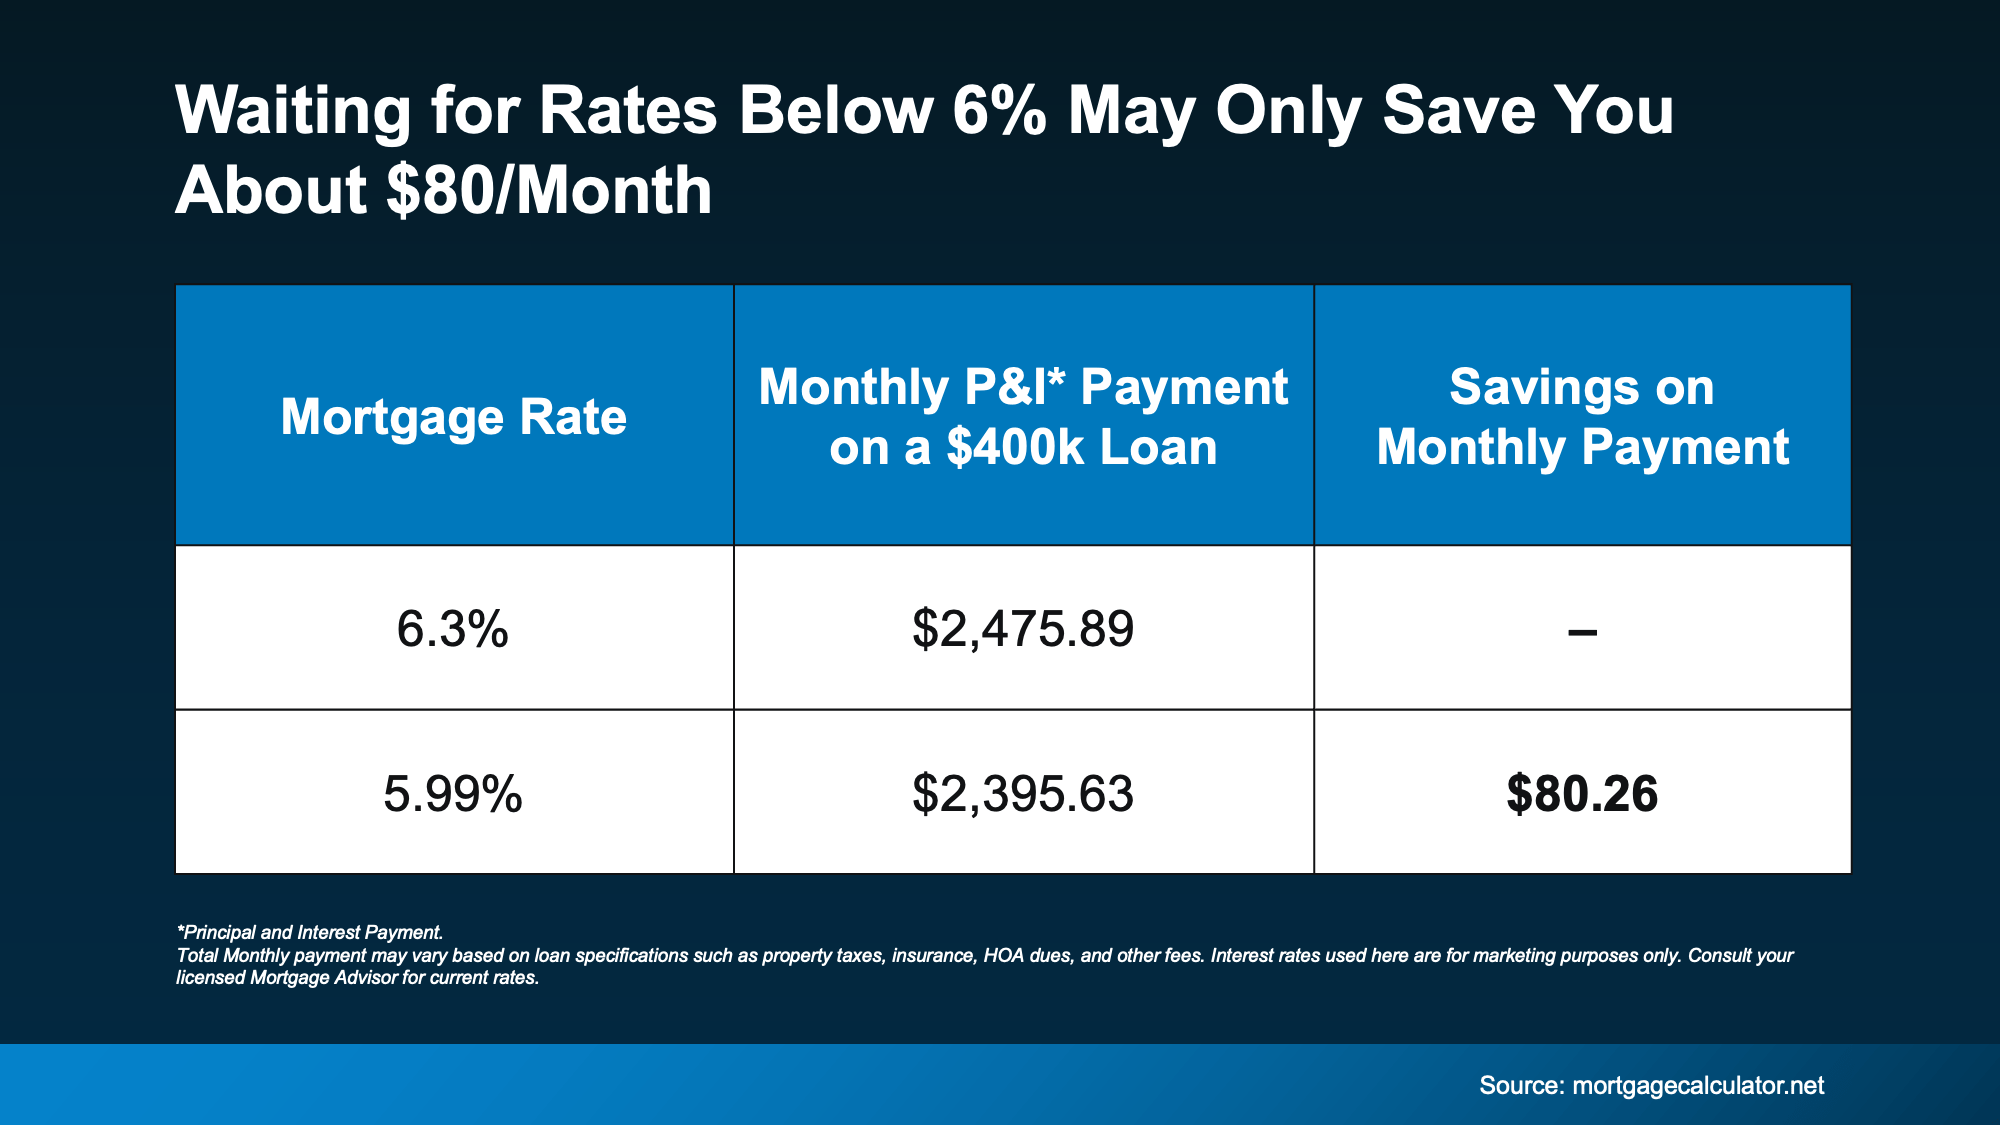 Eighty dollars. That’s it. And for the typical family, that’s about one dinner out (or one dinner in, if you have it delivered). That’s not enough to change the game for most buyers. But the savings of nearly $400 we already have compared to when you paused your search in the spring? That might be.
So, the question to ask yourself is this:
Is an extra $80 savings really worth the wait?
Because while you’re holding out for that small dip, the bigger opportunity might be slipping away.
When Rates Fall, Competition Follows
Right now, you have more homes to choose from, sellers who are ready to negotiate to get a deal done, and fewer buyers to compete with. But once rates fall below 6%, buyer mindsets will shift and all of that will change.
The National Association of Realtors (NAR) reports that if rates hit 6%, about 5.5 million more households will be able to afford the median-priced home. Even if only a small fraction of them decide to buy, that could mean hundreds of thousands of buyers getting back into the market.
That creates more competition for you, which would push home prices even higher – maybe high enough to cancel out the extra savings you waited for.
So, if you’re waiting for rates below 6%, just keep in mind… that extra $80 may not be worth it in the grand scheme of things.
Bottom Line
You don’t have to wait for 5.99%. You have the chance to move (and save) right now. So, ask yourself: Would you let $80 hold you back from buying a condo or home?
If you find a home you love and the math makes sense, getting ahead may be the best strategy. Let’s run your numbers so you can see what you’re working with in our market.
Why Ann Arbor Condos Are Experiencing Price Reductions this Spring
Price Reductions for Ann Arbor Condos
If you’re following the Ann Arbor housing market, you’ve likely noticed a curious trend this Spring—price reductions on condos are becoming more common. For homebuyers and sellers alike, this shift raises a lot of questions. Why are prices being lowered? What does it say about the market? And most importantly, how should you respond, whether you’re buying or selling?
This blog will break down the key reasons behind these price adjustments, the economic factors at play, and what this market trend means for both buyers and sellers. We’ll also share tips for navigating these changes.
What’s Causing the Price Drops?
Several factors are driving the recent wave of condo price reductions in Ann Arbor. While changes like this are rarely the result of one issue alone, the following may help explain the bigger picture.
1. Shifting Market Conditions
Over the past year, the real estate market in the U.S. has cooled after a frenzied post-pandemic housing boom. Ann Arbor, like many cities, is experiencing the effects of this market recalibration. Gone are the days when sellers could list their properties at inflated prices and expect competing offers within hours. Today, homes—including condos—are sitting on the market longer, forcing sellers to reconsider their pricing strategies.
2. Economic Influences
National and local economic factors also play a critical role. As of June 2025, interest rates remain elevated compared to their historical lows. Higher mortgage rates directly impact affordability for buyers. With borrowing costs rising, many prospective buyers are scaling down their budgets or opting to rent instead. This ultimately reduces demand for condos, putting downward pressure on prices.
Additionally, uncertainties in the broader economy, such as concerns about inflation or possible recessionary trends, may be making buyers more cautious. Economic uncertainty often translates to softer real estate markets.
3. Increase in Inventory
Another part of the equation is an increase in condo inventory. Over the last few years, Ann Arbor has seen a rise in new condo developments catering to its growing population of students, professionals, and retirees. In May 2025, Ann Arbor saw a 28% increase in listings compared with May 2024. While this increase in supply is great for buyers, it means sellers now face more competition. When buyers have more options, sellers must be willing to negotiate or lower their asking prices to make their listings stand out.
4. Potential Overpricing
Some sellers in Ann Arbor may have initially priced their condos too high. This might be due to lingering expectations from the seller-friendly market of recent years or a misunderstanding of current conditions. When a home sits on the market without generating enough interest, sellers often opt for price reductions to attract a new buyer pool, get offers, and avoid prolonged market exposure.
The Impact on Buyers and Sellers
Price reductions affect buyers and sellers in different ways, and understanding these impacts can help you make informed decisions.
For Buyers
Price reductions present an opportunity, especially for those who have been struggling to break into the competitive housing market. Here’s what buyers can expect:
- More Negotiating Power: Buyers may find they have an edge when making offers, as sellers are more motivated to close deals.
- Wider Choices: Since inventory levels are higher, buyers can take their time to explore more options and make decisions that align with both their preferences and budgets.
- Affordability Considerations: Although sellers are reducing prices, higher mortgage rates may still make monthly payments a challenge. Ensure you run the numbers carefully before committing.
For Sellers
If you’re selling your condo in Ann Arbor, this environment can feel more challenging. However, understanding the reality of today’s market can help you adjust your approach:
- Pricing Strategically: Setting a realistic price from the beginning is critical to attracting buyers. Consider consulting with a local real estate professional who understands current market trends.
- Considering Pre-Listing Improvements: Enhancing your condo’s appeal through small upgrades or staging can help it sell faster, even in a cooling market.
- Being Patient and Flexible: Be prepared for the possibility of longer listing times and the need to negotiate with buyers.
Navigating the Current Market
Whether you’re a prospective buyer or a seller, here are some tips for navigating today’s Ann Arbor condo market:
Advice for Buyers
- Know Your Budget: With changing market conditions and higher mortgage rates, determine what you can comfortably afford before starting your search.
- Be Prepared to Compromise: While inventory is higher, the perfect property may still come at a premium. Know your non-negotiables and be willing to compromise on other aspects.
- Time Your Offers Strategically: Staying informed about price reductions and market dynamics can help you make well-timed offers, potentially securing a great deal.
Advice for Sellers
- Work with a Pro: An experienced real estate agent familiar with Ann Arbor’s unique market can provide pricing strategies that help your condo remain competitive.
- Focus on Presentation: Ensure your condo makes a strong first impression with prospective buyers. This could include staging, professional photos, or hosting open houses.
- Adjust Quickly: If your condo isn’t generating interest after a couple of weeks, reevaluate your strategy. This might mean a price adjustment or additional marketing efforts. Typically, if you’ve had 10-12 showings and no offers, you’re 4-6% over list price, and if you’ve had no showings, you’re 10% over.
Looking Ahead
The Ann Arbor market is undergoing a period of recalibration, which may continue through 2025. While this isn’t ideal for every seller, it’s a necessary part of balancing supply and demand, paving the way for more sustainable market conditions in the long term. If you’re planning to buy or sell a condo, staying informed and adapting to these changes will help you make the most of today’s real estate landscape.
Whether you’re a first-time homebuyer or a seasoned property owner, preparing for these shifts is key. Taking proactive steps now can lead to better opportunities in the months ahead. Contact us today at The Bouma Group, Realtors at 734-761-3060 or info@condohotline.com and let’s get your condo priced correctly to sell!
Buyers, start your Ann Arbor Condo search here!
Understanding Today’s Mortgage Rates: Is 3% Coming Back?
Are 3% Mortgage Rates Coming Back?
Many buyers are holding off on their plans these days, hoping that mortgage rates will drop – perhaps even back to the historic low of 3% from a few years ago. But here’s the thing: those rates were never meant to last. They were a short-term response to a very specific moment in time. And as the market finds its footing again, it’s time to reset expectations.
Back in 2020 and 2021, 3% mortgage rates gave buyers a serious boost: more affordability, more buying power, and more opportunity. But those rates were a result of emergency economic policies during the height of a global pandemic. Now that the economy is in a different place, we’re seeing mortgage rates in the high 6% to low 7% range.
And while experts currently project a slight easing in the months ahead, most industry leaders agree: rates are not going back to 3%.
Instead, many forecasts suggest mortgage rates will settle in the mid-6% range by the end of the year, pending any major economic shifts. As Kara Ng, Senior Economist at Zillow, says:
“While Zillow expects mortgage rates to end the year near mid-6%, barring any unforeseen shocks, that path might be bumpy.”
What Buyers Should Know
Basically, waiting for 3% rates might mean waiting longer than you’d expect – and missing out along the way. Instead of putting off homebuying indefinitely, make a plan to get there and focus on what you can control: your budget, your credit, and working with a trusted professional who can explain exactly what’s happening in the current market – and how to navigate it.
Your local real estate agent and a trusted lender make all the difference in this process. The experts have insights into down payment assistance programs, alternative financing options, negotiation strategies, and overall – the experience you need on your side to understand creative ways that will make your plans work.
And here’s the biggest thing to keep in mind. Since rates are projected to ease slightly later this year, if that happens, it could bring some more buyers back into the market. Acting now gives you a head start, especially with more homes on the market than we’ve seen in years.
Think about it: if mortgage rates do come down, what do you think everyone else is going to do? That’s right – they’ll jump back in too.
Getting ahead of that rush could put you in a stronger position to find the right home with less competition. Realtor.com sums it up well:
“Staying out of the market in hopes of a rate drop that never comes can lead to missed opportunities . . . Rising home prices, rent increases, and inflation might outpace any future savings on interest. And if rates do fall sharply again, buyers could face an entirely different challenge: surging competition.”
Bottom Line
Those 3% rates everyone remembers from a few years ago were the exception, not the rule.
Now that they’re settling into new territory, it’s a good time to adjust your expectations and learn more about where things are heading as this market shifts.
A local real estate agent and a trusted lender will be your best resources, always keeping you up-to-date and informed, so you can make sense of your options and build a game plan that works for you. See Ann Arbor Condo complexes here and start dreaming about your new home! Contact The Bouma Group today at 734-761-3060 or info@condohotline.com.
Buying Your First Home? It’s Okay to Feel Nervous

Buying your first home or condo is exciting, but let’s be real – it can also feel overwhelming. It’s a big step, and with that comes plenty of questions. Am I making the right decision? Can I really afford this right now? Will I be able to make ends meet if I have unexpected repairs? What if I lose my job?
Here’s the thing: every first-time homebuyer has these thoughts.
The homebuying process has always been a mix of excitement and nerves, and that’s completely normal. Here’s some information that can give you a bit of perspective, so you don’t have these concerns.
Focus on What You Can Control
Since homeownership is new to you, you’re probably feeling like it’s hard to know what to budget for. And that can be a bit scary. You’ll have the mortgage, home insurance, and maintenance to think about – maybe even lawn care or homeowner’s association (HOA) fees. It’s easy to let the dollar signs be overwhelming. As Zillow says:
“Buying a house is a big decision, and you might feel confused and indecisive as you assess your current financial situation and try to work through whether or not the timing is right. Making big life choices might come with some self-doubt, but crunching the numbers and thinking about what you want your life to look like will help guide you down the right path.”
The important thing is to focus on what you can control. By partnering with a local agent and a trusted lender, you can get a clear understanding of what you can borrow for your home loan, what your monthly payment would be, and how your mortgage rate can impact it. And since that payment will likely be your biggest recurring expense, the key is to make sure the number works for you.
Don’t Stress About Repairs
The maintenance and repairs? Those can be a little bit harder to anticipate. But don’t forget you’ll get an inspection during the homebuying process to give you a better look at the condition of your future house. And with your inspection report in hand, you’ll have a good idea of what needs work. This way, you can start saving up so that you’re ready if and when something breaks.
But even then, if this is something that’s still really nagging at you, talk to your agent about asking the seller to throw in a home warranty. Those can cover repairs for some of the bigger systems in the house, like the HVAC, if they break within a specific time frame. While this isn’t a huge expense for the seller, the likelihood of a seller agreeing to one depends on what’s happening in your local market and how competitive it is right now.
It’s Okay To Stretch – Just Not Too Far
And remember, chances are that money will be a little tight – at least at first. And that’s kind of to be expected. A lot of times when someone buys their first home, they cut down on things like shopping and eating out for a while until they get a better idea of how their expenses will shake out in the new home.
But if you’re crunching the numbers and you won’t have enough money left for things like gas, food, etc. – it’s a sign you’d be stretching yourself too far. The last thing you want is to take on a payment that’s too much to handle. But stretching a little? That’s different. That’s normal.
Your Job Will Probably Change – And That’s Okay
And don’t forget, you’ll likely earn more down the road, so that slight stretch now won’t seem so bad as time wears on. As you advance in your career, you’ll probably start to make more money too. So, as your paycheck grows, the payments will get easier. Renting is a short-term option – and it’s one you deserve to get out of. Buying a home is a long-term play.
And just in case you’re worried about what happens if you do lose your job, you should know there are options, like forbearance, designed to help you temporarily pause payments on your home loan due to hardship.
Bottom Line
Buying your first home or condo is a big decision, and it’s okay to feel a little nervous about it. But if you’re financially ready, don’t let fear keep you from moving forward. These emotions are normal, and great agents help their buyers get through them.
What makes you nervous when you think about buying your first home?
Let’s connect so you have an expert on your side to explain everything along the way. From finding the perfect community for your needs to guiding you through the process, we’re here to help! Contact us today at The Bouma Group, Realtors at 734-761-3060 or info@condohotline.com.
What’s Behind Today’s Mortgage Rate Volatility?
If you’ve been keeping an eye on mortgage rates lately, you might feel like you’re on a roller coaster ride. One day rates are up; the next they dip down a bit. So, what’s driving this constant change? Let’s dive into just a few of the major reasons why we’re seeing so much volatility, and what it means for you.
The Market’s Reaction to the Election
A significant factor causing fluctuations in mortgage rates is the general reaction to the political landscape. Election seasons often bring uncertainty to financial markets, and this one is no different. Markets tend to respond not only to who won but also to the economic policies they are expected to implement. And when it comes to what’s been happening with mortgage rates over the past couple of weeks, as the National Association of Home Builders (NAHB) says:
“. . . the primary reason interest rates have been on the rise pertains to the uncertainty surrounding the presidential election. Although the election is now complete, there continue to be growing concerns over budget deficits.”
In the short term, this anticipation has caused a slight uptick in mortgage rates as the markets adjust and react. Additionally, factors like international tensions, supply chain disruptions, and trade policies can drive investor sentiment, causing them to seek safer assets like bonds, which can indirectly impact mortgage rates. Essentially, the more global or domestic uncertainty, the greater the chance that mortgage rates may shift.
The Economy and the Federal Reserve
Inflation and unemployment are two other big drivers of mortgage rates. The Federal Reserve (the Fed) has been working to bring inflation under control, and has been closely monitoring the economy as they do. And as long as inflation continues to moderate and the job market shows signs of maximum employment, the Fed will continue its plans to cut the Federal Funds Rate.
Although the Fed doesn’t set mortgage rates, their decisions do have an impact, and typically a cut leads to a mortgage rates response. And in their November 6-7th meeting, the Fed had the data they needed to make another cut to the Federal Funds Rate. And while that decision was expected and much of the mortgage rate movement happened prior to that meeting, there was a slight dip in rates.
What To Expect in the Coming Months
As we look ahead, mortgage rates will respond to changes in the Fed’s policies and other economic indicators. The markets will likely remain in a wait-and-see mode, reacting to each new development. And, with the transition of a new administration comes an element of unpredictability. A recent article from The Mortgage Reports explains:
“Today’s economic indicators come with mixed pressures on mortgage rates and we’re likely to be in for a good amount of volatility as markets adjust and respond to the election . . .”
The best way to navigate this landscape is to have a team of real estate experts by your side. Professionals will help you understand what’s happening and can provide you with the guidance you need to make informed housing market decisions along the way.
Bottom Line
The takeaway? Today’s mortgage rate volatility is going to continue to be driven by economic factors and political changes.
Now is the time to lean on experienced professionals. A trusted real estate agent and mortgage lender can help you navigate through it. And with the right guidance, you can make informed decisions. Contact us today at 734-761-3060 or info@condohotline.com.
This Is the Sweet Spot Homebuyers Have Been Waiting For
Today’s Market is a Sweet Spot for Condo and Homebuyers
After months of sitting on the sidelines, many condo and homebuyers who were priced out by high mortgage rates and affordability challenges finally have an opportunity to make their move. With rates trending down, today’s market is a sweet spot for buyers—and it may not last long.
So, if you’ve put your move on the back burner, here’s why maybe you shouldn’t delay your plans any longer.
As you weigh your options and decide if you should buy now or wait, ask yourself this: What do you think everyone else is going to do?
The truth is, if mortgage rates continue to ease, as experts project, more buyers will jump back into the market. A survey from Bankrate shows over half of homeowners would be motivated to buy this year if rates drop below 6% (see graph below):
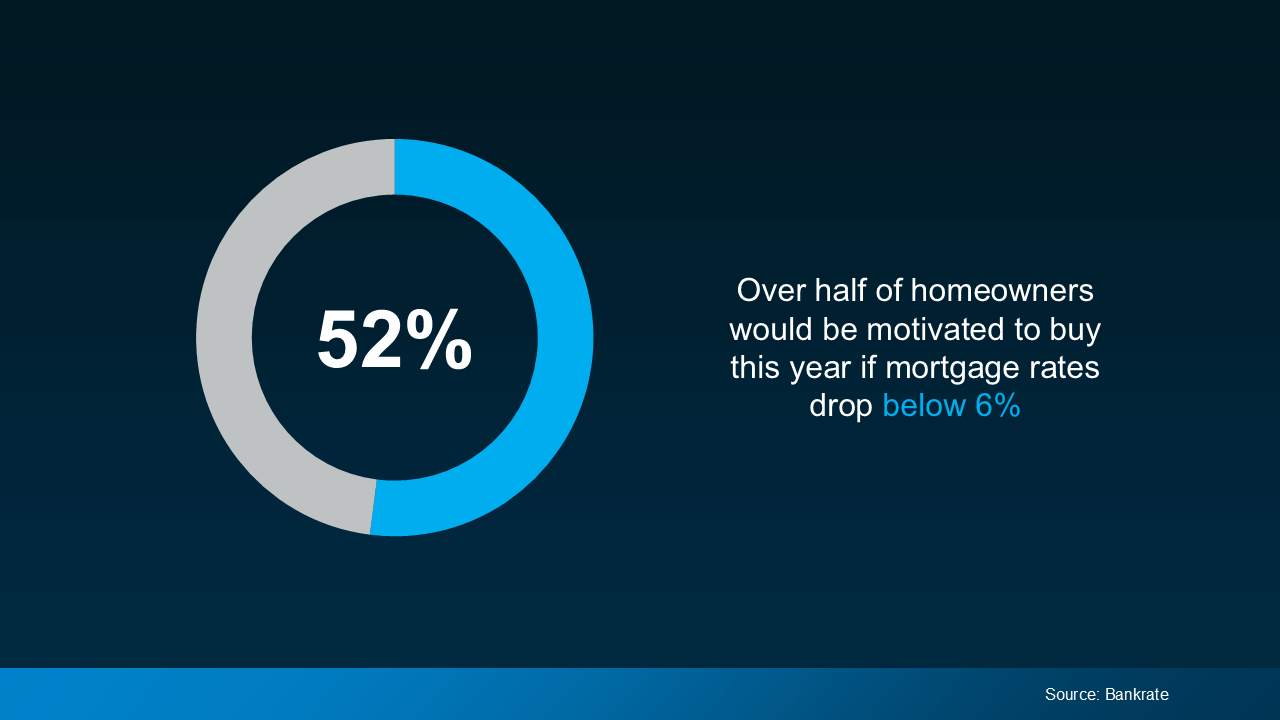
With rates already in the low 6% range, we’re not terribly far off from hitting that threshold. The bottom line is, that when they drop into the 5s, the number of buyers in the market is going to go up – and that means more competition for you.
That increased demand will likely push home prices up, which could potentially take away from some of the benefits you’d gain from a slightly lower interest rate. As Nadia Evangelou, Senior Economist and Director of Real Estate Research at the National Association of Realtors (NAR), explains:
“The downside of increased demand is that it puts upward pressure on home prices as multiple buyers compete for a limited number of homes. In markets with ongoing housing shortages, this price increase can offset some of the affordability gains from lower mortgage rates.”
So, while waiting to buy may seem like a smart move, it could backfire if rising prices outpace your savings from slightly lower rates.
What This Means for You
Right now, you’ve got the chance to get ahead of all of that. Today’s market is a buyer sweet spot. Why? Because a lot of other buyers are waiting – which means not as many people are actively looking for condos and homes. That means less competition for you.
At the same time, affordability has already improved quite a bit. Recent easing in mortgage rates has made homeownership more accessible. As Mike Simonsen, Founder of Altos Research, says:
“Mortgage payments on the typical-price home are 7% lower than last year and are 13% lower than the peak in May 2024.”
And while the supply of homes for sale is still low, it’s also higher than it’s been in years. According to Ralph McLaughlin, Senior Economist at Realtor.com:
“The number of homes actively for sale continues to be elevated compared with last year, growing by 35.8%, a 10th straight month of growth, and now sits at the highest since May 2020.”
This means you now have more options to choose from than you’ve had in quite a while.
With fewer buyers in the market, improving affordability, and more homes to choose from, you have the chance to find the right one before the competition heats up.
Why Waiting Could Cost You
If you’re waiting for the perfect time to buy, it’s important to understand that timing the market is nearly impossible. The longer you wait, the higher the risk that market conditions will shift—and not necessarily in your favor. As Greg McBride, Chief Financial Analyst at Bankrate, says:
“It’s one of those things where you should be careful what you wish for. A further drop in mortgage rates could bring a surge of demand that makes it tougher to actually buy a house.”
Bottom Line
Don’t wait until you have to deal with more competition and higher prices – you already have the chance to buy a condo or home while we’re in the sweet spot today. Let’s connect to make sure you’re taking advantage of it. 734-761-3060 or info@condohotline.com.
Tips for Younger Homebuyers: How To Make Your Dream a Reality
Tips for Younger Homebuyers in Today’s Real Estate Market
If you’re a member of a younger generation, like Gen Z, you may be asking the question: will I ever be able to buy a home? And chances are, you’re worried that’s not going to be in the cards with inflation, rising home prices, mortgage rates, and more seemingly stacked against you.
While there’s no arguing this housing market is challenging for first-time homebuyers, it is still achievable, especially if you have professionals on your side.
Here are some helpful tips:
1. Explore Your Options for a Down Payment
If a down payment is your #1 hurdle, you may have options to give your savings a boost. There are over 2,000 down payment assistance programs designed to make homeownership more achievable. And, that’s not the only place you may be able to get a helping hand. While it may not be an option for everyone, 49% of Gen Z homebuyers got money from loved ones that they used toward a down payment, according to LendingTree.
And chances are you won’t need to put 20% down (unless specified by your loan type or lender). So be sure to work with a trusted mortgage professional to explore your options, find out how much you’ll really need, and learn about any guidelines on getting a gift from loved ones.
2. Live with Loved Ones To Boost Your Savings
Another thing a number of Gen Z buyers are doing is ditching their rental and moving back in with friends or family. This can help cut down your housing costs so you can build your savings a whole lot faster. As Bankrate explains:
“. . . many have opted to stop renting and live with family in order to boost their savings. Thirty percent of Gen Z homebuyers move directly from their family member’s home to a home of their own, according to NAR.”
3. Cast a Broad Net for Your Search
When you’ve saved up enough, here’s how a pro will help you approach your search. Since the supply of condos and homes for sale is still low and affordability is tight, they’ll give you strategies and avenues you may not have considered to open up your pool of options.
For example, it’s usually more affordable if you consider a rural or suburban area versus an urban one. So, while the city may be livelier and more energetic, the cost of living may be reason enough to look at something further out. And if you consider smaller homes and condos or townhouses, you’ll give yourself even more ways to break into the market. As Colby Stout, Research Analyst at Bright MLS, explains:
“Being flexible on the types of home (e.g., a condo or townhome versus a single-family home) and exploring more affordable neighborhoods is important for first-time buyers.”
4. Take a Close Look at Your Wants and Needs
And lastly, an agent can help you really think about your must-have’s and nice-to-have’s. Remember, your first home doesn’t have to be your forever home. You just need to get your foot in the door to start building equity. If you want to buy, you may find making some compromises is worth it. As Chase says:
“An open-minded approach to house-hunting may be one way for Gen Z homebuyers to maintain some edge. This could mean buying in areas that are less expensive. Differentiating needs vs. wants may help in this area as well.”
An agent will help you prioritize your list of home features and find places that can deliver on the top ones. And they’ll be able to explain how equity can benefit you in the long run and make it possible to move into that dream home down the line.
Bottom Line
Real estate professionals have expertise on what’s working for other buyers like you. Lean on them for tips and advice along the way. As Directors Mortgage says, with that support you can make it happen:
“The path to homeownership may not be a straightforward one for Gen Z, but it’s undoubtedly within reach. By adopting the right strategies, like exploring down payment assistance programs and sharing living costs with relatives, you can bring your dream of owning a home closer to reality.”
Let’s connect to get you set up for long-term success. You can reach The Bouma Group, Ann Arbor’s Condo Specialists at 734-761-3060 or info@condohotline.com.
Check out the top 10 most affordable condo complexes in Ann Arbor and see if one may be a good fit for you!
Should I Move with Today’s Mortgage Rates?
Should I Move with Today’s Mortgage Rates?
When mortgage rates spiked up over the last few years, some would-be condo and home buyers put their plans to move on pause. Maybe you did too because you didn’t want to move and take on a higher mortgage rate for your next place. But is that still the right strategy for you?
In today’s market, data shows more homeowners are getting used to where rates are and thinking it may be time to move. As Mark Zandi, Chief Economist at Moody’s Analytics, explains:
“Listings are up a bit as life events and job changes are putting increasing pressure on locked-in homeowners to sell their homes. Homeowners may also be slowly coming to the realization that mortgage rates aren’t going back anywhere near the rate on their existing mortgage.”
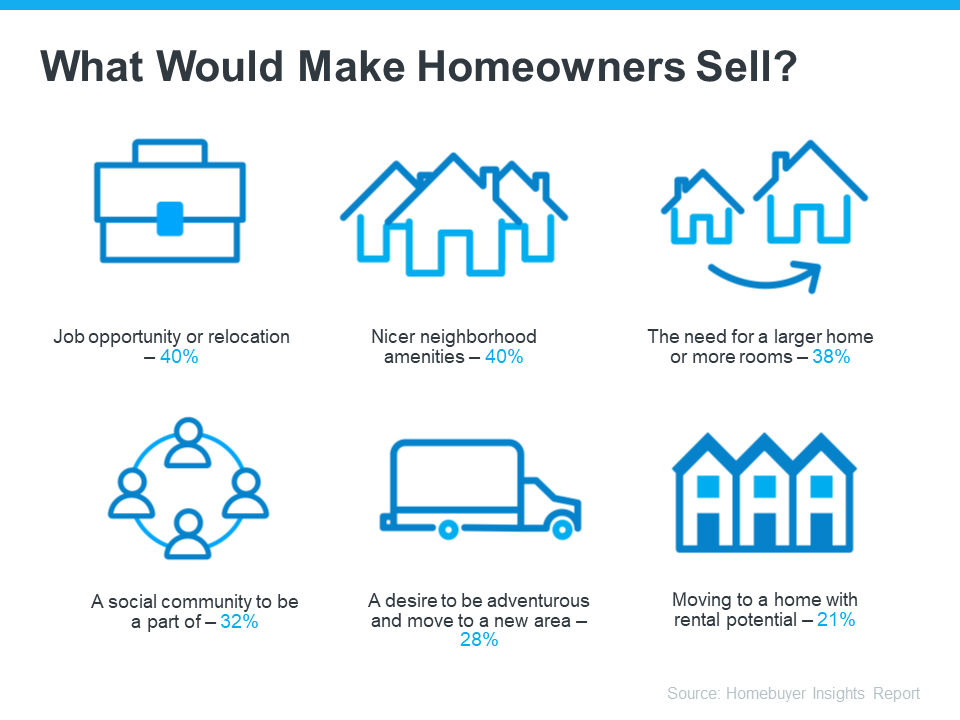
A recent study from Bank of America sheds light on some of the things homeowners say would make them sell, even with rates where they are right now (see visual below):
What Would Motivate You To Move?
Now that you know why other people would move, take a minute to think about what would make a move worth it for you. Is it time to take a chance and go for your dream job, even though it’s not local? Are you looking for a neighborhood with more to offer and a close-knit sense of community? Maybe you need more space, you’re looking for your next great adventure, or you want a condo or house that opens up rental opportunities to pad your income.
And here’s something else to consider. Mortgage rates are still expected to go down over the course of the year. Once that happens, there will be a big rush of buyers jumping back into the market. While you could delay your plans until rates drop, you’ll only have more competition with those buyers if you do.
So, does that mean it’s worth moving now, even with rates where they are? The answer is: that it depends.
You’ll want to consider today’s mortgage rates, where they’re expected to go from here, and what would prompt you to want to make a change as you decide on your next steps. An expert can help with that.
Bottom Line
Other homeowners are getting used to rates and deciding to move. Let’s chat about what matters most and if it’s time for you to jump back into the market too. Contact us today at 734-761-3060 or info@condohotline.com and let’s discuss your options! Check out some different Ann Arbor condo communities here!
Are Higher Mortgage Rates Here To Stay?
Higher Mortgage Rates Are Affecting Purchase Power
Mortgage rates have been back on the rise recently and that’s getting a lot of attention from the press. If you’ve been following the headlines, you may have even seen rates recently reached their highest level in over two decades (see graph below):

That can feel like a little bit of a gut punch if you’re thinking about making a move. If you’re wondering whether or not you should delay your plans, here’s what you really need to know.
How Higher Mortgage Rates Impact You
There’s no denying rates are higher right now than they were in recent years. And, when rates are up, that affects overall home affordability. It works like this. The higher the rate, the more expensive it is to borrow money when you buy a home. That’s because, as rates trend up, your monthly mortgage payment for your future home loan also increases.
Urban Institute explains how this is impacting buyers and sellers right now:
“When mortgage rates go up, monthly housing payments on new purchases also increase. For potential buyers, increased monthly payments can reduce the share of available affordable homes . . . Additionally, higher interest rates mean fewer homes on the market, as existing homeowners have an incentive to hold on to their home to keep their low interest rate.”
Basically, some people are deciding to put their plans on hold because of where mortgage rates are right now. But what you want to know is: is that a good strategy?
Where Will Mortgage Rates Go From Here?
If you’re eager for rates to drop, you’re not alone. A lot of people are waiting for that to happen. But here’s the thing. No one knows when it will. Even the experts can’t say with certainty what’s going to happen next.
Forecasts project rates will fall in the months ahead, but what the latest data says is that rates have been climbing lately. This disconnect shows just how tricky mortgage rates are to project.
The best advice for your move is this: don’t try to control what you can’t control. This includes trying to time the market or guess what the future holds for mortgage rates. As CBS News states:
“If you’re in the market for a new home, experts typically recommend focusing your search on the right home purchase — not the interest rate environment.”
Instead, work on building a team of skilled professionals, including a trusted lender and real estate agent, who can explain what’s happening in the market and what it means for you. If you need to move because you’re changing jobs, want to be closer to family, or are in the middle of another big life change, the right team can help you achieve your goal, even now.
Bottom Line
The best advice for your move is: don’t try to control what you can’t control – especially mortgage rates. Even the experts can’t say for certain where they’ll go from here. Instead, focus on building a team of trusted professionals who can keep you informed. When you’re ready to get the process started, let’s connect today at 734-761-3060 or info@condohotline.com.
Gen Z: The Next Generation Is Making Moves in the Housing Market
Gen Z: The Next Generation Is Making Moves in the Housing Market
Gen Z (Generation Z) is eager to put down their own roots and achieve financial independence. As a result, they’re turning to homeownership. According to the latest Home Buyers and Sellers Generational Trends Report from the National Association of Realtors (NAR), 30% of Gen Z buyers transitioned straight from living under their parents’ roofs to owning their own homes.
If you’re a member of this generation, and you’re interested in pursuing your own dream of homeownership, here’s some information you may find helpful on why and where your peers are buying.
The Reasons Gen Z Want To Become Homeowners
A recent survey by Rocket Mortgage identifies some of the top motivators driving Gen Z buyers to purchase a home:
“Of those surveyed, 34% said that starting or growing their family was their main motivation to buy a home. . . . Along with growing a family comes establishing a home base.”
Another key reason the survey says Gen Z wants to buy is because homeownership can give them more stability (20.8%). That’s because buying a home allows you to stabilize what’s typically your biggest monthly expense: your housing cost.
When you have a fixed-rate mortgage on your home, you can lock in your monthly payment for the duration of your loan, often 15 to 30 years. If you keep renting, you don’t have that same benefit, and you won’t be protected from rising housing costs.
So, if you’re ready to start a new chapter in your life or if you’re craving more stability, know that your peers feel the same way, and those motivators are why they’re turning to homeownership.
Gen Z’s Next Stop: Where Are They Making Their Moves?
If those reasons have you feeling ready to buy, here’s some information on where your peers are finding their homes that could help you with your search. According to a recent Lending Tree survey, Gen Z buyers are focusing on more affordable areas to help boost their buying power and offset the challenges that come with today’s mortgage rates.
Many Gen Z buyers still want the convenience and excitement of city life, but also value the affordability, open air, and space more suburban areas offer. Jacob Channel, Senior Economist at LendingTree, explains:
“. . . they want to live in a city, but they also want to be close to nature.”
Locating a home that offers both of those things requires expertise. Working with a trusted real estate professional can help you find a home in your budget and desired area. Your agent will know the most affordable neighborhoods to search in. They can also highlight the amenities and features that the location offers and how those are aligned with your goals. They’ll also be able to walk you through how things like remote work can help you cast a broader net for your search.
Bottom Line
If you’re a member of Gen Z and are just getting started on your homebuying journey, or if you want to learn more about the process, let’s connect. That way, you have a guide to help you find a home that fits both your lifestyle and your budget. Contact us at The Bouma Group, Realtors today at 734-761-3060 or info@condohotline.com, and let’s get started!